
Apple's robust Q3 FY2020 (quarter ended June 2020) results highlighted by higher than expected product sales was quite impressive considering challenging circumstances and supply disruptions amid the pandemic. Consequently, we revise our top and bottom line forecasts upwards for 2020E, and 2021E, to $274 billion ($264 billion earlier) and $300 billion ($291 billion), respectively, and accordingly revise our target price to $451.69 from $409.26.
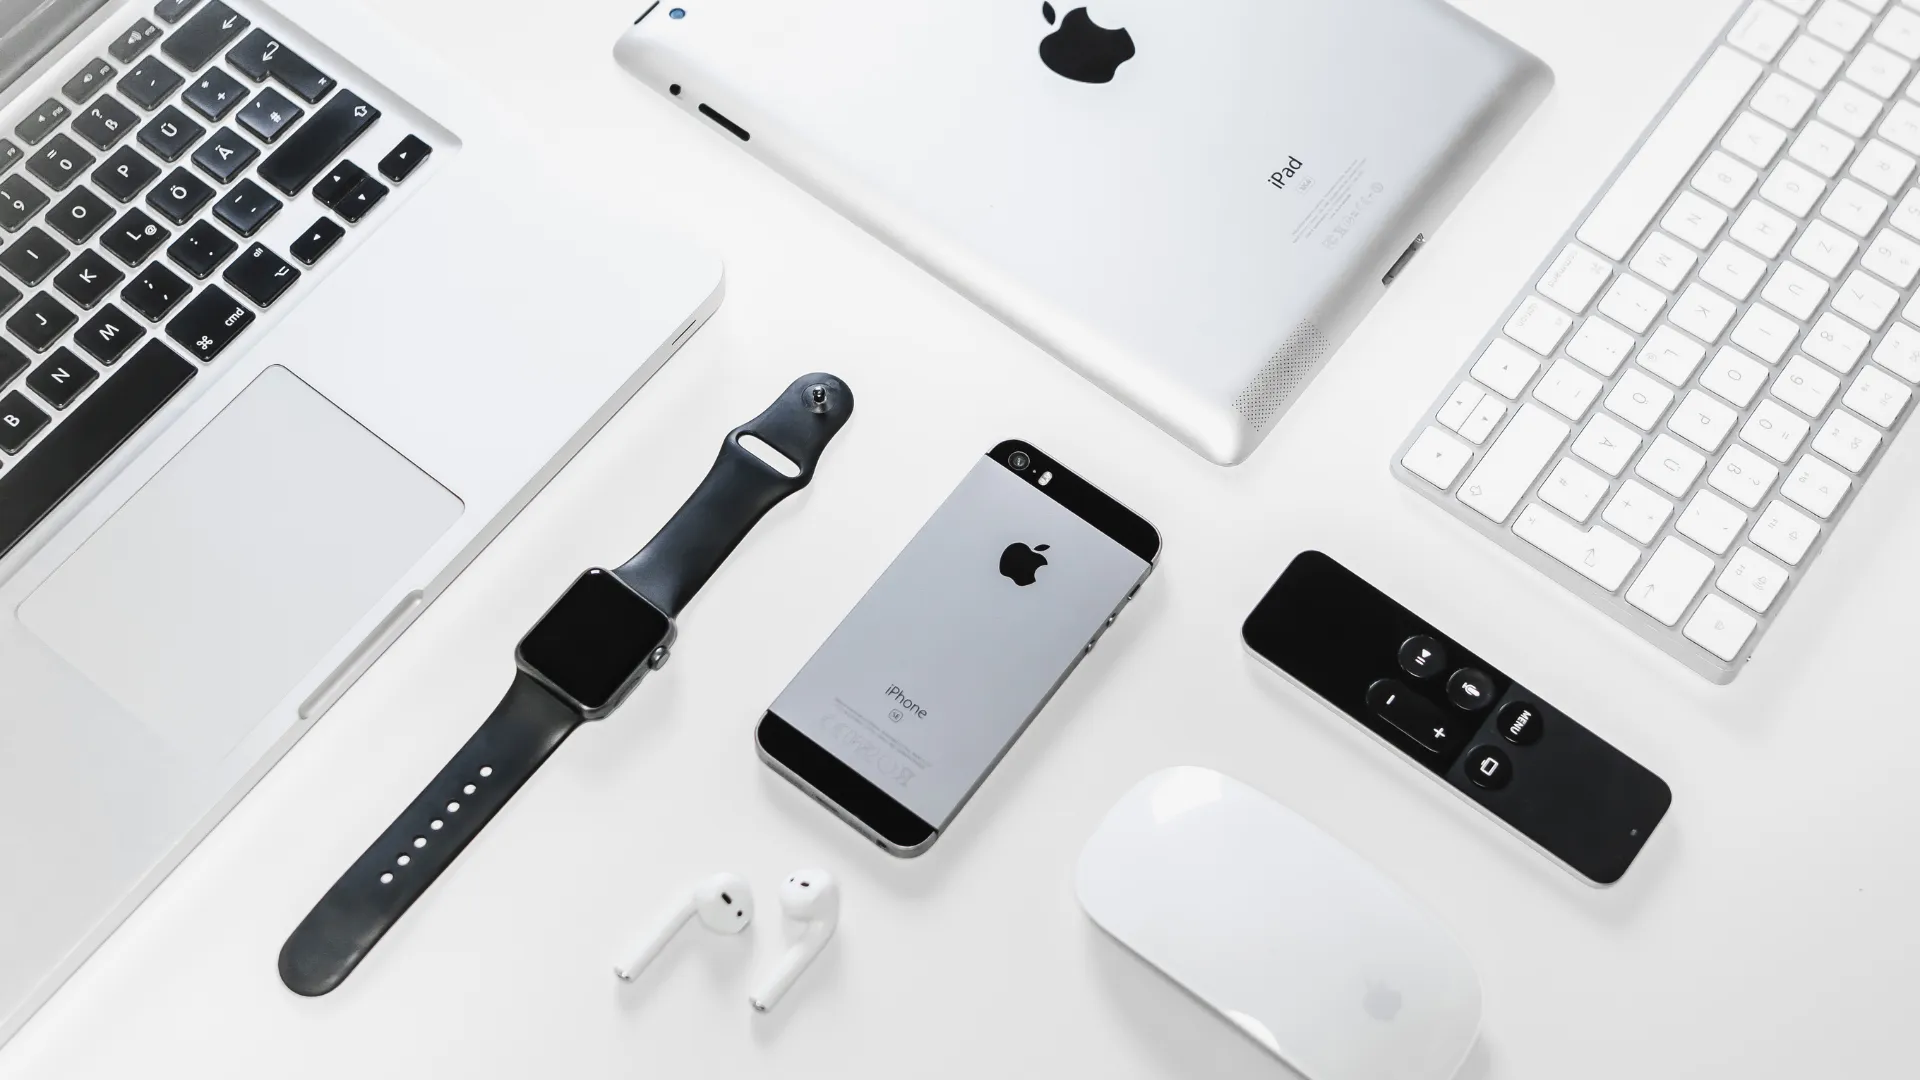
Robust Product Sales Amid Work From Home Trend Drive Q3 Earnings; Downgrading
Paused · 15:38 left · FRC · read by an AI voice
Disclosure: See the disclosures at the end of this report, and the last page of the PDF, for important disclosures, rating, and risk definitions.
All figures in US$ unless otherwise specified.
Strong growth in both Products and Services drives Q3 revenues. Specifically, total net sales increased 11% y/y to $59.7 billion, well above our forecast of $51.5 billion. The beat is primarily attributable to strong product sales (+10% vs. our forecast of ~9% drop) aided by the work from home trend, while services revenues were largely in line (+15% vs. +14%) with our estimates.
We believe this renewed strength in devices, and continued strong services revenue stream, will boost AAPL’s earnings in the near term. Accordingly, we see total net sales of $274 billion in FY 2020 ($264 billion earlier), and $300 billion ($291 billion earlier) in FY 2021, implying 5.4% and 9.5% growth.
| YTD | 12M | |
|---|---|---|
| Ret. | 48.4% | 113.6% |
| SPX | 10.2% | -2.7% |
| Key Financial Data (YE Sept 30, $ million) | 2020 (9M) | 2020E | 2021E |
|---|---|---|---|
| Cash, cash equivalent and marketable securities | 193,617 | 197,568 | 182,335 |
| Working Capital | 44,747 | 66,573 | 69,152 |
| Total Assets | 317,344 | 320,506 | 309,200 |
| Revenue | 209,817 | 274,100 | 300,073 |
| Net Income | 44,738 | 57,390 | 63,244 |
| EPS Diluted ($) | 10.13 | 13.06 | 15.96 |
Contrary to the muted guidance given by the company in April, iPhone sales edged up 2% y/y to $26.4 billion, beating our forecast by more than $5 billion. The growth was attributable to better-than-expected demand in May and June on reopening of stores, continued economic stimulus, and stronger demand for new models particularly the iPhone SE. This drove the installed base of iPhones to a new all-time high (management did not reveal the exact figure though).
Based on preliminary data from IDC, iPhone shipments may have jumped ~11% in calendar Q2 2020 vs. Q2 2019, to 37.6 million while overall smartphones shipments fell 17%, attributable to the factors discussed above. We expect this trend to continue in Q4, driving total iPhone units for FY 2020 to ~190 million. Accordingly, we revise our revenue forecast for iPhone to $141 billion from $135 billion earlier for FY 2020.
| Units (Mn) | Q2 2019 | Prel. Q2 2020 | Growth |
|---|---|---|---|
| Huawei | 58.73 | 55.76 | -5% |
| Samsung | 76.22 | 52.48 | -31% |
| Apple | 33.79 | 37.57 | 11% |
| Xiaomi | 32.26 | 28.45 | -12% |
| Oppo | 29.53 | 23.96 | -19% |
| Vivi | 28.35 | 23.65 | -17% |
| Other | 72.59 | 54.78 | -25% |
| Total Smartphones | 331.47 | 276.65 | -17% |
Mac and IPad sales surged 22% and 31% respectively. Specifically, Mac revenue surged 22% y/y to $7.1 billion (vs. our forecast of $5.9 billion), primarily attributable to the work from home trend as well the launch of new models of MacBook Air and MacBook Pro. We expect this strong growth to continue in the near term on the work from home trend, and accordingly, revise our Mac revenue forecast to $7.3 billion for Q4 FY20 ($7.1 billion earlier), taking annual revenues to $26.9 billion ($25.5 billion previously).
Similar to Mac, iPad also saw strong growth during the quarter on the back of the work and learn from home trend across geographies as well as new model launches. Revenues shot up 31% to $6.6 billion, marking AAPL’s highest June quarter revenues for iPad in eight years. We expect this trend to continue in Q4 and accordingly revise our forecast to $5.6 billion ($4.7 billion earlier), which takes full year 2020 revenues to $22.5 billion ($20 billion earlier).
Wearables, Home and Accessories grew 17% in line with our forecasts. However, the one segment that continued its decelerating growth trend within the products segment is Wearables, Home and Accessories. Although revenues increased 17% y/y to a third quarter record of $6.5 billion and largely in-line with our forecast, the growth has decelerated from 23% and 37% in Q2 and Q1, respectively.
Management noted on the earnings call that the deceleration in this quarter was due to store closures in April as potential customers like to try wearable products, like the Apple Watch, before buying, unlike iPhones. Accordingly, we are revising downwards our revenues for this segment to $7.2 billion in Q4 ($7.8 billion earlier), which takes annual revenues to $29.9 billion ($30.6 billion earlier).
During the quarter, Services revenues grew 15% to $13.2 billion (in-line with our forecast of $13.1 billion). The key focus area of Apple, services continues to grow at high double-digit growth rates (~16% over the past six quarters), attributable to the large installed base of active devices with deep integration of hardware, software and services.
This consistent growth has enabled AAPL to achieve its goal of doubling 2016 services revenue six months ahead of schedule. Apple now has over 550 million paid subscribers, 130 million more than a year ago, and the firm expects 600 million subs by December 2020.
We believe the services revenue will continue to be stable and consistent over the medium term, leveraging the large installed base. For 4Q, we have marginally revised upwards our revenue forecasts to $14.1 billion ($13.8 billion previously).
Gross margins increased y/y but fell q/q. Specifically, gross profit came in at $22.7 billion (+12% y/y), implying gross margins of 38.0%, up 41 bps y/y on an uptick in services margins (+309 bps to 67.2%) and down 40 bps q/q due to unfavorable forex movement. Consequently, we have reduced gross margins to 38.5% in Q4 from 39% earlier.
Total operating expenses increased 10% y/y to $9.6 billion, with research and development expenses and selling, general and administrative increasing by 12% and 9% respectively. However, operating income increased 13% y/y to $13.1 billion, implying a margin of 21.9%. We assume operating expenses of $9.9 billion for 4Q, at the higher end of the management guidance range of $9.8-$9.9 billion.
| Margin Analysis | Q3-2019 | Q3-2020 | y/y Change |
|---|---|---|---|
| Gross | 37.6% | 38.0% | 41 bps |
| EBITDA | 26.9% | 26.5% | -36 bps |
| EBIT | 21.5% | 21.9% | 48 bps |
| Net | 18.7% | 18.9% | 19 bps |
Diluted EPS grew 18% to 2.58. Based on the above factors, net income came in at $11.2 billion (+12% y/y) or $2.58 per diluted share (+18% y/y and above our forecasts of $2.18). Our forecasts for net income have increased to $57.4 billion or $13.06 per diluted share for FY20 ($54.6 billion or $12.43 per diluted share earlier) while that of FY21 have marginally increased to $63.2 billion or $15.96 per diluted share ($15.63).
FCF came in at $14.4 billion. Additionally, Apple ended the quarter with a healthy cash balance of $193.6 billion (including cash equivalents and marketable securities). Total debt (including short term and long term) was $112.7 billion, translating into a net-cash position of $80.9 billion.
Operating cash flows came in at $60 billion for the 9M of FY2020, while capex came in at $7.0 billion, translating into FCF of $53 billion. This solid free cash flow generation enables Apple to continue with aggressive share repurchases and dividend payments while pursuing new opportunities. Our FCF comes at $70 billion and $71 billion for FY20 and FY21 ($65 billion and $69 billion previously).
Considering upbeat third quarter results for FY20, we have revised upwards our forecasts for FY20 and FY21 as well as our target price.
| Old Forecasts | New Forecasts | |||
|---|---|---|---|---|
| Line Items | 2020 | 2021 | 2020 | 2021 |
| Revenue ($ mn) | 264,378 | 290,822 | 274,100 | 300,073 |
| EBITDA ($ mn) | 74,289 | 83,902 | 77,716 | 86,187 |
| Net Income ($mn) | 54,608 | 61,707 | 57,390 | 63,244 |
| EPS ($) | $12.43 | $15.63 | $13.06 | $15.96 |
| Comparable Companies | Price/FCF FY20E | Price/FCF FY21E | Price/FCF FY22E | P/E FY20E | P/E FY21E | P/E FY22E |
|---|---|---|---|---|---|---|
| Apple Inc | 26.77 | 26.22 | 25.82 | 33.36 | 27.30 | 24.86 |
| Samsung Electronics Co Ltd | 15.17 | 12.92 | 9.06 | 15.50 | 11.11 | 9.96 |
| Nokia Oyj | 42.75 | 17.79 | 13.85 | 17.39 | 14.06 | 12.53 |
| Microsoft Corp | 33.24 | 30.76 | 27.07 | 33.57 | 29.62 | 26.32 |
| Alphabet Inc | 33.87 | 24.90 | 20.11 | 28.91 | 22.79 | 19.14 |
| Amazon.com Inc | 53.24 | 35.80 | 26.40 | 68.55 | 53.05 | 40.18 |
| International Business Machines Corp | 9.21 | 9.50 | 8.89 | 11.23 | 10.18 | 9.46 |
| HP Inc | 10.57 | 8.21 | 7.50 | 8.46 | 7.59 | 6.39 |
| Dell Technologies Inc | 10.79 | 6.96 | 6.38 | 10.53 | 9.46 | 8.84 |
| Lenovo Group Ltd | 74.86 | 60.70 | 21.33 | 83.79 | 66.58 | 55.23 |
| Average Market Multiples | 31.0x | 23.4x | 16.6x | 31.1x | 25.2x | 21.3x |
| Median Market Multiples | 30.0x | 21.3x | 17.0x | 23.1x | 18.4x | 15.8x |
Raising our target price to $451.69 from $409.26 earlier. We raise our fair value to $451.69 from $409.26 earlier to reflect strong quarterly results and our upward revision of earnings and FCF for 2020E and 2021E. Accordingly, we assume marginally higher multiples for both P/FCF (27.0x vs. 25.0 earlier) and P/E (29.0x vs. 27.0x) to arrive at a revised fair value of ~$451.69 per share for Apple.
| Relative Valuation - AAPL | |
|---|---|
| FCF 2021E ($ million) | 71,050 |
| EPS 2021E ($) | 16.0 |
| Target Price/FCF multiple for 2021E (x) | 27.0x |
| Target P/E multiple for 2021E (x) | 29.0x |
| Fair value per share ($) - P/FCF Multiple | 440.52 |
| Fair value per share ($) - P/E Multiple | 462.87 |
| Valuation Method | Fair Value per share ($) | Weight | Weighted value per share ($) | Upside/downside |
|---|---|---|---|---|
| Relative Valuation - P/FCF | 440.5 | 50.0% | 220.258 | 1.1% |
| Relative Valuation - P/E | 462.9 | 50.0% | 231.433 | 6.2% |
| Target Price ($) | 451.69 | |||
| CMP ($) (As of Aug 03, 2020) | 435.75 | |||
| Upside/(Downside) | 3.7% | |||
| Forward Dividend Yield 2021E | 1.0% | |||
| Total return Including dividend | 4.6% |
Based on the above, we are raising our fair value estimate from $409.26 to $451.69 per share, but revise our rating from BUY to HOLD as the total expected return is 5%, which is under our threshold for a BUY rating. See last page for our ratings definitions.
We believe the company is exposed to the following risks (list is non-exhaustive):
We are maintaining a risk rating of 2 (Below Average Risk).
| Income Statement (YE Sept 30, $ million) | 2020E | 2021E | 2022E |
|---|---|---|---|
| Products | 220,744 | 239,247 | 251,930 |
| Services | 53,356 | 60,826 | 68,125 |
| Total Revenue | 274,100 | 300,073 | 320,055 |
| COGS | 168,763 | 183,045 | 196,194 |
| Gross Margin | 105,338 | 117,029 | 123,861 |
| Research and development | 18,595 | 19,505 | 20,804 |
| Sales and marketing | 20,123 | 22,505 | 24,004 |
| EBIT | 66,620 | 75,018 | 79,054 |
| Depreciation and Amortization | 11,096 | 11,169 | 11,441 |
| EBITDA (calculated) | 77,716 | 86,187 | 90,495 |
| Other income (expense) | 723 | 723 | 723 |
| EBT | 67,343 | 75,741 | 79,777 |
| Provision for income taxes | 9,952 | 12,497 | 13,163 |
| Net Income | 57,390 | 63,244 | 66,613 |
| EPS (basic) | 13.16 | 14.67 | 15.45 |
| Shares | 4,313 | 4,313 | 4,313 |
| Balance Sheet (YE Sept 30, $ million) | 2019 | 2020E | 2021E | 2022E |
|---|---|---|---|---|
| Assets | ||||
| Cash, cash equivalents and markatable securities | 205,898 | 197,568 | 182,335 | 167,336 |
| Accounts receivable, net | 22,926 | 17,612 | 19,731 | 21,922 |
| Inventories | 4,106 | 3,438 | 3,510 | 4,300 |
| Property and equipment, net | 37,378 | 35,709 | 37,444 | 39,765 |
| Other assets | 68,208 | 66,180 | 66,180 | 66,180 |
| Total assets | 338,516 | 320,506 | 309,200 | 299,502 |
| Liabilities and stockholders’ equity | ||||
| Accounts payable | 46,236 | 36,639 | 41,019 | 44,025 |
| Commercial paper and repurchase agreement | 5,980 | 11,166 | 11,166 | 11,166 |
| Short-term debt | 10,260 | 7,509 | 7,509 | 7,509 |
| Long-term debt | 91,807 | 100,038 | 90,199 | 80,360 |
| Other liabilities | 93,745 | 97,014 | 97,014 | 97,014 |
| Total liabilities | 248,028 | 252,366 | 246,907 | 240,074 |
| Common stock and paid-in capital | 45,174 | 50,440 | 57,791 | 65,633 |
| Retained earnings | 45,898 | 18,251 | 5,051 | -5,655 |
| Accumulated other comprehensive income/(loss) | -584 | -550 | -550 | -550 |
| Total stockholders’ equity | 90,488 | 68,140 | 62,293 | 59,428 |
| Total liabilities and stockholders’ equity | 338,516 | 320,506 | 309,200 | 299,502 |
| Cash Flow (YE Sept 30, $ million) | 2019 | 2020E | 2021E | 2022E |
|---|---|---|---|---|
| Operating activities: | ||||
| Net income | 55,256 | 57,390 | 63,244 | 66,613 |
| Depreciation and amortization | 12,547 | 11,096 | 11,169 | 11,441 |
| Share-based compensation expense | 6,068 | 6,849 | 7,352 | 7,841 |
| Other | -992 | 88 | 0 | 0 |
| Accounts receivable, net | 245 | 5,419 | -2,119 | -2,191 |
| Inventories | -289 | 550 | -73 | -790 |
| Accounts payable | -1,923 | -9,473 | 4,380 | 3,006 |
| Other current and non-current liabilities | -1,521 | 7,441 | 0 | 0 |
| Cash generated by operating activities | 69,391 | 79,360 | 83,953 | 85,921 |
| Investing activities: | ||||
| Purchases of marketable securities | -39,630 | -96,606 | 0 | 0 |
| Proceeds from maturities of marketable securities | 40,102 | 64,865 | 10,000 | 10,000 |
| Proceeds from sales of marketable securities | 56,988 | 49,760 | 10,000 | 10,000 |
| Payments for acquisition of property, plant and equipment | -10,495 | -8,096 | -12,003 | -12,802 |
| Payments made in connection with business acquisitions, net | -624 | -1,666 | -900 | -960 |
| Other | -445 | |||
| Cash generated by/(used in) investing activities | 45,896 | 7,416 | 7,097 | 6,238 |
| Financing activities: | ||||
| Payments for dividends and dividend equivalents | -14,119 | -14,108 | -16,443 | -17,319 |
| Repurchases of common stock | -66,897 | -70,171 | -60,000 | -60,000 |
| Proceeds from issuance of term debt, net | 6,963 | 19,135 | 0 | 0 |
| Repayments of term debt | -8,805 | -15,139 | -9,839 | -9,839 |
| Other | -8,118 | 2,272 | 0 | 0 |
| Cash used in financing activities | -90,976 | -78,011 | -86,282 | -87,158 |
| Increase/(Decrease) in cash, cash equivalents and restricted cash | 24,311 | 8,766 | 4,768 | 5,001 |
| Cash, cash equivalents and restricted cash, beginning balances | 25,913 | 50,224 | 58,990 | 63,757 |
| Cash, cash equivalents and restricted cash, ending balances | 50,224 | 58,990 | 63,757 | 68,758 |
| Restricted cash included in other current assets | 23 | 1,656 | 1,656 | 1,656 |
| Restricted cash included in other non-current assets | 1,357 | 0 | 0 | 0 |
| Cash and cash equivalents | 48,844 | 57,334 | 62,101 | 67,102 |
Sid Rajeev, B.Tech, CFA, MBA — Head of Research, Fundamental Research Corp.
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Disclosures. No fees were paid by AAPL to FRC. Fundamental Research Corp. “FRC” owns shares of the subject company, but does not make a market or offer shares for sale of the subject company, and does not have any investment banking business with the subject company. The Analyst does not own shares of the subject company. Hold – Annual expected rate of return is between 5% and 12% for micro / small-cap companies, and 5% and 8% for mid / large-cap companies. 2 (Below Average Risk) - The company operates in an industry where the fundamentals and outlook are positive. The industry and company are relatively less sensitive to systematic risk than companies with a Risk Rating of 3. The company has a history of profitability and has demonstrated its ability to generate positive free cash flows (though current free cash flow may be negative due to capital investment). The company’s capital structure is conservative with little to modest use of debt. The distribution of FRC’s ratings are as follows: BUY (67%), HOLD (8%), SELL / SUSPEND (25%). ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST.


Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.