
Given the progress since our last report, including rising international support, government funding, and the Nasdaq uplisting, we have reduced our discount rate assumption from 13.0% to 11.6%, in line with the rate we typically apply to advanced-stage development projects in relatively safe jurisdictions. We reiterate our BUY rating, and raise our fair value estimate from $3.16 to $3.61/share, reflecting the company's continued progress in advancing its integrated LFP supply chain, strong government and institutional support, and improving market positioning.
Moving to the Big Leagues: Nasdaq Listing & Growing Global Support
Paused · 9:27 left · FRC · read by an AI voice
Disclosure: First Phosphate Corp has paid FRC a fee for research coverage and distribution of reports. This fee creates a potential conflict of interest which readers should consider. See last page for other important disclosures, rating, and risk definitions.
All figures in C$ except for commodity prices, which are in US$.
Price and Volume (1-year)
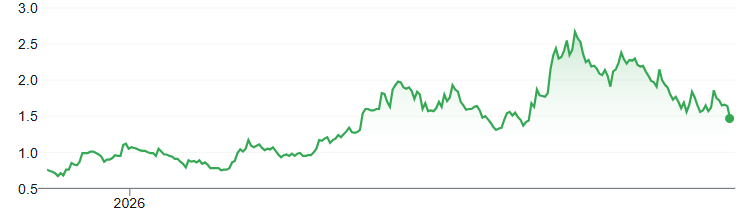
| YTD | 12M | |
|---|---|---|
| PHOS | 23% | 81% |
| CSE | -33% | -18% |
| SETM* | -28% | -23% |
| Key Financial Data (FYE - Feb 28) | 2027 (6M) | Current (FRC Est.) |
|---|---|---|
| Cash | $19,949,271 | ~$17,800,000 |
| Working Capital | $22,668,760 | |
| Mineral Assets | $3,638,061 | |
| Total Assets | $30,776,289 | |
| Net Income (Loss) | -$19,504,359 | |
| EPS | -$0.11 |
PHOS owns two advanced-stage phosphate projects in Quebec, an emerging Canadian hub for battery metals, while primarily focused on advancing Bégin-Lamarche towards production.
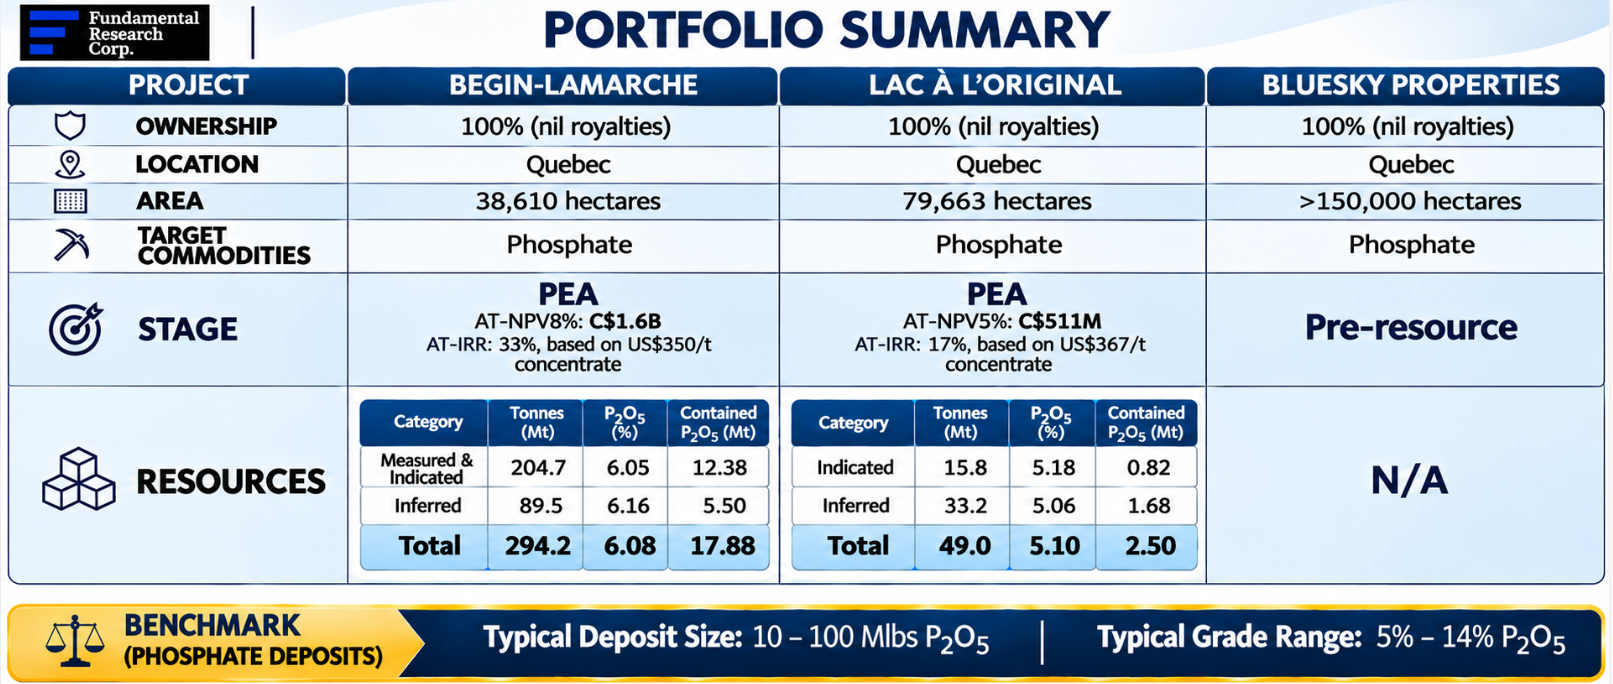
PORTFOLIO SUMMARY
| PROJECT | BEGIN-LAMARCHE | LAC À L'ORIGINAL | BLUESKY PROPERTIES |
|---|---|---|---|
| OWNERSHIP | 100% (nil royalties) | 100% (nil royalties) | 100% (nil royalties) |
| LOCATION | Quebec | Quebec | Quebec |
| AREA | 38,610 hectares | 79,663 hectares | >150,000 hectares |
| TARGET COMMODITIES | Phosphate | Phosphate | Phosphate |
| STAGE | PEA AT-NPV8%: C$1.6B AT-IRR: 33%, based on US$350/t concentrate |
PEA AT-NPV5%: C$511M AT-IRR: 17%, based on US$367/t concentrate |
Pre-resource |
| RESOURCES | N/A | ||
| BENCHMARK (PHOSPHATE DEPOSITS) | |||
| Typical Deposit Size: 10 – 100 Mlbs P2O5 | Typical Grade Range: 5% – 14% P2O5 | ||
| Category | Tonnes (Mt) | P2O5 (%) | Contained P2O5 (Mt) |
|---|---|---|---|
| Measured & Indicated | 204.7 | 6.05 | 12.38 |
| Inferred | 89.5 | 6.16 | 5.50 |
| Total | 294.2 | 6.08 | 17.88 |
| Category | Tonnes (Mt) | P2O5 (%) | Contained P2O5 (Mt) |
|---|---|---|---|
| Indicated | 15.8 | 5.18 | 0.82 |
| Inferred | 33.2 | 5.06 | 1.68 |
| Total | 49.0 | 5.10 | 2.50 |
PHOS is developing a fully integrated supply chain, from high-purity phosphate extraction to cathode active material (CAM) production, targeting high-growth markets including energy storage, AI data centres, robotics, automation, and electric vehicles (EVs).
Business Plan
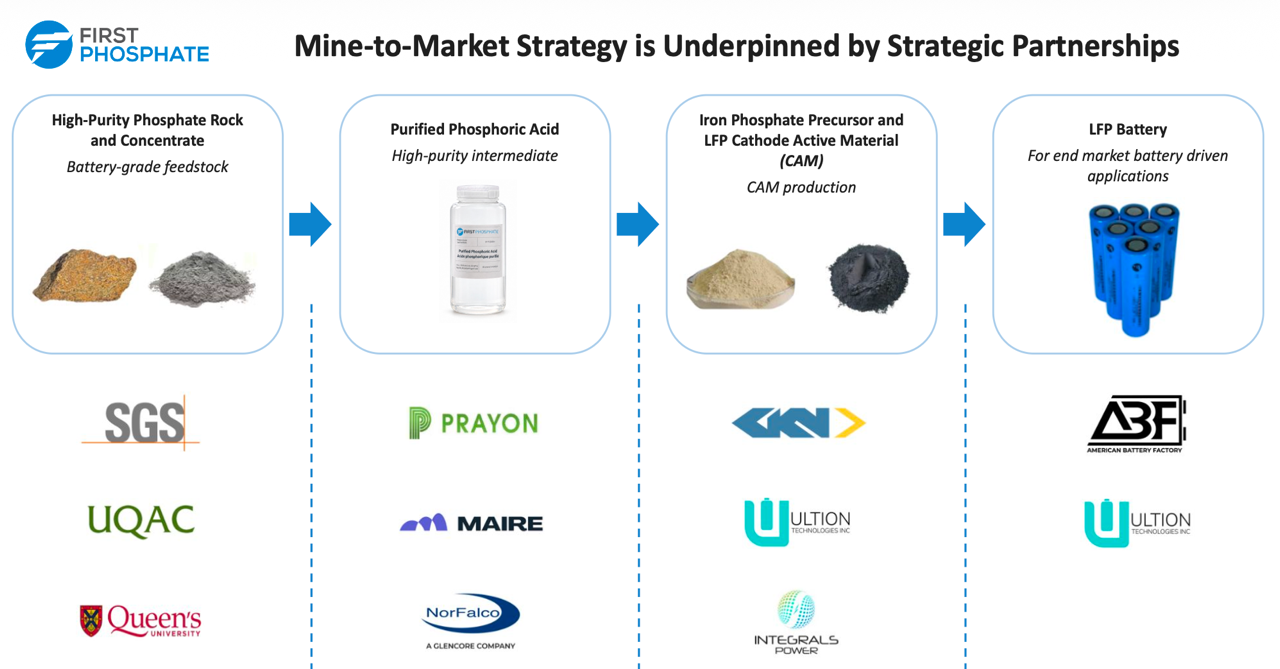
Product prices increase at each stage of production, reflecting value added through incremental OPEX and CAPEX investments.
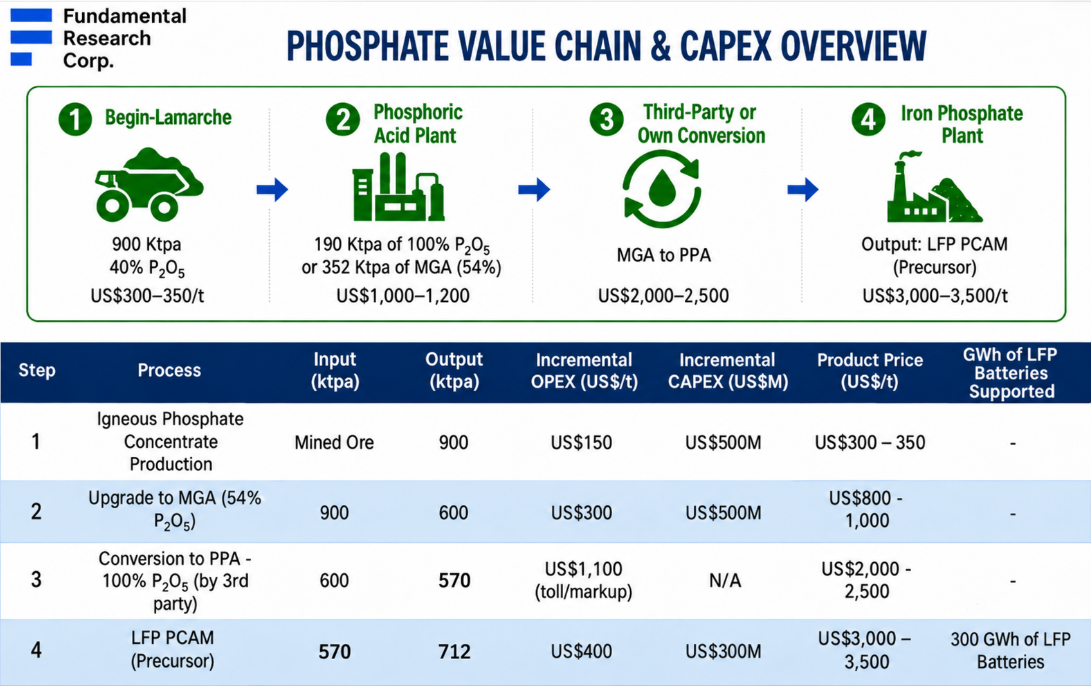
PHOSPHATE VALUE CHAIN & CAPEX OVERVIEW
| Step | Process | Input (ktpa) | Output (ktpa) | Incremental OPEX (US$/t) | Incremental CAPEX (US$M) | Product Price (US$/t) | GWh of LFP Batteries Supported |
|---|---|---|---|---|---|---|---|
| 1 | Igneous Phosphate Concentrate Production | Mined Ore | 900 | US$150 | US$500M | US$300 – 350 | - |
| 2 | Upgrade to MGA (54% P2O5) | 900 | 600 | US$300 | US$500M | US$800 - 1,000 | - |
| 3 | Conversion to PPA - 100% P2O5 (by 3rd party) | 600 | 570 | US$1,100 (toll/markup) | N/A | US$2,000 - 2,500 | - |
| 4 | LFP PCAM (Precursor) | 570 | 712 | US$400 | US$300M | US$3,000 – 3,500 | 300 GWh of LFP Batteries |
Phosphate is designated as a critical mineral by the U.S., EU, and Canada because of its critical role in fertilizer production, and modern battery technologies, while facing concentrated global supply chains.
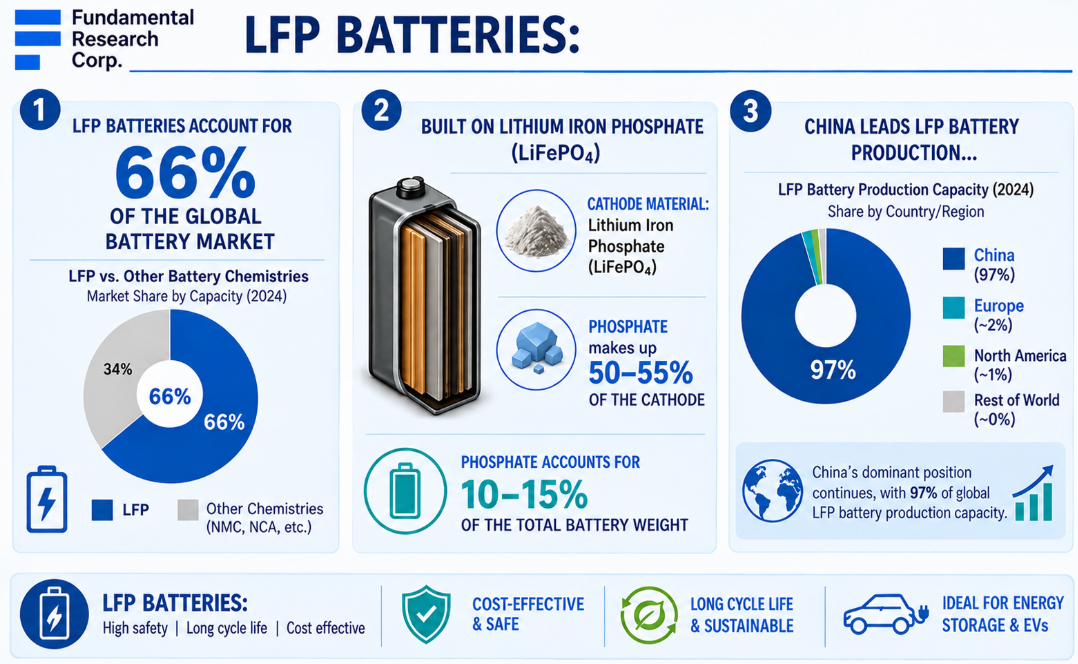
LFP batteries dominate global battery demand, in turn driving demand for secure phosphate supply chains. Near-term growth is tempered by slower EV demand growth, but the long-term outlook remains strong, supported by rising demand for grid-scale energy storage, and renewable energy integration.
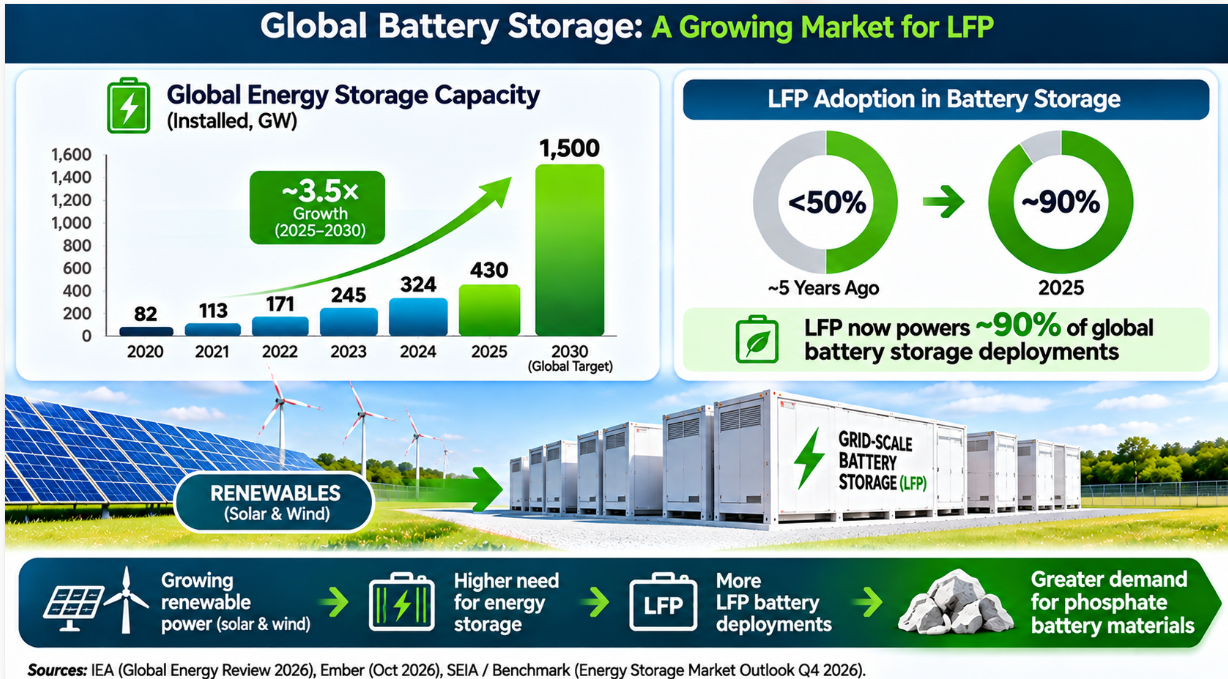
Renewables growth is accelerating demand for energy storage. In addition, LFP adoption in energy storage creates an additional source of phosphate demand.
We believe the Bégin-Lamarche project is capable of supplying phosphate feedstock for decades of LFP cathode production. Mineralization extends from surface to 400 m depth, with significant resource expansion potential as the deposit remains open at depth.
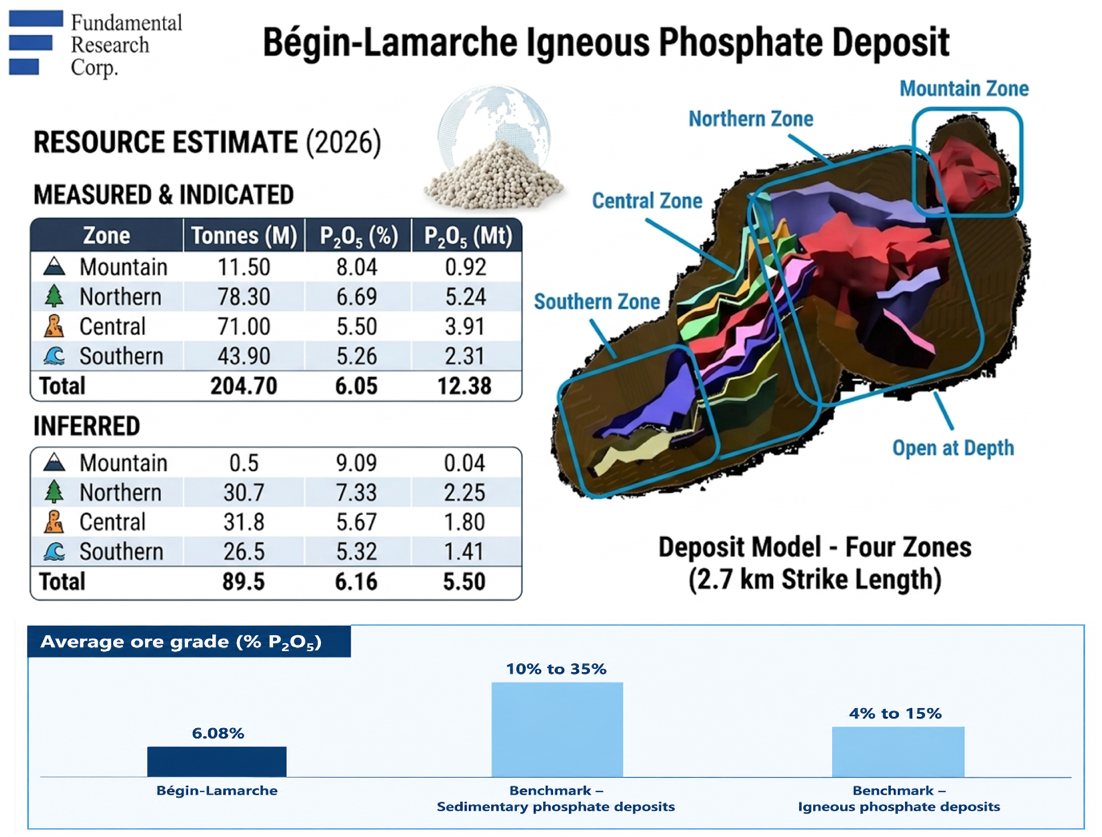
MEASURED & INDICATED
| Zone | Tonnes (M) | P2O5 (%) | P2O5 (Mt) |
|---|---|---|---|
| Mountain | 11.50 | 8.04 | 0.92 |
| Northern | 78.30 | 6.69 | 5.24 |
| Central | 71.00 | 5.50 | 3.91 |
| Southern | 43.90 | 5.26 | 2.31 |
| Total | 204.70 | 6.05 | 12.38 |
INFERRED
| Zone | Tonnes (M) | P2O5 (%) | P2O5 (Mt) |
|---|---|---|---|
| Mountain | 0.5 | 9.09 | 0.04 |
| Northern | 30.7 | 7.33 | 2.25 |
| Central | 31.8 | 5.67 | 1.80 |
| Southern | 26.5 | 5.32 | 1.41 |
| Total | 89.5 | 6.16 | 5.50 |
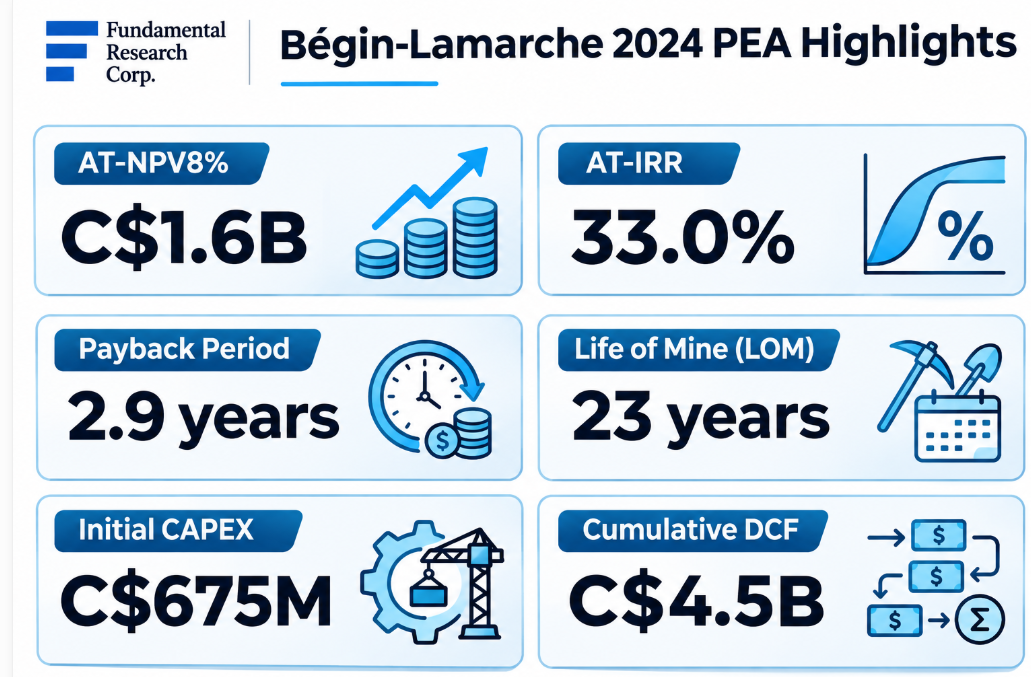
An independent 2024 PEA estimated an after-tax NPV8% of $1.59B, and IRR of 33.0%. We consider IRRs above 25% attractive.
A key advantage for PHOS is the strong government and international support it has secured to date, with over $800M in announced commitments and grants. Strong government backing helps de-risk project development. We believe international support positions PHOS as a strategic Western phosphate supplier, strengthening battery supply-chain security.
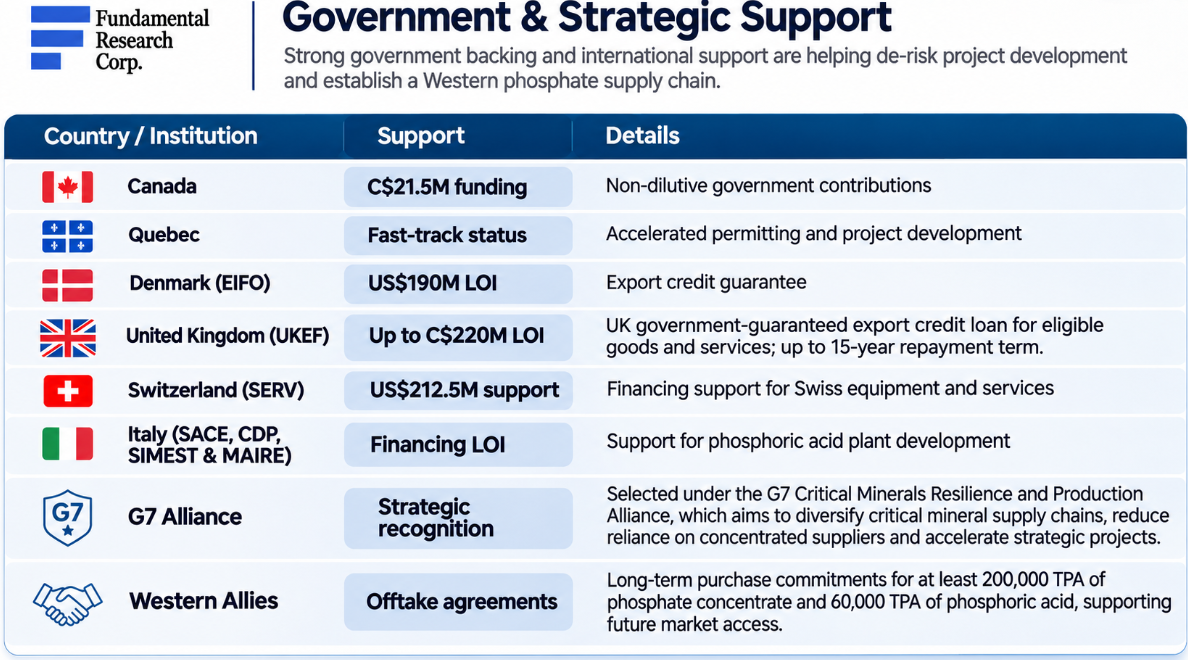
Government & Strategic Support
| Country / Institution | Support | Details |
|---|---|---|
| Canada | C$21.5M funding | Non-dilutive government contributions |
| Quebec | Fast-track status | Accelerated permitting and project development |
| Denmark (EIFO) | US$190M LOI | Export credit guarantee |
| United Kingdom (UKEF) | Up to C$220M LOI | UK government-guaranteed export credit loan for eligible goods and services; up to 15-year repayment term. |
| Switzerland (SERV) | US$212.5M support | Financing support for Swiss equipment and services |
| Italy (SACE, CDP, SIMEST & MAIRE) | Financing LOI | Support for phosphoric acid plant development |
| G7 Alliance | Strategic recognition | Selected under the G7 Critical Minerals Resilience and Production Alliance, which aims to diversify critical mineral supply chains, reduce reliance on concentrated suppliers and accelerate strategic projects. |
| Western Allies | Offtake agreements | Long-term purchase commitments for at least 200,000 TPA of phosphate concentrate and 60,000 TPA of phosphoric acid, supporting future market access. |
We note that European interest reflects efforts to secure alternative phosphate supplies and diversify battery supply chains, while creating opportunities for European companies to supply equipment, technology, and engineering services to PHOS.
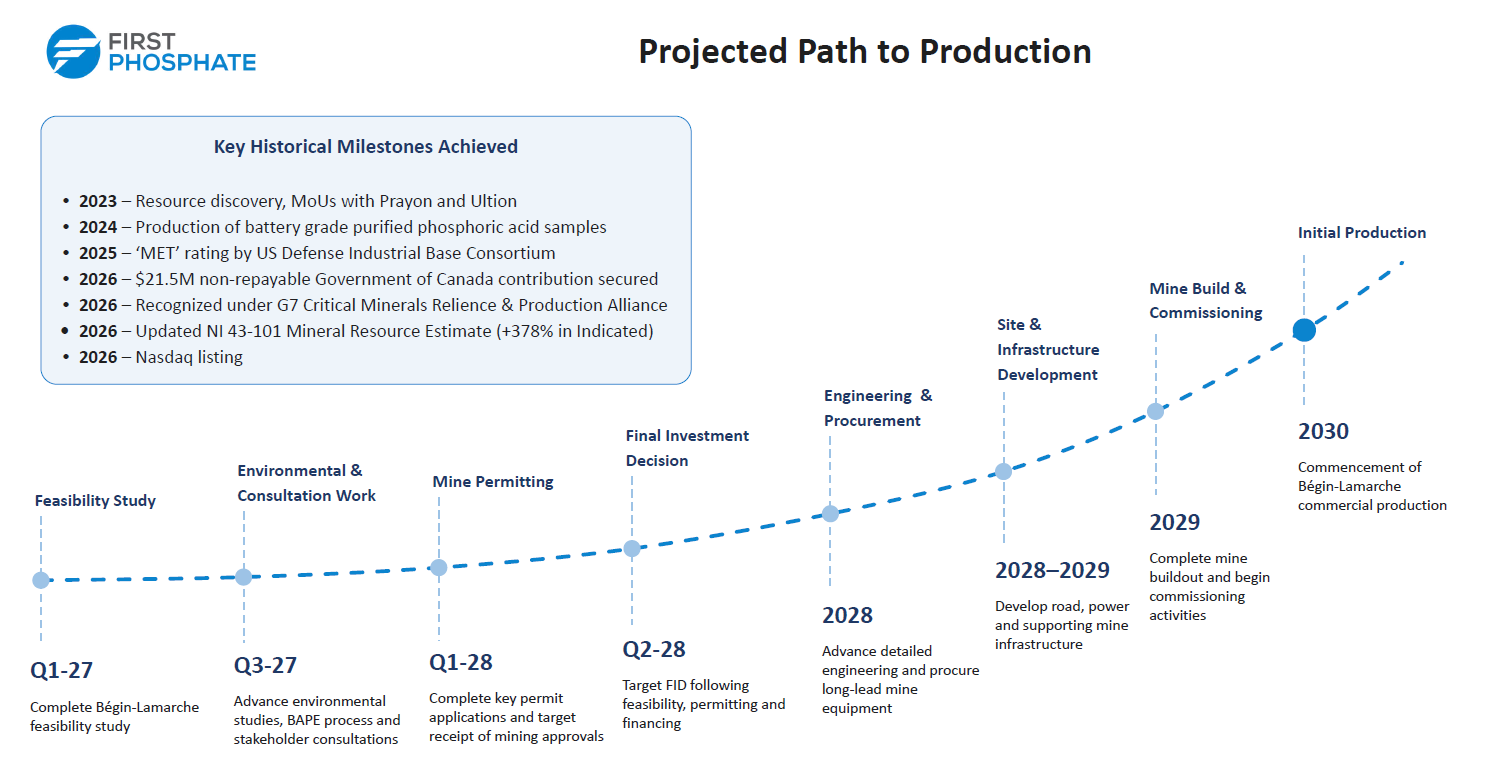
PHOS is completing a feasibility study based on a significantly larger resource base than the 2024 PEA, potentially supporting a longer mine life, and improved project economics, with potential production start in 2030.
PHOS has a strong balance sheet with sufficient cash to fund development over the next 12 months, implying limited need for near-term share dilution.
| Key Financial Data (FYE - Feb 28) | 2027 (6M) | Current (FRC Est.) |
|---|---|---|
| Cash | $19,949,271 | ~$17,800,000 |
| Working Capital | $22,668,760 | |
| Current Ratio | 6.5 | |
| Monthly Burn Rate (incl. G&A) | -$1,050,231 | |
| Cash from Financing Activities & Grants | $23,075,538 | |
| Property Related Expenses | -$13,571,989 |
In-the-money warrants and options could provide an additional $6.5M in funding.
| Options | # | Exercise Price | Amount |
|---|---|---|---|
| Total | 7,650,000 | $0.79 | $6,064,000 |
| In-the-Money | 7,350,000 | $0.74 | $5,464,000 |
| Warrants | # | Exercise Price | Amount |
|---|---|---|---|
| Total | 4,551,475 | $1.29 | $5,866,188 |
| In-the-Money | 2,625,000 | $0.40 | $1,050,000 |
Given the progress since our last report, including rising international support, government funding, and the Nasdaq uplisting, we have reduced our discount rate assumption from 13.0% to 11.6%, in line with the rate we typically apply to advanced-stage development projects in relatively safe jurisdictions.
| DCF Valuation | |
|---|---|
| Operating Life (years) | 25 |
| Annual Produciton - PPA - Mt | 330,000 |
| Product Price (US$/t) | $2,250 |
| OPEX (US$/t) | $1,450 |
| Exchange rate (US$:C$) | 1.43 |
| Initial CAPEX (US$B) | $1.0 |
| Discount Rate | 11.6% |
| After-Tax Net Asset Value (C$) | $688,440,310 |
| Working Capital - Debt (C$) | $17,062,500 |
| Fair Value of PHOS (C$) | $705,502,810 |
| No. of Shares * | 195,459,816 |
| Fair Value per Share (C$) | $3.61 |
As a result, our valuation increased materially from $3.16 to $3.61/share.
| Fair Value (C$) | Product Price (US$/t) | |||||
|---|---|---|---|---|---|---|
| $2,000 | $2,250 | $2,500 | $2,750 | $3,000 | ||
| Exchange Rate (US$:C$) | $1.20 | $0.50 | $3.04 | $5.59 | $8.14 | $10.68 |
| $1.30 | $0.53 | $3.29 | $6.05 | $8.81 | $11.56 | |
| $1.43 | $0.58 | $3.61 | $6.64 | $9.68 | $12.71 | |
| $1.40 | $0.56 | $3.54 | $6.51 | $9.48 | $12.45 | |
| $1.45 | $0.58 | $3.66 | $6.74 | $9.81 | $12.89 | |
| Fair Value (C$) | Product Price (US$/t) | |||||
|---|---|---|---|---|---|---|
| $2,000 | $2,250 | $2,500 | $2,750 | $3,000 | ||
| Discount Rate | 5.0% | $5.53 | $11.63 | $17.73 | $23.83 | $29.93 |
| 10.0% | $1.33 | $4.87 | $8.40 | $11.94 | $15.48 | |
| 11.6% | $0.58 | $3.61 | $6.64 | $9.68 | $12.71 | |
| 15.0% | -$0.47 | $1.81 | $4.09 | $6.37 | $8.65 | |
| 20.0% | -$1.27 | $0.32 | $1.91 | $3.49 | $5.08 | |
We reiterate our BUY rating, and raise our fair value estimate from $3.16 to $3.61/share, reflecting the company's continued progress in advancing its integrated LFP supply chain, strong government and institutional support, and improving market positioning. Rising Western efforts to diversify critical mineral supply chains, and reduce dependence on China, provide a strong structural tailwind for PHOS.
We are maintaining a risk rating of 5 (Highly Speculative). We believe the company is exposed to the following key risks (not exhaustive):
Sid Rajeev, B.Tech, MBA, CFA — Head of Research, Fundamental Research Corp.
Nina Rose Coderis, B.Sc (Geology) — Equity Analyst, Fundamental Research Corp.
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Buy – Fair value is 12% above the current market price; or risk and reward is favorable
Hold – Fair value is between 5% to 12% above the current market price
Sell – Fair value is 5% above, or less, than the current market value; or risk and reward is unfavorable
Suspended or Rating N/A— Coverage and ratings suspended until more information can be obtained from the company regarding recent events.
1 (Low Risk) - The company operates in an industry where it has a strong position (for example a monopoly, high market share etc.) or operates in a regulated industry. The future outlook is stable or positive for the industry. The company generates positive free cash flow and has a history of profitability. The capital structure is conservative with little or no debt.
2 (Below Average Risk) - The company operates in an industry where the fundamentals and outlook are positive. The industry and company are relatively less sensitive to systematic risk than companies with a Risk Rating of 3. The company has a history of profitability and has demonstrated its ability to generate positive free cash flows (though current free cash flow may be negative due to capital investment). The company’s capital structure is conservative with little to modest use of debt.
3 (Average Risk) - The company operates in an industry that has average sensitivity to systematic risk. The industry may be cyclical. Profits and cash flow are sensitive to economic factors although the company has demonstrated its ability to generate positive earnings and cash flow. Debt use is in line with industry averages, and coverage ratios are sufficient.
4 (Speculative) - The company has little or no history of generating earnings or cash flow. Debt use is higher. These companies may be in start-up mode or in a turnaround situation. These companies should be considered speculative.
5 (Highly Speculative) - The company has no history of generating earnings or cash flow. They may operate in a new industry with new, and unproven products. Products may be at the development stage, testing, or seeking regulatory approval. These companies may run into liquidity issues and may rely on external funding. These stocks are considered highly speculative.
Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE.
Analyst Certification: The views expressed in this report accurately reflect the personal views of the analyst, and no part of their compensation was, is, or will be directly or indirectly related to the specific recommendation or views expressed.
Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The analyst and Fundamental Research Corp. “FRC” do not own any shares of the subject company. FRC owns warrants of the subject company, but does not make a market or offer shares for sale of the subject company, and does not have any investment banking business with the subject company. Fees ranging between $25,000 and $35,000 have been paid to FRC by First Phosphate to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. FRC takes steps to mitigate conflicts including setting fees in advance and utilizing analysts who must abide by CFA Institute Code of Ethics and Standards of Professional Conduct. Additionally, analysts may not trade in any security under coverage. Our full editorial control of all research, timing of release of the reports, and release of liability for negative reports are protected contractually. The issuer has agreed to a minimum coverage term and coverage cannot be unilaterally terminated. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time.
The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (28%).
This report contains "forward looking" statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company's products/services in the marketplace; acceptance in the marketplace of the Company's new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company's periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. A report initiating coverage will most often be updated quarterly while a report issuing a rating may have no further or less frequent updates because the subject company is likely to be in earlier stages where nothing material may occur quarter to quarter.
Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.