
We are initiating coverage on AZS with a BUY rating, and a fair value estimate of $2.34/share, supported by Philadelphia’s multi million ounce potential, potential district-scale mineralization, and a strategic investment by Evolution Mining. AZS trades at an 85% discount to our peer group average, offering significant upside potential as exploration progresses. A strong balance sheet provides funding to advance exploration, while reducing the risk of near-term dilution.
The Hidden Value the Market Has Yet to Discover
Paused · 20:08 left · FRC · read by an AI voice
Disclosure: Arizona Gold & Silver Inc. has paid FRC a fee for research coverage and distribution of reports. This fee creates a potential conflict of interest which readers should consider. See last page for other important disclosures, rating, and risk definitions.
All figures are in CS$.
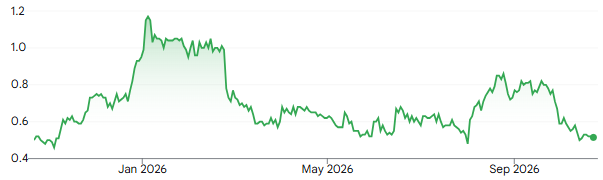
Price and Volume (1-year)
| YTD | 12M | |
|---|---|---|
| AZS | -50% | -1% |
| TSXV | -17% | -13% |
| Gold | -7% | 0% |
| GOEX* | -7% | 11% |
| Key Financial Data (FYE - Aug 31) (C$) |
2026 (9M) | Current Cash |
|---|---|---|
| Cash | $4,957,698 | ~$12,500,000 |
| Working Capital | $5,282,069 | |
| Mineral Assets/PP&E | $12,506,547 | |
| Total Assets | $18,438,545 | |
| Net Income (Loss) | -$1,846,993 | |
| EPS | -$0.02 |
Diversified commodity exposure: Gold, silver, and antimony (critical mineral).
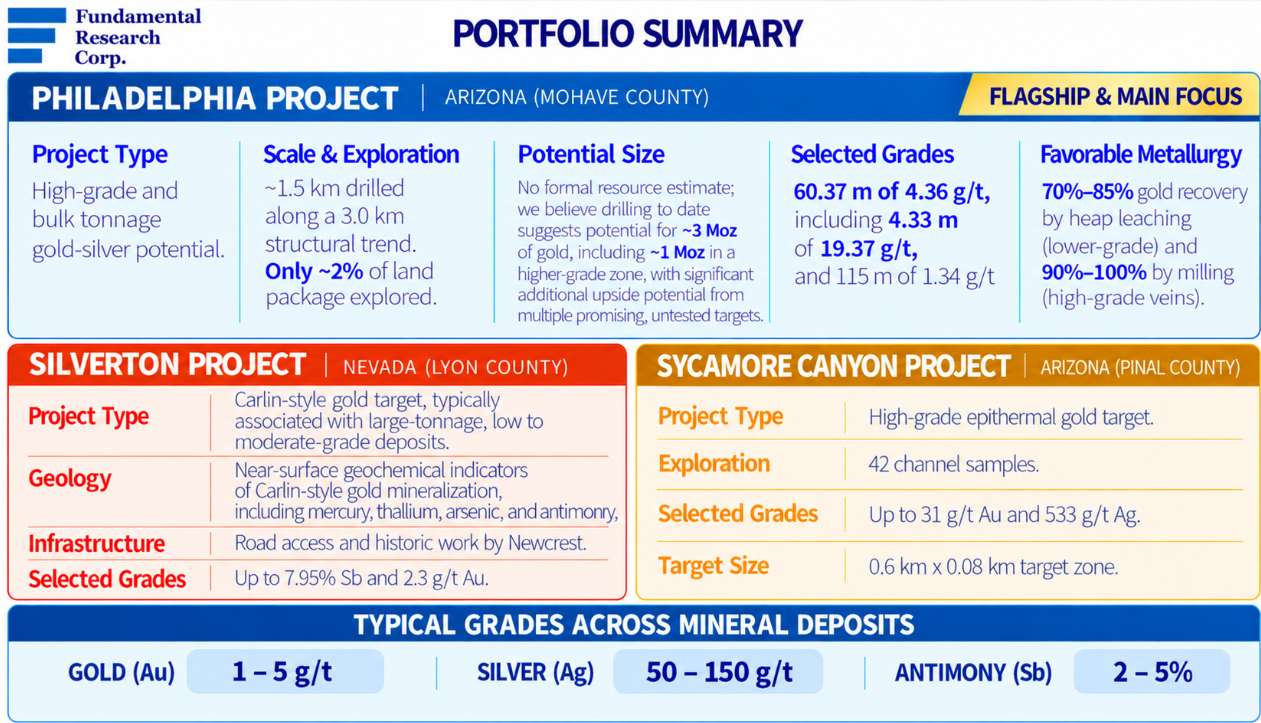
Tier-1 Mining Jurisdictions: Nevada and Arizona rank among the top jurisdictions for mining investment globally, with both placing in the top 10 in the Fraser Institute’s 2025 survey.
Project Locations Map
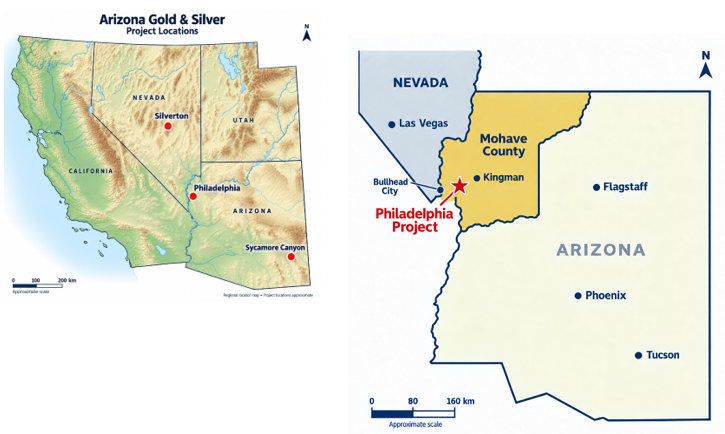
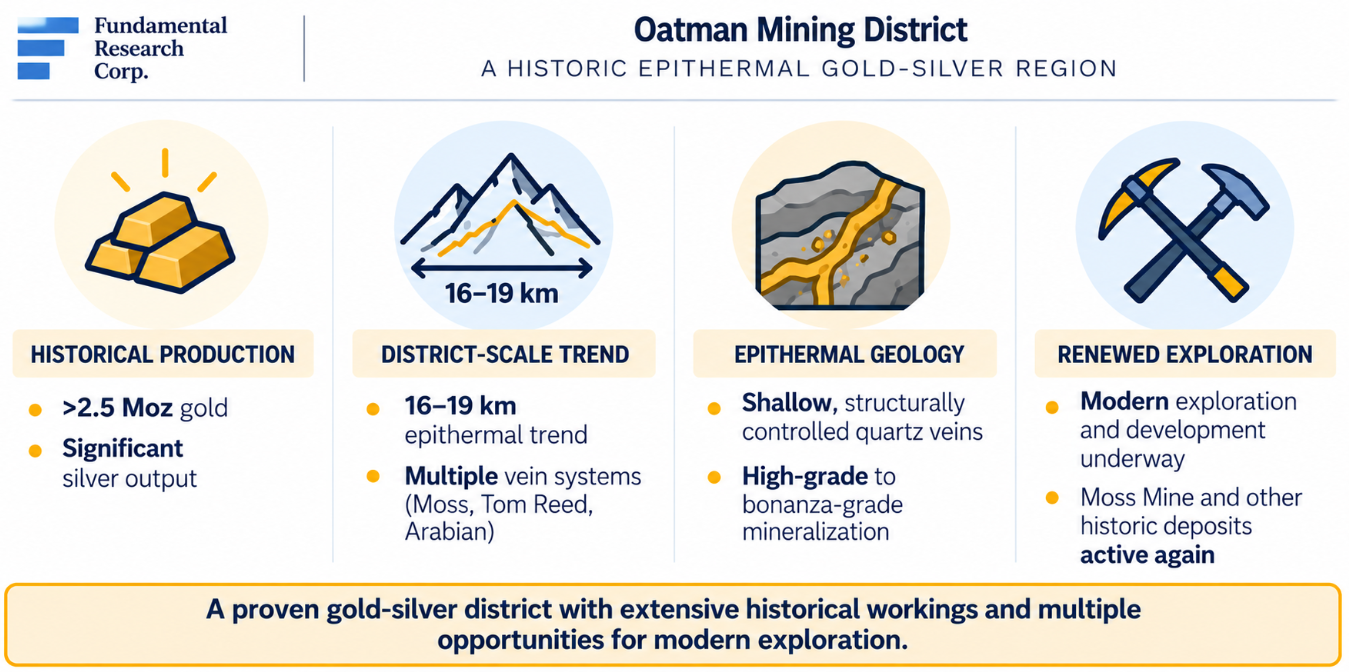
The 4,300-acre project is located in Mohave county, northwestern Arizona, within the Oatman Mining District, a historically productive region known for shallow, high-grade epithermal gold-silver mineralization. Generally, shallow deposits support lower initial CAPEX, while high grades support robust margins.
AZS gained control of the project in 2019. Large Land Package: 4,300 acres in a proven Arizona gold-silver district, with significant exploration upside. High-Grade Potential: Shallow gold-silver system, with bonanza-grade mineralization, identified across multiple targets.
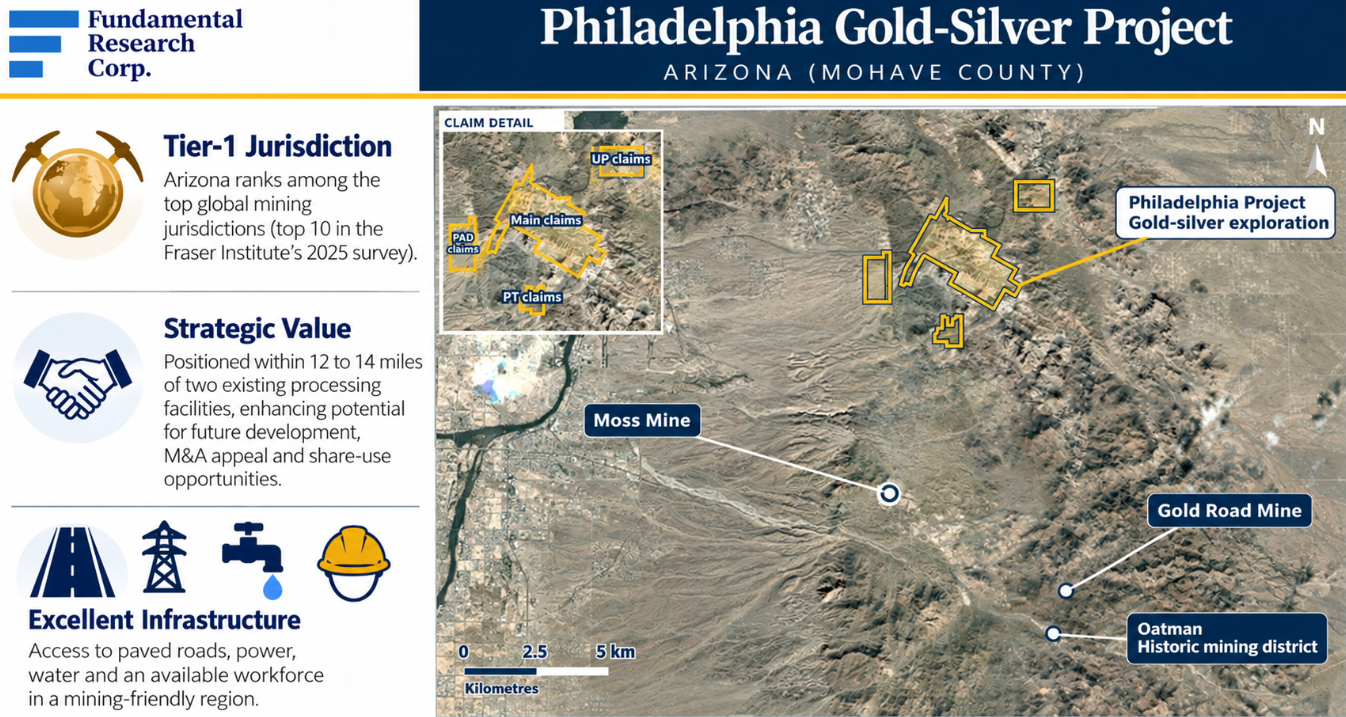
Strategic Potential: A historic gold-silver district with significant potential for renewed exploration.
The Oatman Mining District hosts two active gold mines: Mako Mining’s (MCAP: $1.1B) open-pit Moss mine, Gold Road International’s (OB:GOLDR / MCAP: $60M) underground Gold Road mine. The presence of active mining operations underscores established infrastructure, and strategic development potential.
| Oatman Mining District KEY NEARBY GOLD MINES |
||
|---|---|---|
| Mine | Moss Mine (Arizona, USA) |
Gold Road Mine (Arizona, USA) |
| Owner | Mako Mining Corp. | Gold Road International PLC |
| Mining Method | Open Pit | Underground |
| First Production | 2018 | 1900, modern restart 2025 |
| Current / Target Annual Production (gold) | ~31,000 oz Au | 8,000 – 10,000 oz Au |
| Cash Cost (US$/oz Au) | ~US$2,204/oz Au | N/A |
| Measured + Indicated Resource | 646 koz Au @ 0.35 g/t | N/A |
| Inferred Resource | 122 koz Au @ 0.31 g/t | 214 koz Au @ 6.83 g/t |
| Total Resource (M&I + Inferred) | 768 koz Au @ ~0.35 g/t | 214 koz Au @ 6.83 g/t |
| Average Grade (Total Resource) | ~0.35 g/t Au | 6.83 g/t Au |
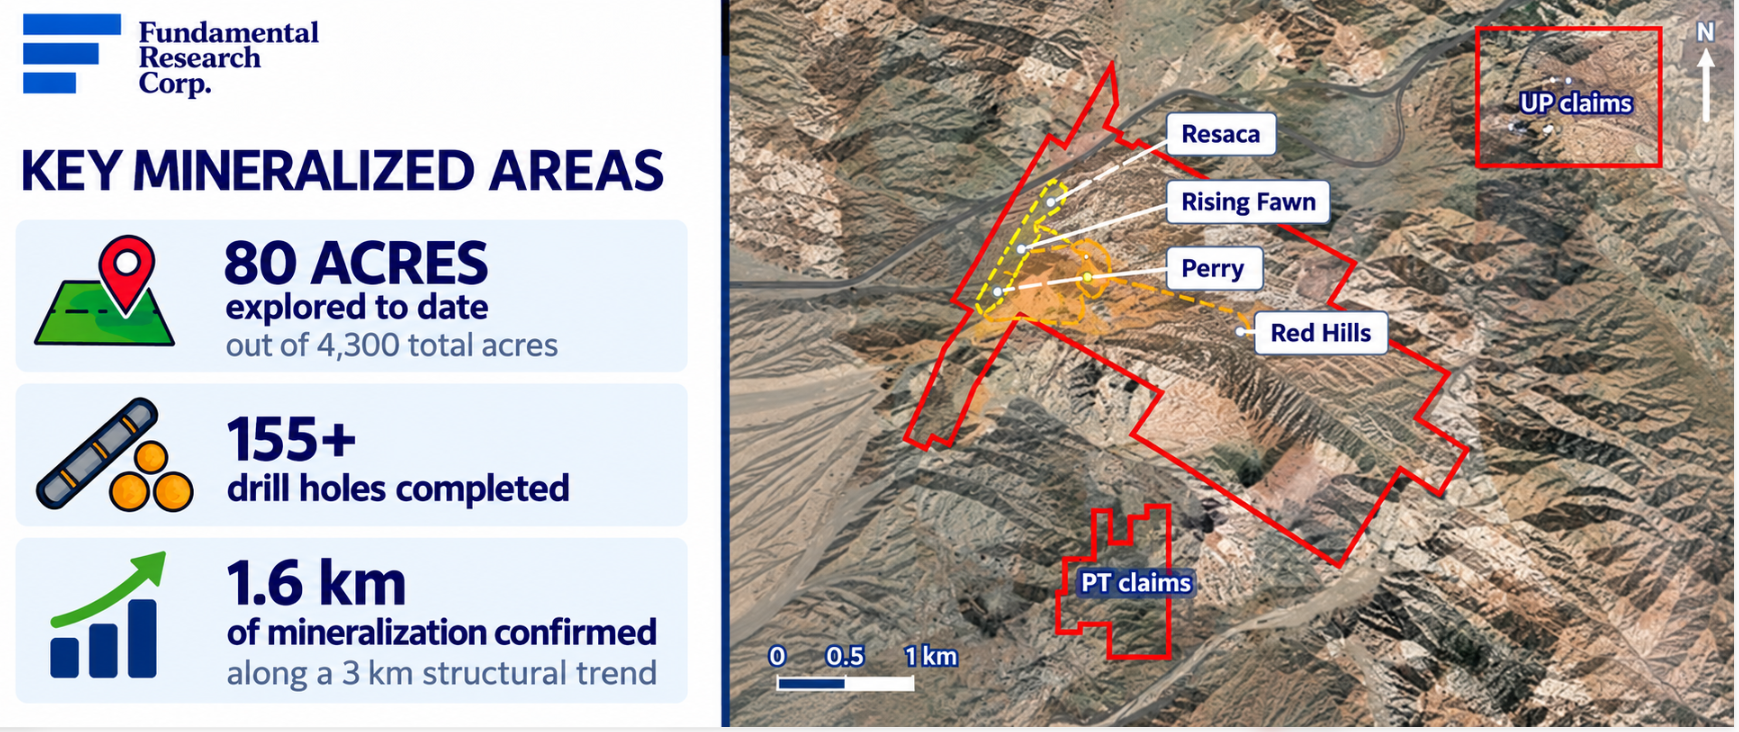
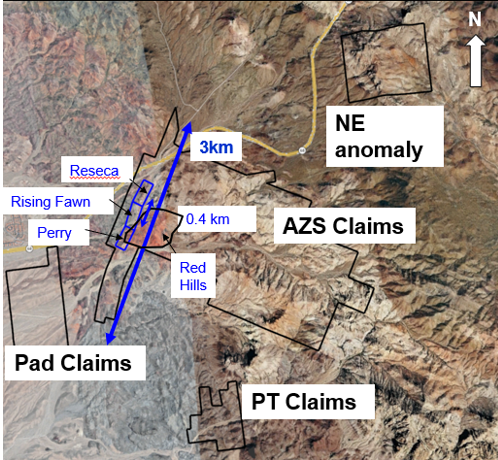
Drilling has confirmed gold mineralization along the Arabian Fault, a major regional structure, extending along a ~3-km trend with four key targets: Perry, Red Hills, Rising Fawn, and Resaca.
Only 2% of the 4,300-acre project has been explored to date (80 acres). ~1.6 km have been drilled along a 3.0 km structural trend. Mineralization remains open in multiple directions.
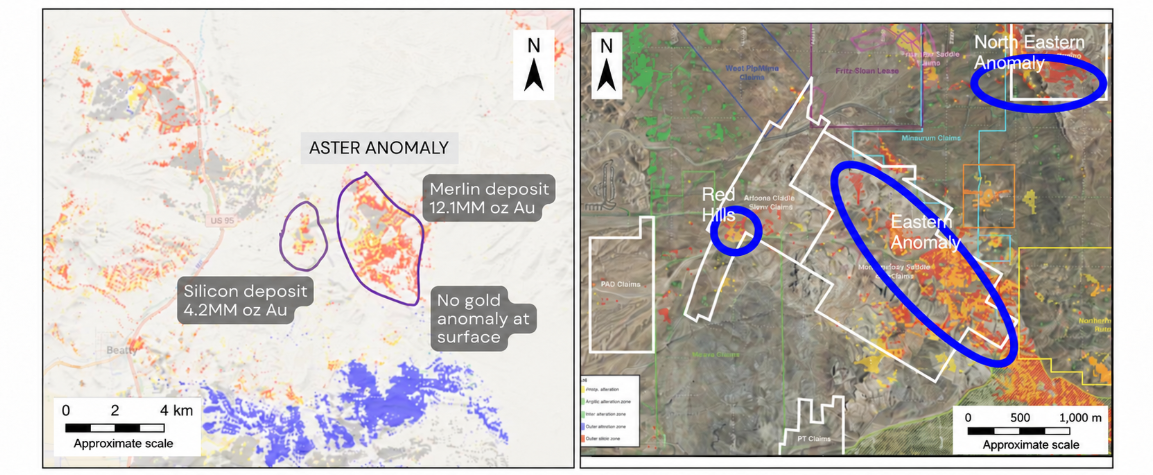
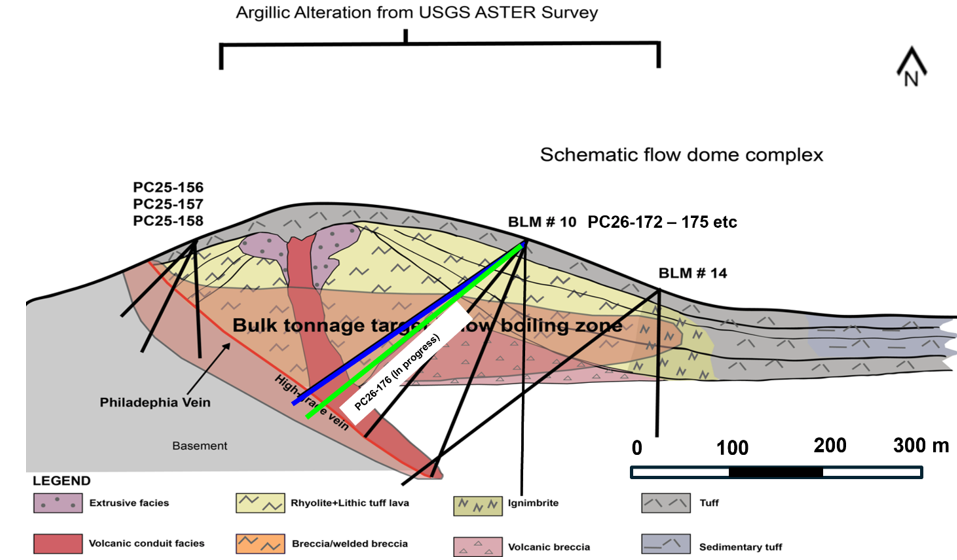
Historically, exploration focused on narrow, high-grade gold-silver veins at Perry and Rising Fawn. AZS has since expanded the opportunity by identifying potential for larger, bulk-tonnage mineralization, supported by U.S. Geological Survey (USGS) satellite data identifying a large anomaly similar to that associated with AngloGold Ashanti’s Arthur gold project in Nevada, which comprises the Silicon and Merlin gold deposits, and hosts over 16 Moz of gold.
A key feature of Philadelphia is its dual-style mineralization, combining high-grade veins, with broader bulk-tonnage mineralization, similar to AngloGold Ashanti’s multi-million-ounce Arthur gold project in Nevada, which comprises the Silicon and Merlin gold deposits.
Similar Geophysical Signature: Merlin/Silicon Deposits vs Philadelphia
Since 1981, the property has undergone mapping, geochemical and geophysical surveys, and drilling by several operators. AZS began drilling in 2019.
Extensive Drilling History: 83,967 ft drilled across 197 holes since 1981.
| Year | Drill Holes | Feet |
|---|---|---|
| 1981 | 1 | 72 |
| 1982 | 12 | 3,498 |
| 1983 | 10 | 2,663 |
| 1993 | 4 | 1,149 |
| 1994 | 3 | 769 |
| 2019 | 11 | 1,691 |
| 2020 | 41 | 11,831 |
| 2021 | 34 | 9,878 |
| 2022 | 11 | 5,810 |
| 2023 | 14 | 6,675 |
| 2024 | 14 | 8,320 |
| 2025 | 25 | 13,007 |
| 2026 (Drilling Ongoing) (red) | 17 | 18,613 |
| Total | 197 | 83,967 |
Drilling from 2021–2026 has intersected both high-grade gold, and broad mineralized intervals, across multiple areas, suggesting a potentially large, multi-zone gold system. High-Grade Gold Intercepts: Multiple holes intersected significant gold grades, including 4.0 m at 10.8 g/t Au, and 1.5 m at 18.2 g/t Au. Strong Results Across Multiple Areas: Drilling at Perry, Rising Fawn, and Red Hills has returned promising gold intercepts. Broad Mineralized Intervals: Several holes intersected wide mineralized intervals, including 90.7 m at 1.5 g/t Au, and 70.4 m at 1.2 g/t Au.
2021-2026 Drill Highlights
| DrillHole # | Area | Thickness (m) | Au (g/t) |
|---|---|---|---|
| PRC21-78 | Perry | 42.2 | 0.1 |
| including | 1.3 | 9.8 | |
| PRC21-79 | Perry | 10.8 | 1.8 |
| including | 5.5 | 7.8 | |
| PRC21-80 | Perry | 69.4 | 1.6 |
| including | 4.0 | 6.9 | |
| PRC21-81 | Rising Fawn | 38.1 | 0.5 |
| including | 1.5 | 3.8 | |
| PC22-86 | Rising Fawn | 45.0 | 1.3 |
| including | 4.0 | 10.8 | |
| PC22-87 | Rising Fawn | 31.5 | 1.0 |
| including | 3.0 | 6.0 | |
| PC22-88 | Rising Fawn | 24.3 | 1.1 |
| including | 1.0 | 8.7 | |
| PC22-89 | Rising Fawn | 18.9 | 1.0 |
| including | 0.9 | 11.2 | |
| PC22-90 | Perry | 27.9 | 2.4 |
| including | 7.2 | 7.5 | |
| PC22-91 | Perry | 47.0 | 1.0 |
| including | 1.4 | 6.7 | |
| PC22-95 | Rising Fawn | 37.0 | 0.8 |
| including | 4.1 | 3.8 | |
| PC22-96 | Rising Fawn | 32.9 | 0.7 |
| including | 11.2 | 1.0 | |
| PRC23-97 | Rising Fawn | 50.0 | 2.9 |
| including | 1.5 | 18.2 | |
| PRC23-107 | Perry | 18.6 | 1.4 |
| including | 5.3 | 5.6 | |
| PRC23-108 | Perry | 35.0 | 0.5 |
| including | 1.2 | 4.6 | |
| PC23-111 | Rising Fawn | 51.1 | 0.7 |
| including | 1.6 | 6.2 | |
| PC25-136 | Rising Fawn | 4.9 | 9.2 |
| including | 41.9 | 1.6 |
| DrillHole # | Area | Thickness (m) | Au (g/t) |
|---|---|---|---|
| PC25-137 | Rising Fawn | 22.0 | 0.8 |
| PC25-138 | Rising Fawn | 20.3 | 0.5 |
| PC25-139 | Rising Fawn | 18.0 | 0.5 |
| PC25-148 | Rising Fawn | 15.3 | 0.4 |
| PC25-149 | Rising Fawn | 13.4 | 0.3 |
| PC25-150 | Rising Fawn | 15.2 | 0.5 |
| PC25-151 | Rising Fawn | 17.5 | 1.2 |
| PC25-152 | Rising Fawn | 16.0 | 0.4 |
| including | 5.2 | 7.1 | |
| PC25-153 | Rising Fawn | 12.2 | 0.7 |
| PC25-133 | Red Hills | 22.8 | 0.3 |
| including | 3.9 | 0.4 | |
| PC25-135 | Red Hills | 64.2 | 0.4 |
| PC25-156 | Perry | 20.4 | 9.0 |
| PC25-157 | Perry | 48.2 | 2.4 |
| PC25-158 | Perry | 60.4 | 4.4 |
| including | 4.3 | 19.4 | |
| PC26-162 | Perry | 28.3 | 2.8 |
| including | 3.4 | 15.1 | |
| PC26-163 | Perry | 23.4 | 1.7 |
| including | 2.7 | 6.7 | |
| PC26-164 | Perry | 60.0 | 1.3 |
| including | 7.4 | 4.4 | |
| PC26-168 | Perry | 30.9 | 2.0 |
| including | 15.2 | 2.9 | |
| PC26-170 | Perry | 59.2 | 1.0 |
| including | 21.5 | 2.1 | |
| PC26-171B | Perry | 90.7 | 1.5 |
| including | 33.3 | 3.0 | |
| PC26-173 | Perry | 43.6 | 1.5 |
| including | 21.9 | 2.5 | |
| PC26-172 | Perry | 70.4 | 1.2 |
| including | 2.9 | 4.9 |
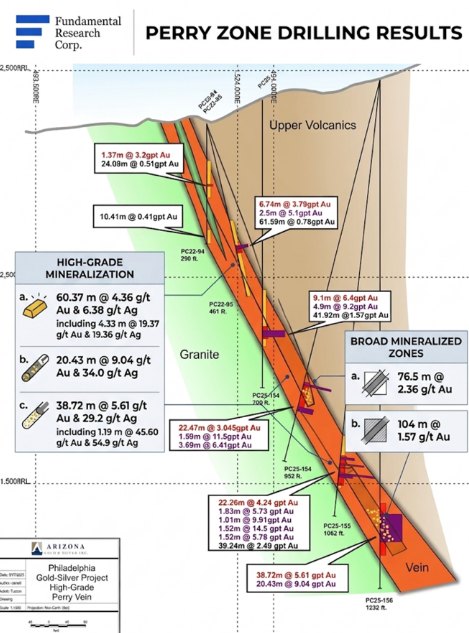
Historical Focus: Exploration has primarily targeted the Perry zone, one of four targets, delineating mineralization over 1 km along the 3 km structural trend, to depths of ~300 m. High-Grade Vein Potential: Standout results include 9.04 g/t Au over 20.43 m, from 320.73 m depth; for context, gold mines commonly average grades of 1–5 g/t.
Key Targets
Bulk-Tonnage Potential: Intercepts include 104 m at 1.57 g/t gold, and 76.5 m at 2.36 g/t, highlighting the potential for a large-scale mineralized system, and a potentially long mine life. Current Strategy: Expand high-grade mineralization at Perry, and test deeper mineralization at Red Hills.
Key Takeaways:
Higher grades at depth: Drilling indicates the Perry zone thickens, and grades increase, with depth (e.g., hole 156: 20 m at 9 g/t gold from 320 m depth), implying potential for further resource expansion at depth.
Perry Zone Geological Model and Mineralization Targets
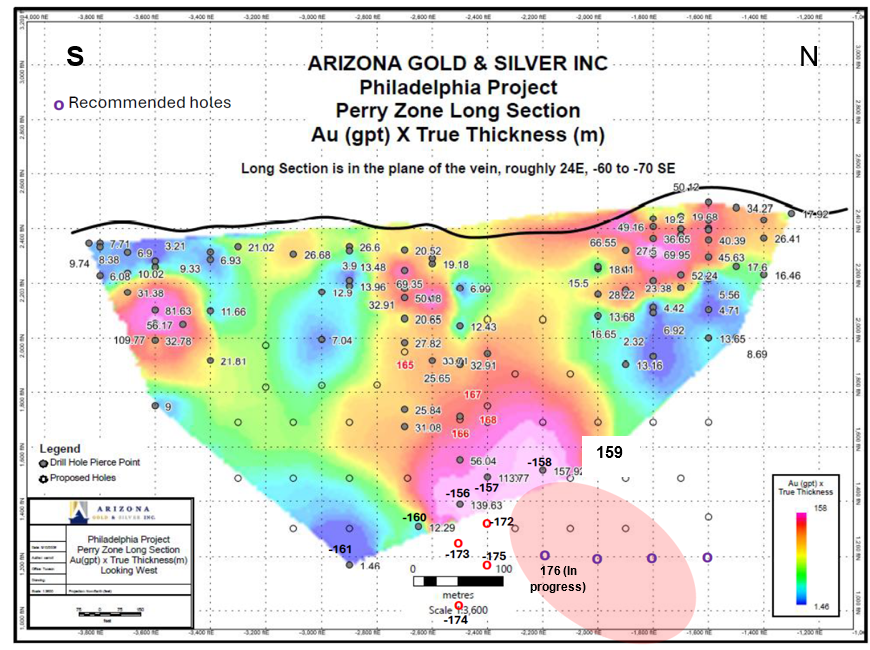
Northward Extension: Higher-grade mineralization appears to continue northward at depth, opening up additional opportunities to expand the Perry zone. Upcoming drilling: Four to five additional holes are planned in the pink zone (shown in the image) before year-end. Positive results could expand the Perry zone at depth and to the north.
We believe drilling along 1 km of the 3 km trend has identified potential for a bulk-tonnage target containing ~3 Moz of gold, within which a higher-grade zone could host ~1 Moz. This supports Philadelphia’s potential as a large-scale project, with the higher-grade zone potentially supporting standalone development.
Philadelphia hosts a potential ~3 Moz gold system, including a ~1 Moz higher-grade opportunity.
Exploration Targets
| Bulk Tonnage Target | High-Grade Target | |
|---|---|---|
| Length (m) | 1,000 | 1,000 |
| Width (m) | 450 | 450 |
| Depth (m) | 60 | 3 |
| Estimated Gross Tonnage | 70,200,000 | 3,510,000 |
| Grades (gpt) | 1.50 | 9.00 |
| Estimated Contained Gold (oz) | 3,369,600 | 1,010,880 |
Using AngloGold Ashanti’s 16 Moz Arthur gold project as a comparison suggests that Philadelphia’s 3 km mineralized trend may represent only the beginning of a much larger mineralized system.
Silicon Deposit Geologic Model
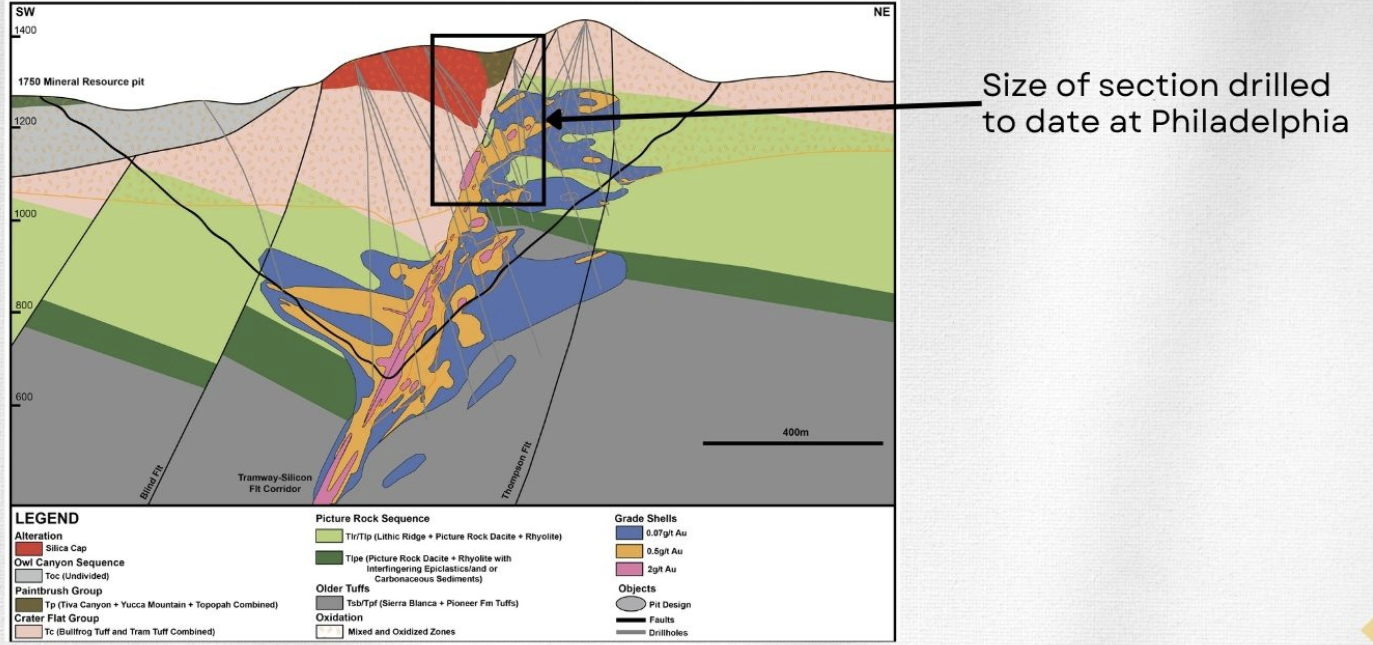
In our view, the project has significant exploration upside, with geophysics pointing to mineralized areas beyond those already drilled.
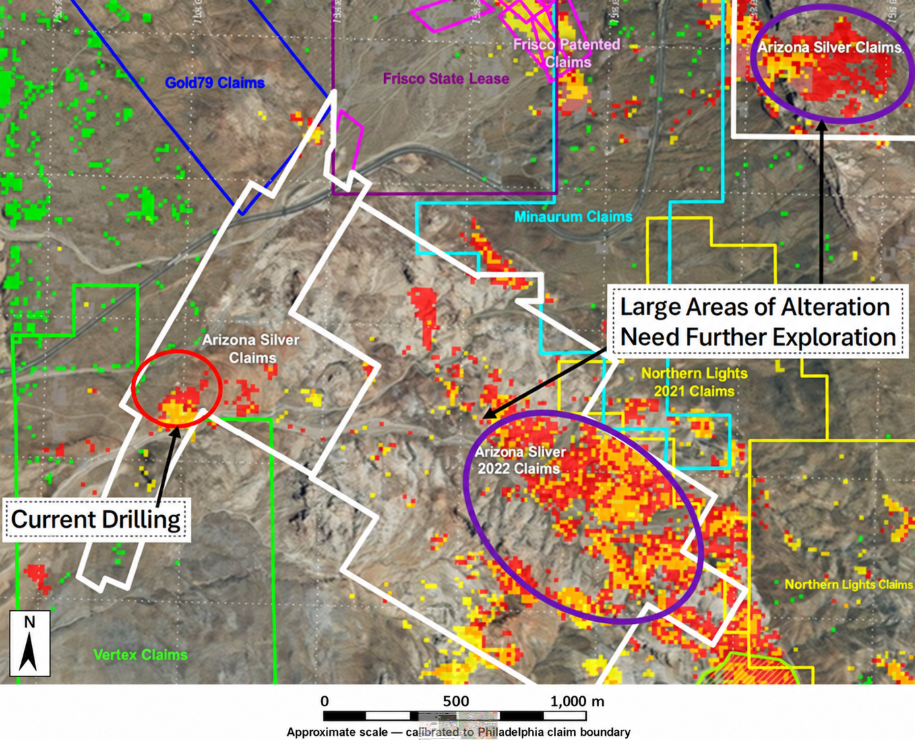
Only ~2% of the land package has been explored to date, highlighting significant potential for further discoveries. Three additional targets, Red Hills, Eastern Anomaly and Northeastern Anomaly, remain untested, offering further exploration potential beyond the Perry zone. The southern Arabian Fault extension is drill-ready, with permits in place. Next, additional permit applications and environmental surveys are planned for next month.
Additional Prospects
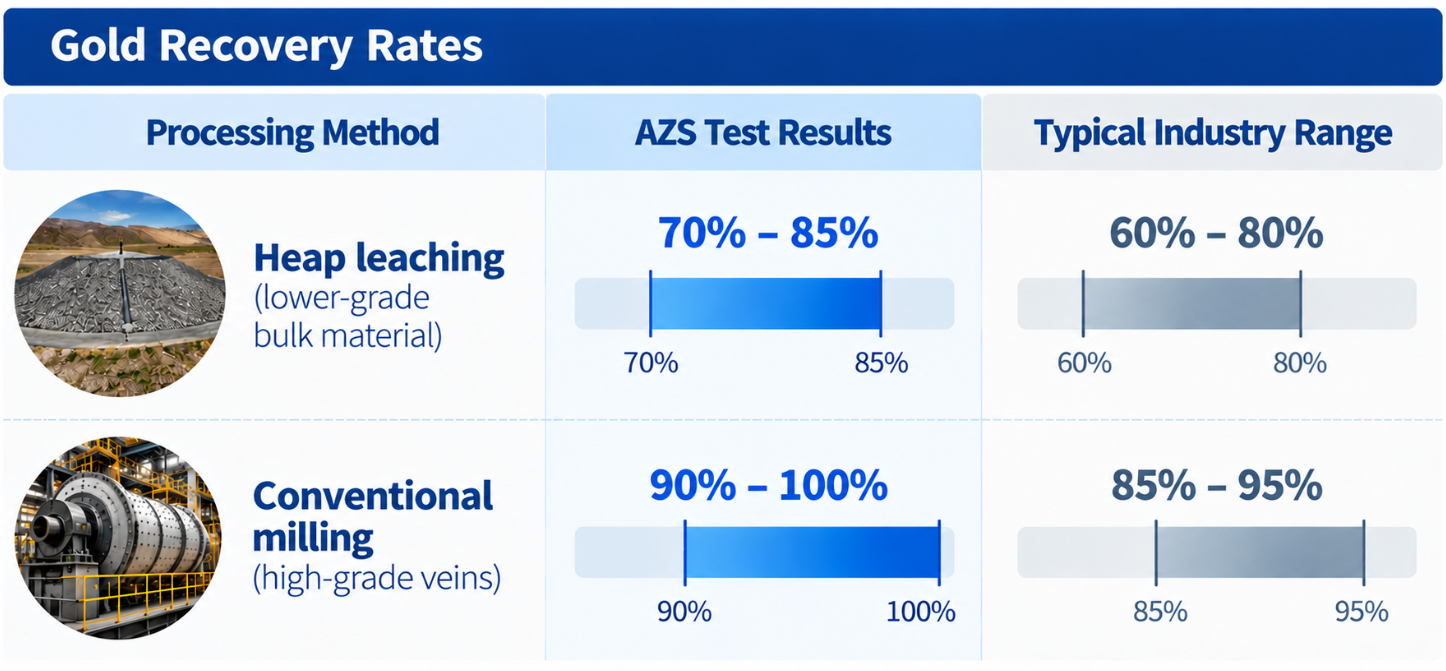
Recovery rates are critical to project economics. Test results show strong gold recovery potential from both lower-grade bulk material and high-grade veins.
Philadelphia has high gold recovery potential.
Management plans to test key targets before publishing a maiden resource (~two years), a strategy we believe could help avoid understating the project’s scale. Without a formal resource estimate, we believe the market has yet to fully recognize Philadelphia’s potential. Our speculative estimates, presented above, provide an initial framework for assessing its scale.
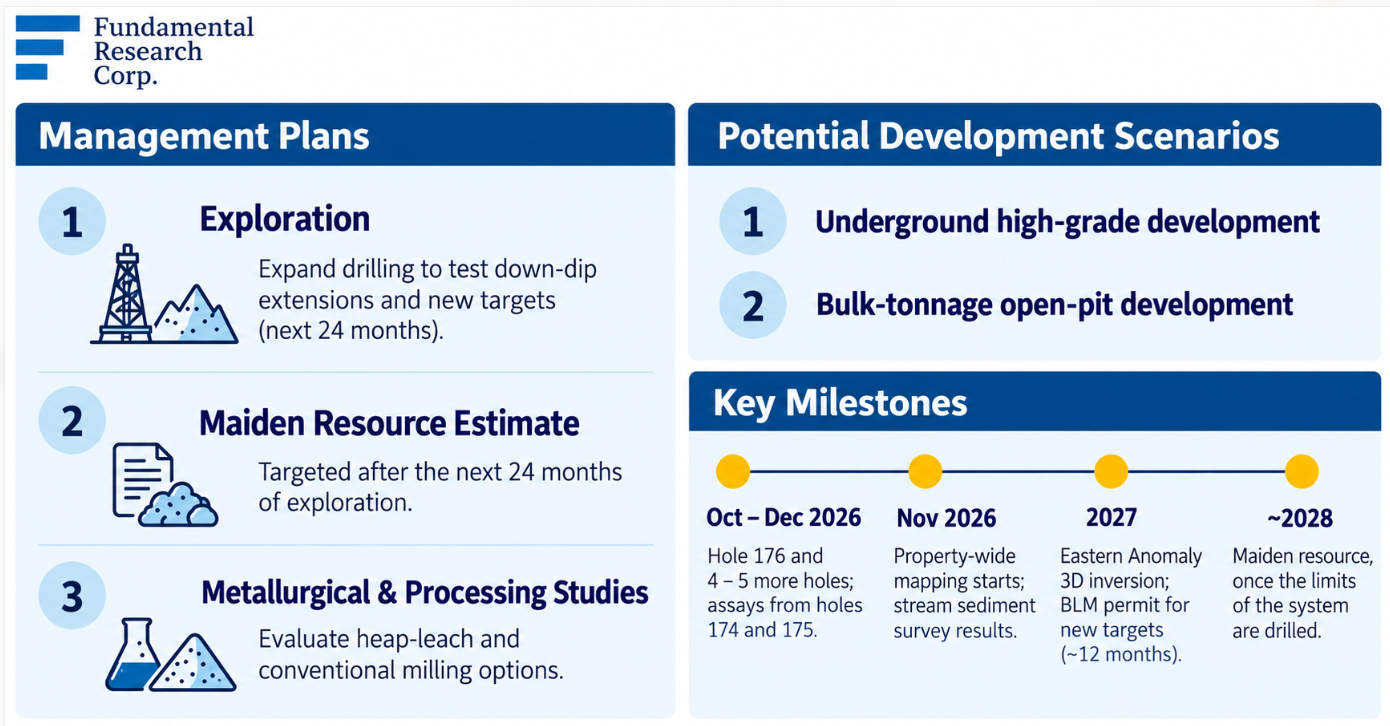
Strategic Resource Definition: Management plans to complete a maiden resource estimate only after fully testing key exploration targets, a process that could take ~two more years. We believe this is a prudent strategy, as an earlier estimate could understate the project’s overall scale, and exploration potential.
Comparable Success Story — Great Bear Resources: Great Bear spent several years drilling its Dixie project in Ontario, expanding its understanding of the deposit before being acquired by Kinross Gold for ~$1.8B. Kinross subsequently published the project’s maiden resource estimate, reporting ~5 Moz of gold. Great Bear provides an example of a company pursuing an exploration-first strategy, attracting a major acquisition before publishing its maiden resource.
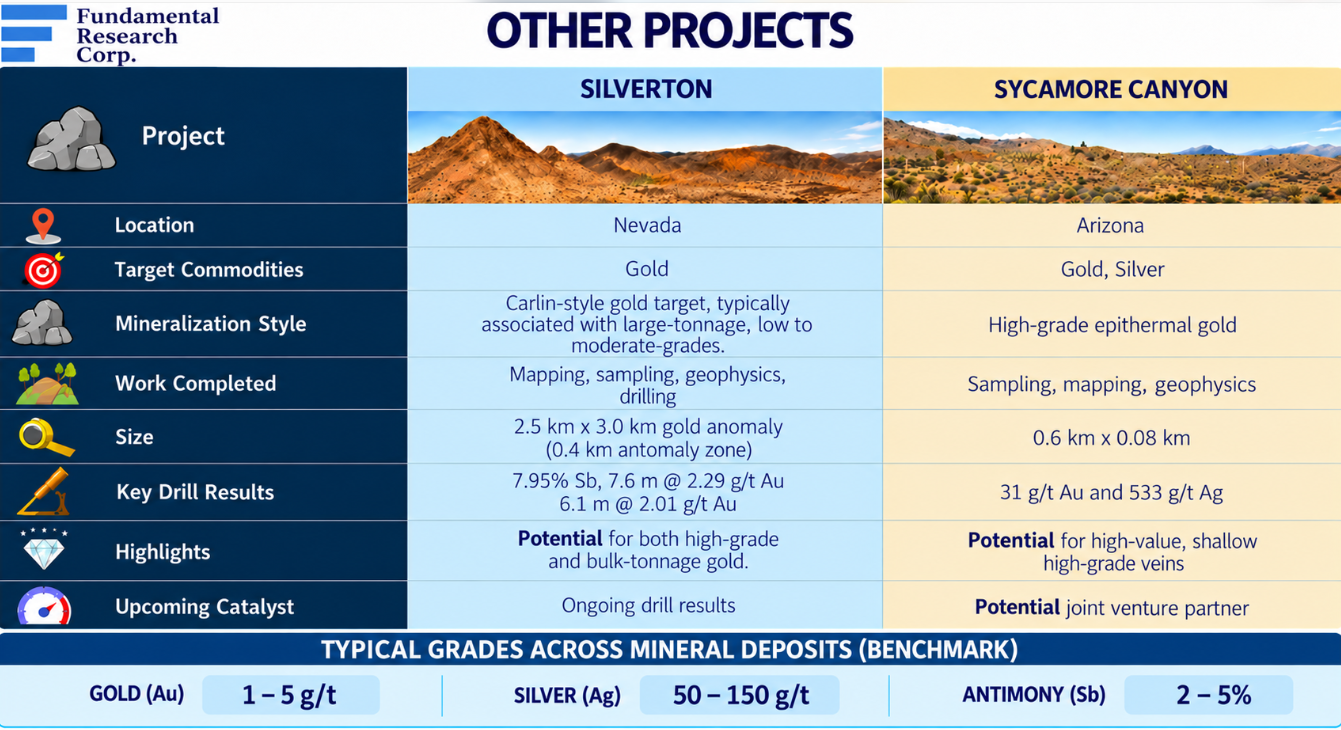
As Philadelphia is currently the main focus, the company plans to advance its other two projects through joint venture (JV) partnerships, sharing exploration risk.
Management and board own 7.5% of the company’s equity. Similarly, Evolution Mining and other major investors collectively own 33.2%. Four out of five directors are independent.
Share Ownership
| Management/Directors | Shares | % of Total |
|---|---|---|
| Mike Stark - President, CEO & Director | 4,395,043 | 2.88% |
| Dr. Lex Lambeck - Senior VP of Exploration | 100,000 | 0.07% |
| Dong H.Shim - CFO & Corporate Secretary | 1,205,000 | 0.79% |
| Jim Engdahl - Chairman | 342,000 | 0.22% |
| Greg Hahn - Vice Chairman | 4,924,589 | 3.23% |
| John McVey - Director | 180,000 | 0.12% |
| Yale Simpson - Director | 250,000 | 0.16% |
| 11,396,632 | 7.47% | |
| Other Major Investors | Shares | % of Total |
| Sorbie Bornholm | 22,500,000 | 14.76% |
| Evolution Mining Limited | 15,056,004 | 9.87% |
| Brady Stiles | 13,019,599 | 8.54% |
| 50,575,603 | 33.17% | |
| Total | 61,972,235 | 40.64% |
AZS has experienced management and board, with expertise across exploration, mine development, and capital markets. Specifically, exploration is led by Dr. Lex Lambeck, former VP of Exploration at MAG Silver, which was acquired by Pan American Silver for ~$2.1B in 2025.
Brief biographies of the management team and board members follow:
Mining executive with 35+ years of business experience, including corporate finance, capital markets, investor relations and strategic development. Previously associated with Exeter Resources and Extorre Resources, both of which were acquired following significant discoveries.
Exploration geologist with a PhD in geology and 25+ years of international experience across gold, silver, copper and base metals. Brings extensive exploration and senior management experience across the U.S., Canada, Mexico and Australia.
Veteran corporate-finance and mining executive with 40+ years of experience. Former Managing Partner at MNP Corporate Finance and President & CEO of Great Western Minerals Group, with extensive experience in financing, M&A, restructuring and resource development.
Mining executive and geological engineer with 35+ years of exploration and mine-development experience. Has advanced projects through permitting, financing, engineering, construction and production, including the Lisbon Valley copper mine.
Mining, energy and infrastructure executive with 35+ years of engineering and construction experience. Former CEO of Procon Group, and previously held senior roles with Bechtel, Bantrel and SNC-Lavalin, overseeing major international mining projects.
Geological engineer and mining entrepreneur with 40 years of international experience in exploration, resource planning, financing and corporate development. Co-founded Exeter Resources and Extorre Gold Mines, both subsequently acquired by major mining companies.
AZS has a strong balance sheet, with $12.5M in working capital, and no debt. Sorbie, a UK-based investment firm, has committed $18M in equity financing over 24 months, with proceeds released monthly, starting this month.
| (in C$) (FYE - Aug 31) | 2026 (9M) | Current Cash |
|---|---|---|
| Cash | $4,957,698 | ~$12,500,000 |
| Working Capital | $5,282,069 | |
| Current Ratio | 13.03 | |
| Debt | - | |
| Monthly Burn Rate (G&A) | -$68,748 | |
| Cash Spent on Properties | -$2,716,238 | |
| Cash from Financing Activities | $5,533,616 |
AZS can raise up to $10M from in-the-money options and warrants.
| # | Exercise Price ($) | Amount | |
|---|---|---|---|
| Total | 9,836,481 | $0.45 | $4,397,533 |
| In-the-Money | 8,586,481 | $0.38 | $3,297,333 |
| Warrants | # | Exercise Price ($) | Amount |
|---|---|---|---|
| Total | 32,633,032 | $0.68 | $22,064,565 |
| In-the-Money | 17,577,028 | $0.40 | $7,008,561 |
Valuation Methodology: We value AZS based on market valuations of gold juniors in the U.S. and Canada.
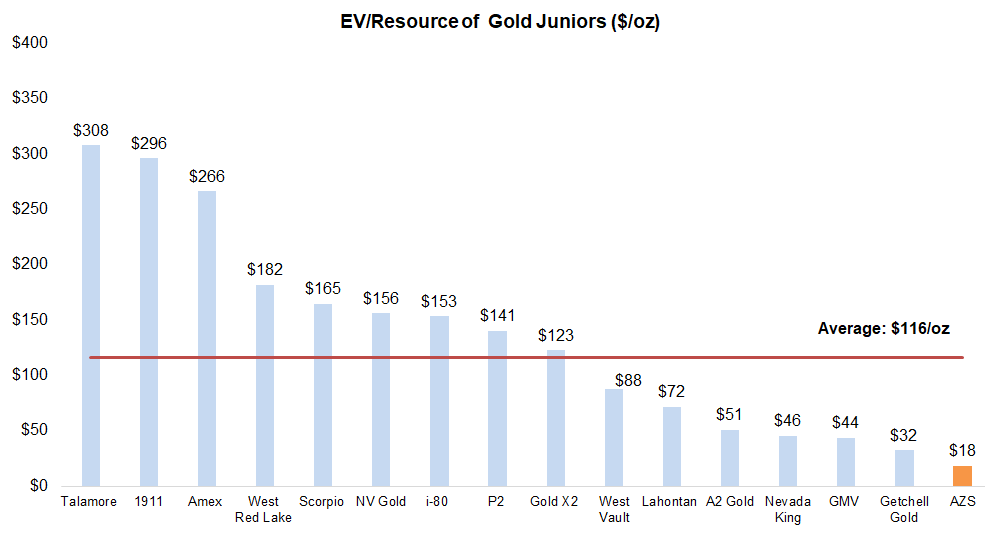
Significant Discount: AZS trades at just $18/oz based on our speculative estimate on Philadelphia, an 85% discount to the peer average of $116/oz, making it the most undervalued gold junior in our peer group. Fair Value Estimate: Applying the peer group’s average valuation multiple to our estimate on Philadelphia, we arrive at a fair value of $2.34/share. Conservative Valuation: Our valuation assigns no value to exploration upside or potential resources at Sycamore and Silverton.
| Gold Juniors | Net Resource* | Enterprise Value ($,M) | EV / Resource* | |
|---|---|---|---|---|
| 1 | Talamore Mining Corp. | 3,357,000 | $1,034 | $308.01 |
| 2 | 1911 Gold | 821,000 | $243 | $295.98 |
| 3 | Amex Gold Mining | 1,964,000 | $523 | $266.29 |
| 4 | West Red Lake Gold Mines | 2,088,606 | $380 | $181.94 |
| 5 | Scorpio Gold Corp | 521,975 | $86 | $164.76 |
| 6 | NV Gold | 250,000 | $39 | $156.00 |
| 7 | i-80 Gold | 11,747,500 | $1,801 | $153.31 |
| 8 | P2 Gold | 2,305,000 | $324 | $140.56 |
| 9 | Gold X2 Mining | 4,080,000 | $502 | $123.04 |
| 10 | West Vault Mining | 998,990 | $88 | $88.09 |
| 11 | Lahontan Gold | 1,744,500 | $125 | $71.65 |
| 12 | A2 Gold | 744,000 | $38 | $51.08 |
| 13 | Nevada King Gold | 1,119,600 | $51 | $45.55 |
| 14 | GMV Minerals | 344,000 | $15 | $43.60 |
| 15 | Getchell Gold | 1,483,050 | $48 | $32.37 |
| 16 | Bravada Gold | 743,220 | $22 | $29.60 |
| 17 | Arizona Gold and Silver | 3,369,800 | $60 | $17.81 |
| Average (excl outliers) | $116.35 | |||
| AZS's Resources - oz | 3,369,800 |
|---|---|
| Average EV/ Resource Ratio (comparables) | $116.35 |
| Fair Value of AZS | $422,582,824 |
| No. of Shares (treasury stock method) | 180,537,572 |
| Fair Value per Share (C$) | $2.34 |
For the companies used in this study, we use 100% of their Measured and Indicated (M&I) resources (higher-confidence categories), and 50% of inferred resources (lower-confidence). However, for AZS’ Philadelphia project, we apply 100% of our speculative estimate, given that only ~2% of its land package has been explored.
We are initiating coverage on AZS with a BUY rating, and a fair value estimate of $2.34/share, supported by Philadelphia’s multi million ounce potential, potential district-scale mineralization, and a strategic investment by Evolution Mining. AZS trades at an 85% discount to our peer group average, offering significant upside potential as exploration progresses. A strong balance sheet provides funding to advance exploration, while reducing the risk of near-term dilution.
We are assigning a risk rating of 5 (Highly Speculative). We believe the company is exposed to the following key risks (not exhaustive):
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Buy – Fair value is 12% above the current market price; or risk and reward is favorable
Hold – Fair value is between 5% to 12% above the current market price
Sell – Fair value is 5% above, or less, than the current market value; or risk and reward is unfavorable
Suspended or Rating N/A— Coverage and ratings suspended until more information can be obtained from the company regarding recent events.
1 (Low Risk) - The company operates in an industry where it has a strong position (for example a monopoly, high market share etc.) or operates in a regulated industry. The future outlook is stable or positive for the industry. The company generates positive free cash flow and has a history of profitability. The capital structure is conservative with little or no debt.
2 (Below Average Risk) - The company operates in an industry where the fundamentals and outlook are positive. The industry and company are relatively less sensitive to systematic risk than companies with a Risk Rating of 3. The company has a history of profitability and has demonstrated its ability to generate positive free cash flows (though current free cash flow may be negative due to capital investment). The company’s capital structure is conservative with little to modest use of debt.
3 (Average Risk) - The company operates in an industry that has average sensitivity to systematic risk. The industry may be cyclical. Profits and cash flow are sensitive to economic factors although the company has demonstrated its ability to generate positive earnings and cash flow. Debt use is in line with industry averages, and coverage ratios are sufficient.
4 (Speculative) - The company has little or no history of generating earnings or cash flow. Debt use is higher. These companies may be in start-up mode or in a turnaround situation. These companies should be considered speculative.
5 (Highly Speculative) - The company has no history of generating earnings or cash flow. They may operate in a new industry with new, and unproven products. Products may be at the development stage, testing, or seeking regulatory approval. These companies may run into liquidity issues and may rely on external funding. These stocks are considered highly speculative.
Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE.
Analyst Certification: The views expressed in this report accurately reflect the personal views of the analyst, and no part of their compensation was, is, or will be directly or indirectly related to the specific recommendation or views expressed.
Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The analyst and Fundamental Research Corp. “FRC” does not own any shares of the subject company, does not make a market or offer shares for sale of the subject company, and does not have any investment banking business with the subject company. Fees ranging between $20,000 and $30,000 have been paid to FRC by Arizona Gold & Silver Inc. to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. FRC takes steps to mitigate conflicts including setting fees in advance and utilizing analysts who must abide by CFA Institute Code of Ethics and Standards of Professional Conduct. Additionally, analysts may not trade in any security under coverage. Our full editorial control of all research, timing of release of the reports, and release of liability for negative reports are protected contractually. The issuer has agreed to a minimum coverage term and coverage cannot be unilaterally terminated. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time.
The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (28%).
This report contains "forward looking" statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company's products/services in the marketplace; acceptance in the marketplace of the Company's new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company's periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. A report initiating coverage will most often be updated quarterly while a report issuing a rating may have no further or less frequent updates because the subject company is likely to be in earlier stages where nothing material may occur quarter to quarter.
Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.