
Monument Mining Limited delivered record FY2026 revenue and net income while staying debt-free and building working capital to $122.86 million. This report examines production trends, operating performance, financial results, and the company’s outlook.
Record FY2026: Debt-Free, Cash-Rich & Deeply Undervalued
Paused · 7:53 left · FRC · read by an AI voice
Disclosure: Monument Mining Limited has paid FRC a fee for research coverage and distribution of reports. See last page for other important disclosures, rating, and risk definitions. This fee creates a potential conflict of interest which readers should consider.
Price and Volume (1-year)
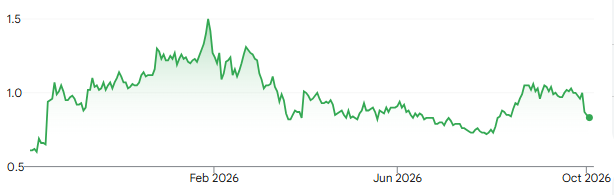
| YTD | 12M | |
|---|---|---|
| MMY | -34% | 29% |
| TSXV | -12% | -11% |
| Gold | -5% | 7% |
| GDXJ | 0% | 10% |
| Key Financial Data (YE - June 30) | |||||
|---|---|---|---|---|---|
| US$M, except EPS | 2024 | 2025 | 2026 | 2027E | 2028E |
| Gold Sales (oz) | 30,713 | 41,183 | 46,275 | 44,392 | 43,046 |
| Revenue | $51.42 | $98.64 | $165.72 | $149.16 | $137.75 |
| Net Income | $6.44 | $37.54 | $68.80 | $55.24 | $54.37 |
| EPS | $0.02 | $0.11 | $0.20 | $0.16 | $0.16 |
| Working Capital | $20.56 | $58.54 | $122.86 | $183.69 | $244.05 |
| Debt/Capital | 0% | 0% | 0% | 0% | 0% |
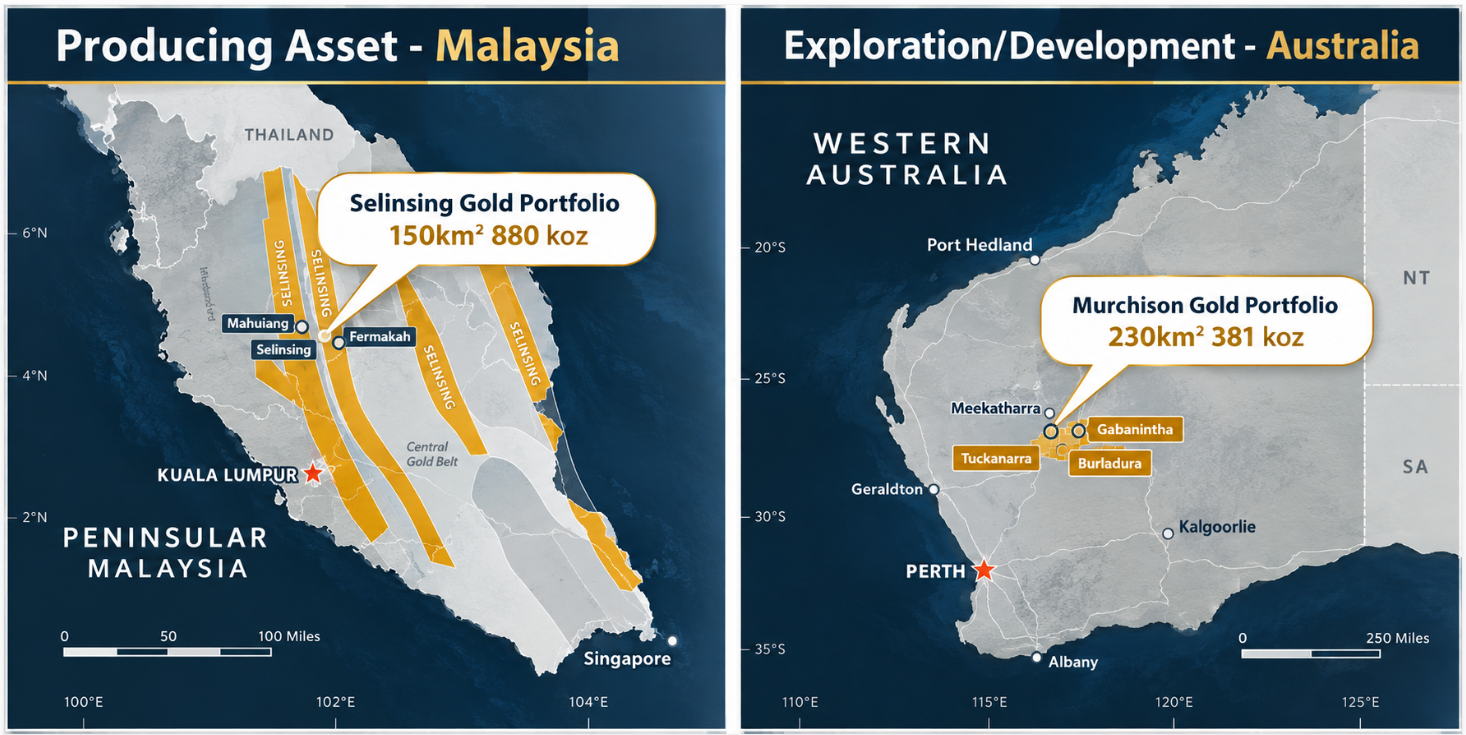
MMY owns a producing gold mine in Malaysia, and exploration projects in Western Australia, with over 1.2 Moz of independently verified, NI 43-101-compliant gold resources across its portfolio.
Since commencing sulphide processing in December 2022, MMY has produced 122 Koz through June 2026.
Production (Year-End: June 30th) - Oz
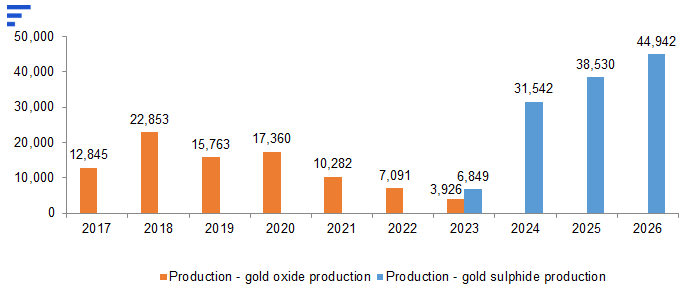
Q4 production declined 15% QoQ, primarily due to lower grades; while this is negative, we note quarterly fluctuations in grades are common in mining operations.
| Q4-2025 | Q1-2026 | Q2-2026 | Q3-2026 | Q4-2026 | YoY | QoQ | |
|---|---|---|---|---|---|---|---|
| Sulphides - Ore Processed (tonnes) | 235,264 | 239,447 | 224,704 | 243,367 | 234,007 | -1% | -4% |
| Grade (g/t Au) | 1.82 | 1.94 | 1.54 | 1.67 | 1.48 | -19% | -11% |
| Recovery Rate (%) | 89.5% | 87.6% | 92.5% | 89.8% | 88.8% | -1% | -1% |
| Gold Production (oz) | 12,315 | 13,092 | 10,249 | 11,700 | 9,902 | -20% | -15% |
| Gold Sold (oz) | 14,527 | 11,227 | 13,725 | 10,478 | 9,581 | -34% | -9% |
| Gold Price (realized) - US$/oz | $3,368 | $3,498 | $4,197 | $5,166 | $4,349 | 29% | -16% |
| Cash Cost (US$/oz) - Sulphides | $701 | $888 | $1,288 | $1,390 | $1,433 | 104% | 3% |
| Gross Profit (US$/oz) | $2,667 | $2,610 | $2,909 | $3,776 | $2,916 | 9% | -23% |
| AISC (US$/oz) | $853 | $1,037 | $1,421 | $1,583 | $1,898 | 123% | 20% |
Despite the sequential decline, FY2026 production rose 17% YoY to 45 Koz, just 3% below our 46 Koz forecast.
| 2023 | 2024 | 2025 | 2026 | YoY | |
|---|---|---|---|---|---|
| Sulphides - Ore Processed (tonnes) | 223,493 | 715,553 | 786,241 | 941,525 | 20% |
| Grade (g/t Au) | 1.80 | 1.84 | 1.79 | 1.66 | -7% |
| Recovery Rate (%) | 54.1% | 74.2% | 85.3% | 89.5% | 5% |
| Gold Production (oz) | 6,849 | 31,542 | 38,530 | 44,942 | 17% |
| Gold Sold (oz) | 1,148 | 30,713 | 41,183 | 45,010 | 9% |
| Gold Price (realized) - US$/oz | $1,800 | $2,116 | $2,947 | $4,280 | 45% |
| Cash Cost (US$/oz) - Sulphides | $917 | $866 | $814 | $1,243 | 53% |
| Gross Profit (US$/oz) | $293 | $1,250 | $2,133 | $3,037 | 42% |
| AISC (US$/oz) | $1,722 | $1,173 | $1,093 | $1,446 | 32% |
FY2026 gold prices rose 45% YoY to $4,280/oz, slightly below our $4,340 forecast. Additionally, cash costs rose 53% YoY to $1,243/oz, mainly due to higher gold price-linked royalty payments, but were in line with our $1,240/oz estimate. Gross profit rose 42% YoY to $3,037/oz.
Cash Costs Per Oz
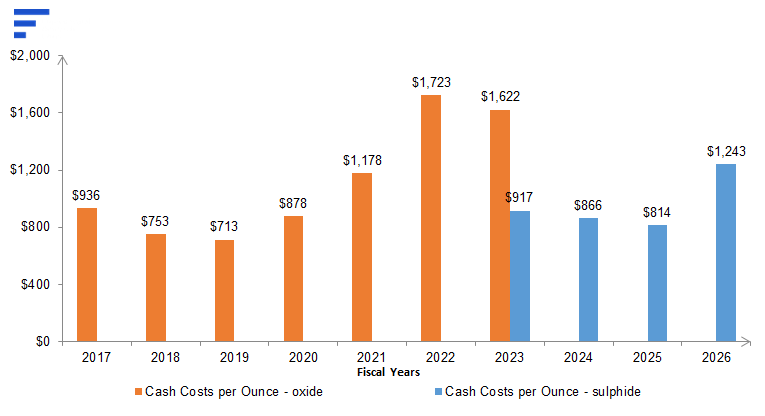
MMY plans to continue drilling to potentially expand resources and support future pit expansion.
Reserves and Resources (Snowden NI 43-101 Technical Report: 2019)
| Category | OXIDE (above 0.3 g/t Au cut-off) | TRANSITION (above 0.5 g/t Au cut-off) | SULPHIDE (above 0.5 g/t Au cut-off) | OXIDE + TRANSITION + SULPHIDE | ||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| KTonnes | g/t | Au (kOz) | KTonnes | g/t | Au (kOz) | KTonnes | g/t | Au (kOz) | KTonnes | g/t | Au (kOz) | |
| MINERAL RESOURCES, REPORTED INCLUSIVE OF MINERAL RESERVES (BASED ON A POTENTIAL US$2,400/OZ GOLD PRICE) | ||||||||||||
| Measured* | 1,265 | 0.47 | 19 | - | - | - | 45 | 1.53 | 2 | 1,310 | 0.51 | 21 |
| Indicated** | 1,533 | 0.85 | 42 | 1,086 | 1.49 | 52 | 8,052 | 1.60 | 415 | 10,671 | 1.48 | 509 |
| M+I | 2,798 | 0.68 | 61 | 1,086 | 1.49 | 52 | 8,097 | 1.60 | 417 | 11,981 | 1.38 | 530 |
| In-ferred*** | 349 | 1.05 | 11.8 | 485 | 1.22 | 19 | 5,563 | 1.79 | 319 | 6,397 | 1.70 | 350 |
FY2026 revenue rose 68% YoY, EBITDA 65%, and EPS 74%, driven by higher gold prices and production. However, revenue missed our forecast by 2.9%, primarily due to lower than expected Q4 production, while EPS missed by 0.2%.
| Summary of Operations | |||||
|---|---|---|---|---|---|
| US$M / YE - June 30th | 2023 | 2024 | 2025 | 2026 | YoY |
| Revenue | $12.39 | $51.42 | $98.64 | $165.72 | 68% |
| COGS | $10.64 | $26.59 | $33.53 | $55.96 | 67% |
| Gross Profit | $1.75 | $24.83 | $65.11 | $109.76 | 69% |
| EBITDA | -$0.21 | $22.41 | $62.95 | $103.56 | 65% |
| Net Income | -$6.27 | $6.44 | $37.54 | $68.80 | 83% |
| EPS | -$0.02 | $0.02 | $0.11 | $0.20 | 74% |
| Margins | 2023 | 2024 | 2025 | 2026 | Sector |
|---|---|---|---|---|---|
| Gross | 14.1% | 48.3% | 66.0% | 66.2% | 20.4% |
| EBITDA | -1.7% | 43.6% | 63.8% | 62.5% | 13.1% |
| EBIT | -31.9% | 26.6% | 51.8% | 53.2% | 11.8% |
| Net | -50.6% | 12.5% | 38.1% | 41.5% | 10.3% |
Gross and net margins improved YoY, remaining well above sector averages.
| Summary of Cash Flows | |||||
|---|---|---|---|---|---|
| US$M / YE - June 30th | 2023 | 2024 | 2025 | 2026 | YoY |
| Funds Flow from Operations | -$0.77 | $20.83 | $51.16 | $84.44 | 65% |
| Cash Flow From Operations | $0.12 | $14.39 | $48.65 | $82.21 | 69% |
| Cash flow Used in investing | -$15.12 | -$9.37 | -$13.54 | -$85.93 | N/A |
| Cash flow Used in financing | -$0.08 | -$0.12 | -$0.03 | -$5.11 | N/A |
| Net Change in Cash | -$15.08 | $4.90 | $35.08 | -$8.84 | N/A |
| Free Cash Flows | -$15.00 | $5.02 | $35.11 | $68.73 | 96% |
Free cash flow increased 96% YoY.
| Liquidity Analysis | |||||
|---|---|---|---|---|---|
| US$M / YE June 30th | 2023 | 2024 | 2025 | 2026 | Sector |
| Cash + Short-Term Inv. | $5.96 | $10.86 | $45.94 | $109.56 | - |
| Working Capital | $9.82 | $20.56 | $58.54 | $122.86 | - |
| Current Ratio | 2.0 | 3.1 | 6.0 | 16.5 | 1.9 |
| Debt/Capital | 0.0% | 0.0% | 0.0% | 0.0% | 17% |
| LT Debt/Capital | 0.0% | 0.0% | 0.0% | 0.0% | 12% |
As a result, the balance sheet strengthened, with $123M in working capital, and no debt.
| Options | Exercise Price (C$) | Amount (C$) | |
|---|---|---|---|
| Total | 1,716,661 | $0.15 | $248,916 |
| In-the-Money | 1,716,661 | $0.15 | $248,916 |
| Warrants | Exercise Price (C$) | Amount | |
|---|---|---|---|
| Total | - | - | - |
| In-the-Money | - | - | - |
| FY2027E (Old) | FY2027E (New) | FY2028E (Introducing) | |
|---|---|---|---|
| Gold Price ($/oz) | $4,200 | $4,200 | $4,000 |
| Gold Sales (oz) | 43,062 | 44,392 | 43,046 |
| Revenue ($M) | $144.69 | $149.16 | $137.75 |
| EBITDA ($M) | $86.73 | $86.18 | $85.33 |
| Net Profit ($M) | $53.87 | $55.24 | $54.37 |
| EPS | $0.16 | $0.16 | $0.16 |
We have made minor changes to our FY2027 forecasts. Additionally, sector multiples have contracted 5% since our June 2026 report, reflecting weaker gold prices. MMY trades at 0.49x forward revenue vs. 1.46x for peers (66% discount). Similarly, MMY trades at 0.85x forward EBITDA vs. 2.89x for peers (71% discount).
| Junior Gold Producers | Enterprise Value (C$M) | MCAP (C$M) | EV/Forward Revenue | EV / Forward EBITDA |
|---|---|---|---|---|
| Orezone Gold Corporation (TSX:ORE) | $2,330 | $2,308 | 1.59 | 2.90 |
| Alkane Resources Ltd (ASX:ALK) | $2,098 | $2,511 | 2.16 | 3.87 |
| McEwen Inc. (NYSE:MUX) | $1,597 | $1,545 | 4.46 | 7.78 |
| Galiano Gold Inc. (TSX:GAU) | $730 | $722 | 0.77 | 1.66 |
| Integra Resources Corp. (TSXV:ITR) | $623 | $737 | 1.43 | 4.78 |
| Caledonia Mining (NYSEAM:CMCL) | $619 | $655 | 1.42 | 2.96 |
| Thor Explorations Ltd. (TSXV:THX) | $512 | $787 | 1.00 | 1.40 |
| Serabi Gold plc (AIM:SRB) | $253 | $342 | 0.73 | 1.30 |
| Namib Minerals (NasdaqGM:NAMM) | $112 | $104 | 0.55 | 1.45 |
| Monument Mining (TSXV:MMY) | $104 | $277 | 0.49 | 0.85 |
| Average (excl. outliers) | 1.46 | 2.89 | ||
| Fair Value of Selinsing @ Sector Average | $1.02 | $1.17 | ||
| MMY's Discount | -66% | -71% |
Using a sum-of-parts valuation, we arrived at a fair value estimate of $1.94/share (previously $1.82/share). The increase reflects our higher revenue and EPS estimates, partially offset by lower sector multiples.
| Financial Summary (C$) | Value (C$M) | VPS (C$) |
|---|---|---|
| Selinsing | ||
| :DCF | $499.46 | $1.44 |
| :Comparables | $462.62 | $1.33 |
| Average | $481.04 | $1.38 |
| Murchison | $19.78 | $0.06 |
| Working Capital-Debt | $174.46 | $0.50 |
| Fair Value Estimate | $675.27 | $1.94 |
We are reiterating our BUY rating, and adjusting our fair value estimate from $1.82 to $1.94 per share. We remain positive on MMY, supported by its stron cash generation, debt-free balance sheet, and opportunities to expand its asset and production base. Despite these strengths, MMY trades at a significant discount to peers, offering meaningful upside potential, as the market increasingly recognizes its growth prospects.
We are maintaining our risk rating of 3 (Average).
We believe the company is exposed to the following key risks:
| Income Statement | |||||
|---|---|---|---|---|---|
| US$M / YE - June 30th | 2024 | 2025 | 2026 | 2027E | 2028E |
| Revenues | $51.42 | $98.64 | $165.72 | $149.16 | $137.75 |
| Other Revenue | |||||
| Total Revenue | $51.42 | $98.64 | $165.72 | $149.16 | $137.75 |
| Cost of Goods Sold | $26.59 | $33.53 | $55.96 | $57.71 | $47.03 |
| Gross Profit | $24.83 | $65.11 | $109.76 | $91.44 | $90.72 |
| G&A | $2.42 | $2.16 | $6.20 | $5.27 | $5.40 |
| EBITDA | $22.41 | $62.95 | $103.56 | $86.18 | $85.33 |
| Depreciation | $8.73 | $11.88 | $15.44 | $15.82 | $16.22 |
| EBIT | $13.68 | $51.08 | $88.13 | $70.36 | $69.11 |
| Interest | $0.27 | $1.04 | $3.08 | $3.30 | $3.39 |
| FOREX | -$2.56 | -$2.64 | $0.23 | ||
| Other | $0.29 | -$0.02 | -$0.01 | ||
| EBT Incl. Unusual Items | $11.68 | $49.45 | $91.43 | $73.66 | $72.50 |
| Income Tax | -$5.24 | -$11.91 | -$22.63 | -$18.41 | -$18.12 |
| Net Income | $6.44 | $37.54 | $68.80 | $55.24 | $54.37 |
| EPS | $0.02 | $0.11 | $0.20 | $0.16 | $0.16 |
| Cash Flow | |||||
|---|---|---|---|---|---|
| US$M / YE - June 30th | 2024 | 2025 | 2026 | 2027E | 2028E |
| Net Income | $6.44 | $37.54 | $68.80 | $55.24 | $54.37 |
| Depreciation & Amort. | $8.78 | $11.94 | $15.49 | $15.82 | $16.22 |
| Share-based compensation | $0.33 | $0.01 | $0.01 | ||
| FOREX | $1.89 | $1.56 | -$0.23 | ||
| Loss/Gain on asset disposal | -$0.19 | $0.03 | $0.01 | ||
| Tax | $3.58 | $0.09 | $0.37 | ||
| Changes in Working Capital | -$6.45 | -$2.51 | -$2.24 | -$1.68 | -$0.85 |
| Cash Flow From Operations | $14.39 | $48.65 | $82.21 | $69.39 | $69.74 |
| PPE, Exploration, & Evaluation | -$10.05 | -$13.54 | -$13.47 | -$10.00 | -$10.00 |
| Others | 0.681 | -$72.46 | |||
| Cash Flow From Investing | -$9.37 | -$13.54 | -$85.93 | -$10.00 | -$10.00 |
| Lease | -$0.09 | -$0.07 | -$0.23 | -$0.23 | -$0.23 |
| Equity | $0.04 | -$4.88 | |||
| Borrowings | -$0.03 | - | - | ||
| Cash Flow From Financing | -$0.12 | -$0.03 | -$5.11 | -$0.23 | -$0.23 |
| Balance Sheet | |||||
|---|---|---|---|---|---|
| US$M / YE - June 30th | 2024 | 2025 | 2026 | 2027E | 2028E |
| ASSETS | |||||
| Cash + Short-Term Inv. | $10.86 | $45.94 | $109.56 | $168.71 | $228.22 |
| Accounts Receivable | $5.95 | $11.85 | $8.33 | $9.17 | $10.08 |
| Inventory | $12.76 | $11.62 | $11.94 | $13.14 | $14.45 |
| Prepaid Exp. and Others | $0.98 | $0.89 | $0.97 | $1.07 | $1.18 |
| Total Current Assets | $30.55 | $70.30 | $130.81 | $192.09 | $253.93 |
| PPE+Inventory | $63.09 | $62.71 | $57.66 | $54.75 | $51.64 |
| Exploration & Evaluation | $48.38 | $49.85 | $56.62 | $53.70 | $50.60 |
| Total Assets | $142.02 | $182.86 | $245.08 | $300.54 | $356.17 |
| LIABILITIES | |||||
| Accounts Payable | $7.87 | $6.46 | $4.47 | $4.92 | $5.41 |
| Lease Liabilities | $0.06 | $0.06 | $0.16 | $0.16 | $0.16 |
| Income Tax Payable | $2.05 | $5.24 | $3.32 | $3.32 | $3.32 |
| Total Current Liabilities | $9.99 | $11.76 | $7.95 | $8.39 | $9.89 |
| Borrowings | $0.00 | $0.00 | $0.00 | $0.00 | $0.00 |
| Lease Liabilities | $0.11 | $0.07 | $0.03 | $0.03 | $0.03 |
| ARO | $6.84 | $7.88 | $9.46 | $9.46 | $9.46 |
| Deferred Tax Liabilities | $3.94 | $4.38 | $4.87 | $4.87 | $4.87 |
| Total Liabilities | $20.86 | $24.08 | $22.31 | $22.76 | $24.25 |
| Share Capital + Reserves | $131.58 | $131.67 | $131.88 | $131.65 | $131.41 |
| Retained Earnings | -$10.43 | $27.11 | $90.89 | $146.13 | $200.51 |
| Total Equity | $121.15 | $158.78 | $222.77 | $277.78 | $331.92 |
| Liabilities and Equity | $142.02 | $182.86 | $245.08 | $300.54 | $356.17 |
Sid Rajeev, B.Tech, MBA, CFA — Head of Research, Fundamental Research Corp.
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Disclosures. Fees ranging between C$20,000 and C$30,000 have been paid to FRC by Monument Mining to commission this report, research coverage, and distribution of reports. The analyst and Fundamental Research Corp. “FRC” do not own any shares of the subject company, do not make a market or offer shares for sale of the subject company, and do not have any investment banking business with the subject company. Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE. Buy – Fair value is 12% above the current market price; or risk and reward is favorable. 3 (Average Risk) - The company operates in an industry that has average sensitivity to systematic risk. The industry may be cyclical. Profits and cash flow are sensitive to economic factors although the company has demonstrated its ability to generate positive earnings and cash flow. Debt use is in line with industry averages, and coverage ratios are sufficient. The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (22%). ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST.
Why won't management commit to another special dividend or opportunistic share repurchase at this point -- this will be the question that weighs on every investor's mind and why the stock won't re-rate. There is just so much cash.
Thank you for the question. This is an important point, and we agree that greater clarity on MMY’s capital allocation strategy would be valuable. As noted on page 1 of our report, we believe management is prioritizing the advancement of Murchison, and potentially pursuing acquisitions to expand its asset base and production. We anticipate potential developments in these areas, although the timing and nature remain uncertain.
@sidr_analystPrecisely this is what weighs on the stock. Management's history of making value-destroying acquisitions in the past.
Hi! Have you talked to them? The more investor feedback they get the better...
Your analyses exclude any value for our Murchison assets which seem to be moving into initial production in 2027 based on recent hirings….what asset value should be added for Murchison
Thank you, gwinter45, for your feedback. We do assign value to Murchison based on its gold resources, using the market value per contained gold ounce for comparable junior gold companies. Please see the valuation summary table at the end of the report, where you will find a separate line item for Murchison and our fair value estimate.
An excellent review , analyses and forward projections .
Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.