
We are initiating coverage with a BUY rating, and a fair value estimate of $0.64/share, based on the average of our three valuation methodologies. The company is addressing a growing digital IP protection market, with a differentiated focus on 3D digital assets, and proactive infringement detection.
Disclosure: SECUR3D Holdings Inc. has paid FRC a fee for research coverage and distribution of reports. This fee creates a potential conflict of interest which readers should consider. See last page for other important disclosures, rating, and risk definitions.
All figures are in C$.
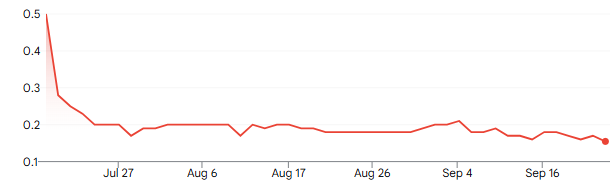
| YTD | 12M | |
|---|---|---|
| SRD | N/A | N/A |
| CSE | 0% | 4% |
| XIT* | 0% | -3% |
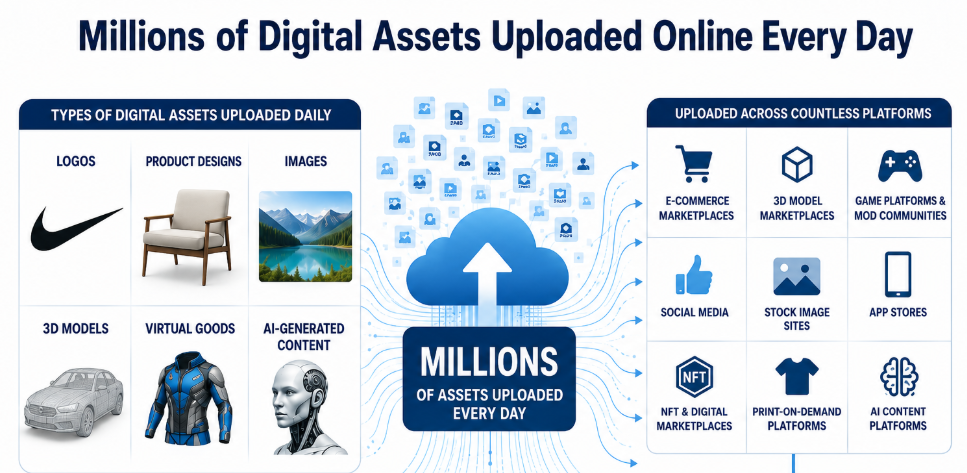
Every day, businesses, brands, creators, developers, and consumers upload millions of digital assets to online platforms.
Digital assets primarily include product designs, logos, images, videos, software code, documents, 3D models, gaming content, and other proprietary digital files.
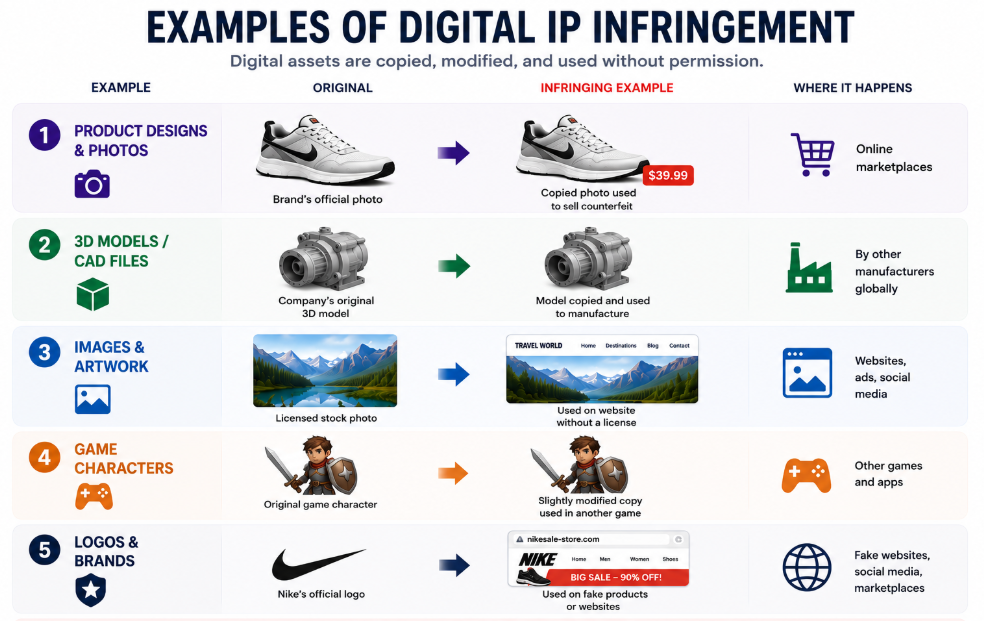
The rapid growth of digital content has created significant intellectual property (IP) challenges. Unlike physical products, digital assets can be copied, modified, and redistributed almost instantly at virtually no cost. Moreover, AI has accelerated this trend, enabling digital assets to be copied and modified in seconds, making infringement faster, cheaper, and harder to detect.
Digital IP infringement can cause revenue losses, brand damage, counterfeiting, legal costs, and weaker returns on innovation.
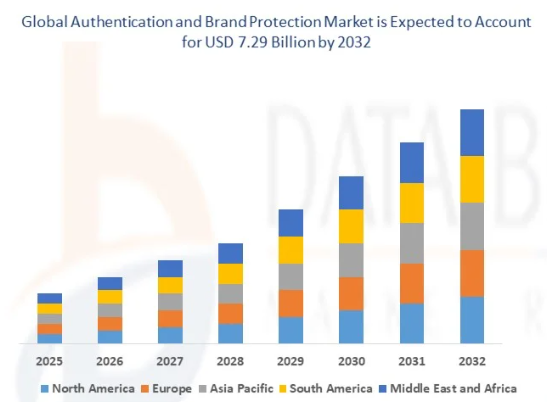
Brands are ramping up spending to safeguard digital IP. Specifically, the global authentication & brand protection market is forecast to grow from $3.5B (2024) to $7.3B (2032), a 10% CAGR.
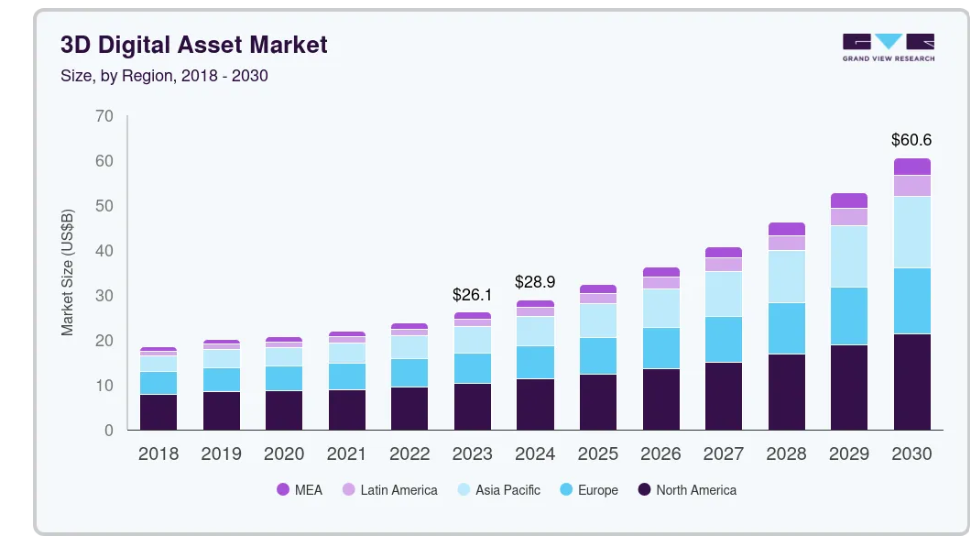
Similarly, the global 3D digital asset market is projected to grow from $26.1B (2023) to $36.2B (2026) and $60.6B (2030), a 13% CAGR over 2023–2030, representing a growing market for SECUR3D’s IP protection solutions.
Enterprises generally use two approaches to combat digital IP infringement: online marketplaces and social platforms use proprietary AI to detect and block infringing content, while brands rely on internal legal/IP teams and/or third-party providers to monitor online channels, identify unauthorized IP use, and facilitate takedowns.
Digital IP is primarily protected through platform moderation and third-party brand protection services.
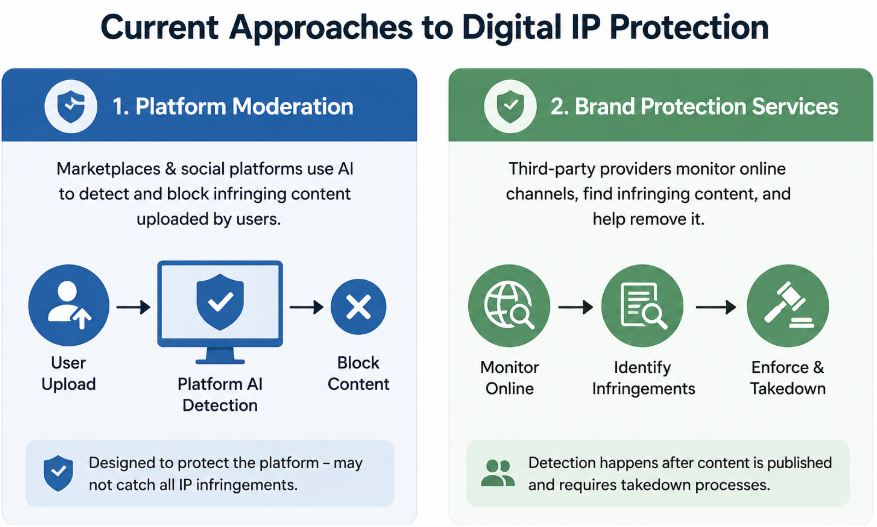
However, both approaches have limitations. Platform AI is mainly designed to enforce platform rules, while third-party providers monitor online channels, and handle IP takedowns. Moreover, most solutions focus on images, logos, and trademarks, while digital 3D models and designs require specialized detection, as identifying infringement requires analyzing an asset’s underlying geometry, structure, and shape, not simply its visual appearance.
SECUR3D’s platform is powered by Sherlock AI, a proprietary engine that combines multiple AI technologies to analyze digital assets, identify similarities to protected IP, and detect potential infringement. However, the processes are proprietary but not patented, with the company relying on confidentiality rather than public disclosure required for patent protection.
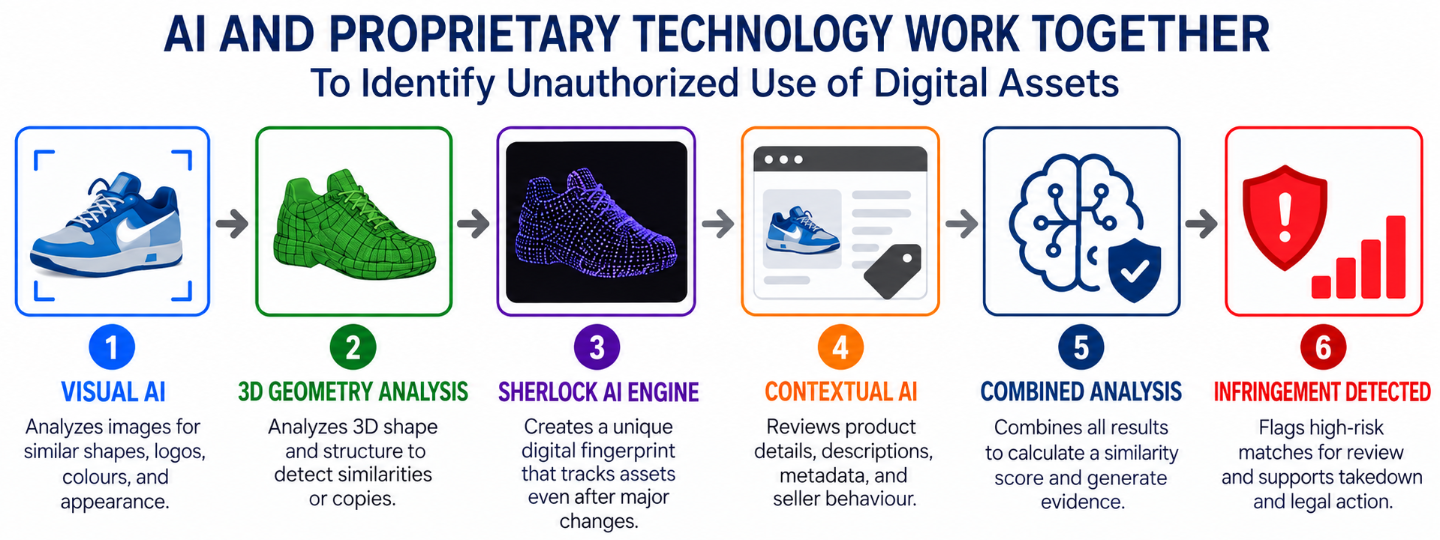
We believe SECUR3D's solutions aim to address several limitations of traditional digital IP protection models through the following capabilities:
AssetSafe adds another layer of protection beyond the tools already used by online marketplaces. Specifically, through partnerships with online platforms, it analyzes newly uploaded digital content using proprietary fingerprinting technology to identify potential matches with protected assets. It provides evidence of potential infringement, while customers or platforms make the final decision to allow, block, remove, or escalate flagged content.
Fingerprinting creates a unique digital signature for an asset, allowing it to be recognized even if modified. AssetSafe scans uploaded digital assets, compares them against protected IP, and flags potential infringements before they are widely distributed.
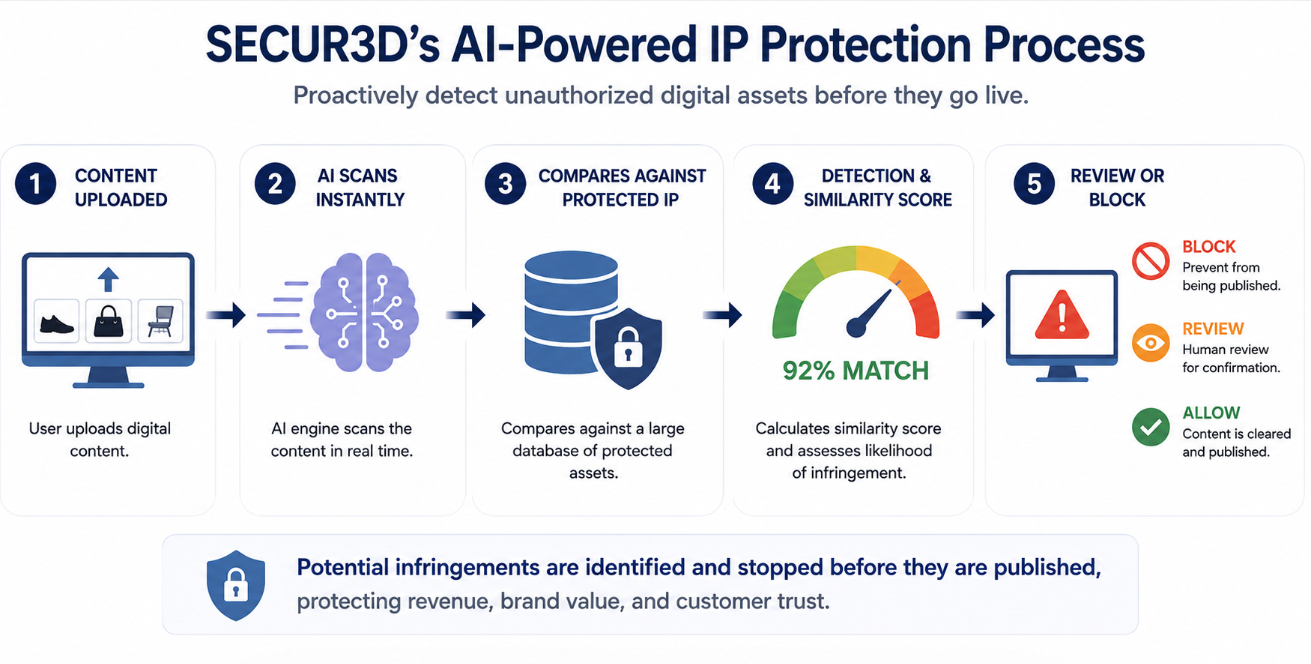
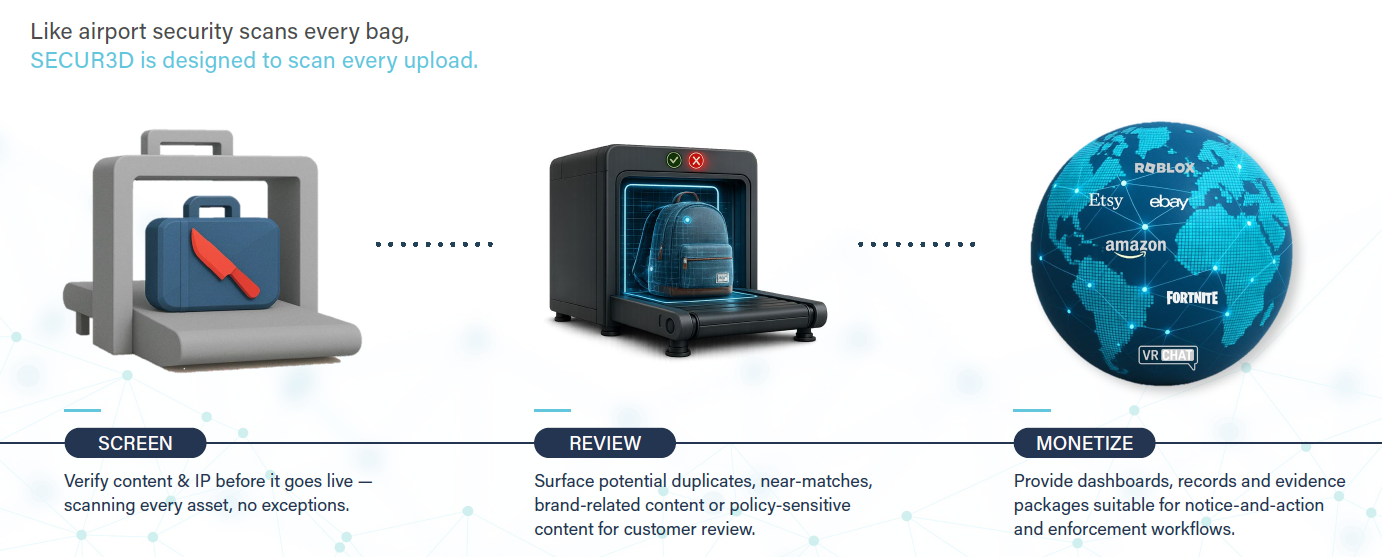
Management likens this proactive approach to airport security, where passengers are screened before boarding.
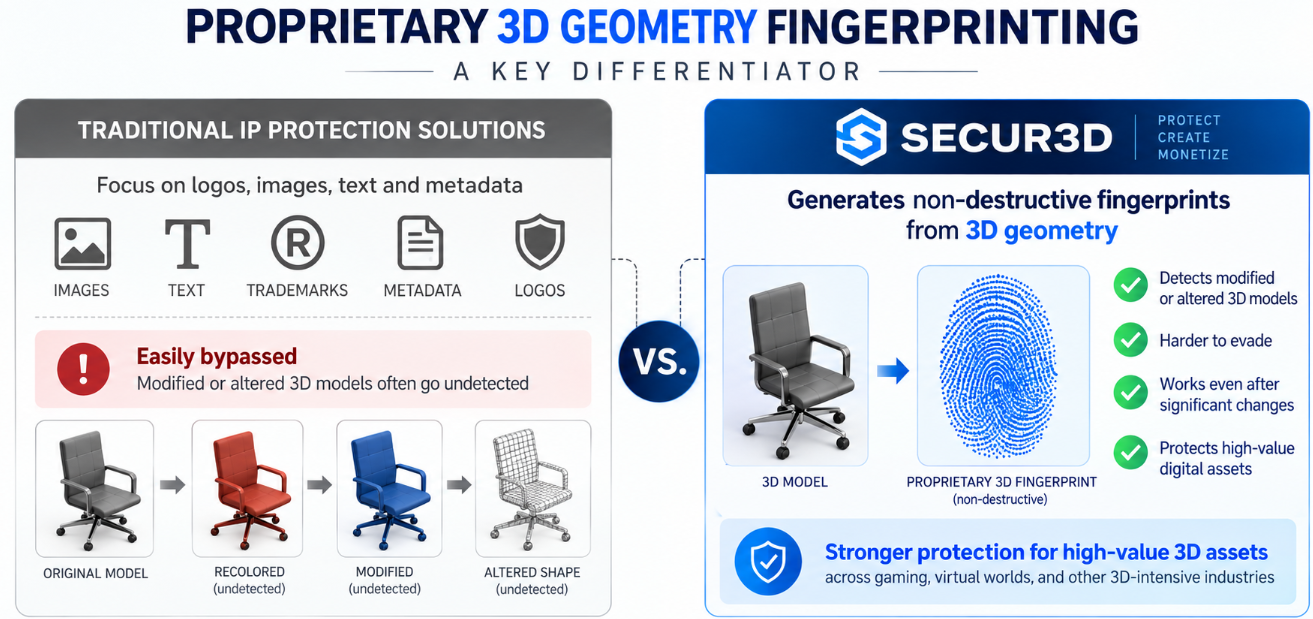
A second key capability is protecting 3D digital assets, an area largely overlooked by traditional IP protection solutions. These solutions focus mainly on logos, images, trademarks, and text. By contrast, SECUR3D’s Geometry Analysis examines 3D model shapes to identify similarities or copies, providing a potential differentiator as most solutions remain focused on 2D content.
SECUR3D’s 3D geometry fingerprinting is designed to detect modified or copied 3D models that traditional IP protection tools may miss.
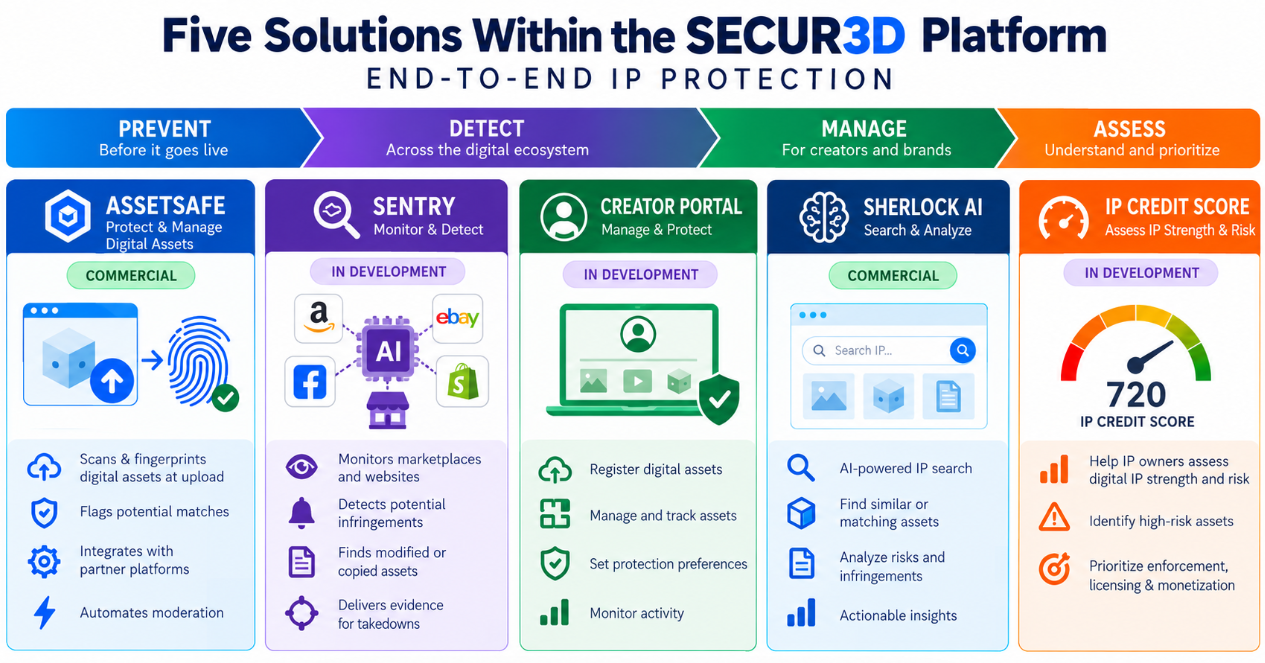
SECUR3D is building an end-to-end digital IP protection platform, designed to prevent infringement, detect unauthorized use, and support enforcement across online channels. AssetSafe and Sherlock AI are currently in market.
The digital IP protection market includes both established IP protection providers and newer AI-focused platforms. Most competing solutions offer counterfeit detection, content monitoring & post-publication enforcement, with $30,000–$100,000 annual contracts. However, we believe SECUR3D is differentiated by its focus on 3D digital assets and proactive detection at upload, before content is published.
| COMPANY | FOCUS | EST. ANNUAL CONTRACT | COMPANY ESTABLISHED |
|---|---|---|---|
| HIVE | AI content moderation | Custom / usage-based | 2013 |
| MARQVISION | AI brand & counterfeit protection | Custom | 2020 |
| RED POINTS | Online brand protection | US$35K – US$70K | 2011 |
| BRANDSHIELD | Counterfeit & threat protection | US$22K+ | 2013 |
| CORSEARCH | Trademark & IP protection | Custom (~US$70K avg. SMB) | 2018 |
| MIDNIGHT LABS | AI infringement detection | Custom / not disclosed | 2023 |
| SECUR3D | 3D asset protection & infringement detection | US$25K – US$250K | 2022 |
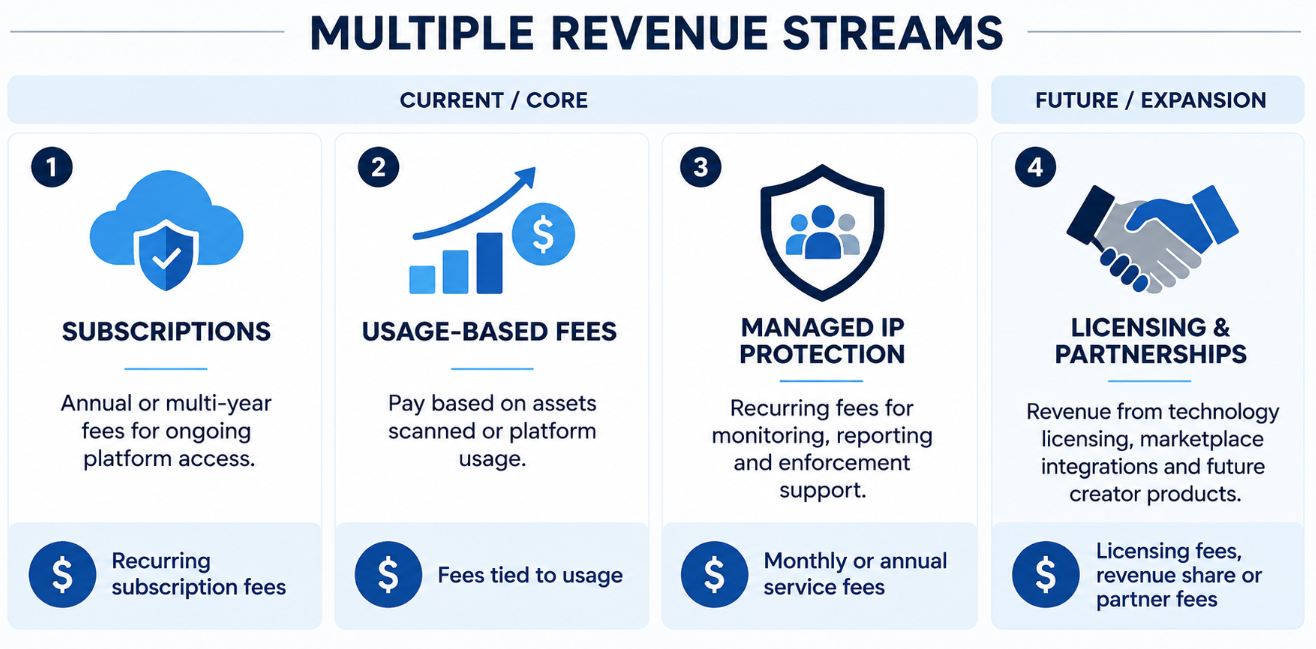
SECUR3D’s business model is built on recurring software subscriptions (SaaS), with additional revenue from usage-based fees, IP protection services, and future licensing.
SECUR3D has attracted 14 customer and partner relationships across fashion, gaming and entertainment. We believe these relationships provide early validation of the platform, although revenue from these relationships has not yet been disclosed.
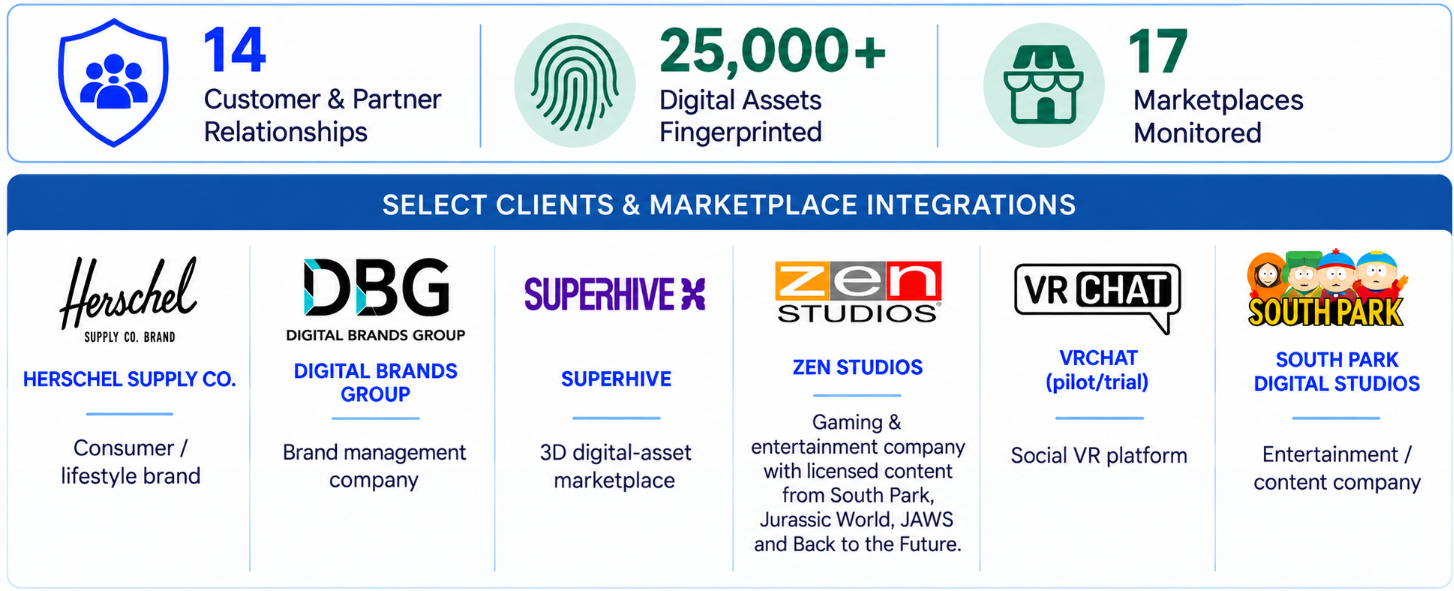
Target customers include online marketplaces, digital platforms, brands/IP owners and creators, with a focus on larger enterprise relationships. Additionally, competition is intense, with both established providers and smaller AI-focused companies.
We believe differentiation and an early track record will be critical, as competitors could add similar 3D capabilities. Building on its current customer and partner relationships, the company can potentially develop case studies and customer references to support customer acquisition.
The head office is in Vancouver, Canada. The company has seven full-time employees and one contractor. The Founder-CEO owns ~28% of the company. In total, management and board own 36%.
| Management and Board Members | Shares | % of Total |
|---|---|---|
| Otis Perrick – CEO & Director | 16,980,200 | 27.60% |
| Nitesh Mistry – President | 2,185,000 | 3.55% |
| Nigel Metcalf - Head of Product | 1,710,000 | 2.78% |
| Shawn Sadler - Fractional CTO | - | - |
| Sheri Rempel - CFO & Corporate Secretary | - | - |
| Nick Malaperiman - Independent Director | 300,000 | 0.49% |
| Scott Souter - Independent Director | 700,000 | 1.14% |
| Kylie Dickson - Independent Director | 300,000 | 0.49% |
| Chris Breikss - Independent Director | 200,000 | 0.33% |
| Total | 22,375,200 | 36.36% |
Brief biographies of the company’s management team and board members follow:
Four out of five directors are independent. Led by executives with experience at Electronic Arts, Microsoft, Nokia, and Unity, we believe the team brings deep expertise in developing, commercializing, and scaling enterprise software platforms.
At the end of Q3-FY2026, the company had $0.37M in cash, $0.23M in working capital, and no debt. The company is currently pursuing a $1.5M equity financing.
| YE: Sep 30th | FY2026 (9M) |
|---|---|
| Revenue | - |
| Loss from Operations | -$1,556,608 |
| EPS | -$0.03 |
| Cash | $370,743 |
| Working Capital | $227,748 |
| LT-Debt | - |
| Assets | $445,008 |
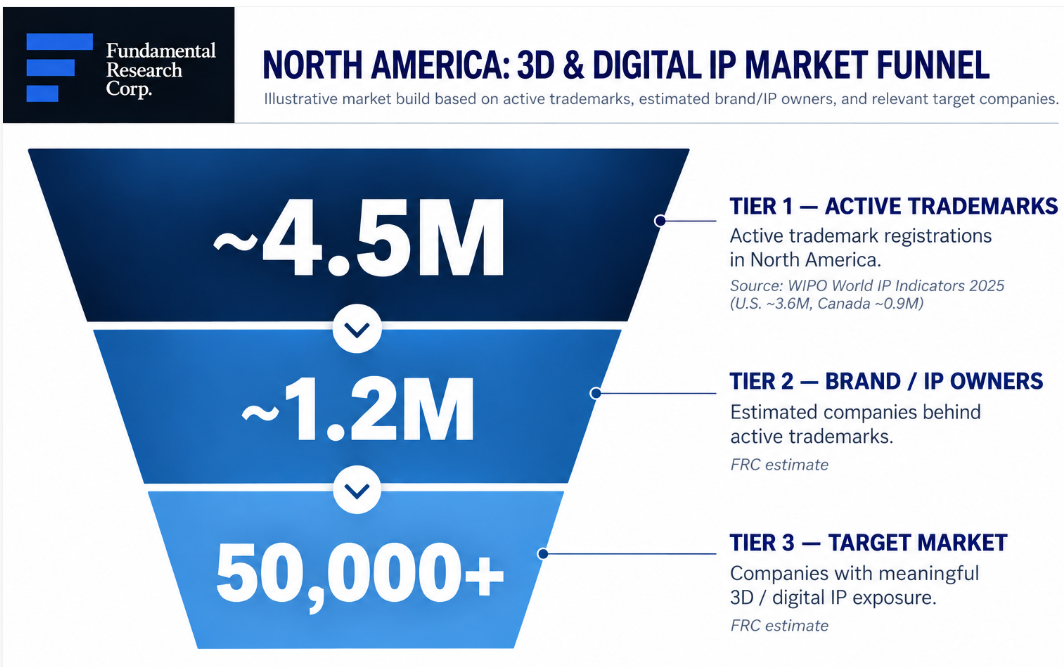
For valuation purposes, we start with active trademarks in North America, use a rough estimate of the number of companies behind them, and narrow the universe to businesses with digital IP exposure. Based on this approach, we estimate SECUR3D’s potential North American target market is ~50,000 companies.
Our DCF valuation is $0.64/share. We assume ~1% market penetration by 2031-2032, representing 500+ customers from a potential market of ~50,000.
Annual contract values and margin assumptions are broadly aligned with comparables.
| SECUR3D (FRC Estimates) | 2027E | 2028E | 2029E | 2030E | 2031E | 2032E | 2033E | Terminal |
|---|---|---|---|---|---|---|---|---|
| New customers | 25 | 50 | 90 | 130 | 170 | 210 | 20 | |
| Total Customers | 25 | 75 | 165 | 295 | 465 | 675 | 695 | |
| Average Annual Contract Value | $50,000 | $50,000 | $50,000 | $50,000 | $50,000 | $50,000 | $50,000 | |
| Revenue | $625,000 | $2,500,000 | $6,000,000 | $11,500,000 | $19,000,000 | $28,500,000 | $34,256,250 | |
| Gross Margin | 70% | 70% | 70% | 70% | 70% | 70% | 70% | |
| Gross Profit | $437,500 | $1,750,000 | $4,200,000 | $8,050,000 | $13,300,000 | $19,950,000 | $23,979,375 | |
| EBITDA | $218,750 | $875,000 | $2,100,000 | $4,025,000 | $6,650,000 | $9,975,000 | $11,989,688 | |
| Free Cash Flow | $175,000 | $700,000 | $1,680,000 | $3,220,000 | $5,320,000 | $7,980,000 | $9,591,750 | $82,329,188 |
| Present Value | $152,174 | $529,301 | $1,104,627 | $1,841,045 | $2,644,980 | $3,449,974 | $3,605,894 | $30,950,591 |
| WACC | 15% | |||||||
| AT-NPV | $44,376,587 | |||||||
| Working Capital - LT Debt* | $1,652,748 | |||||||
| Fair Value | $46,029,335 | |||||||
| # of Shares* | 71,531,371 | |||||||
| Fair Value per Share | $0.64 |
SECUR3D spans several technology segments, so no single company provides a direct comparison. Therefore, we use a broader peer set across AI software, digital IP protection, cybersecurity, and enterprise SaaS to benchmark SECUR3D’s valuation.
SECUR3D trades at a 79% average discount to forward peer multiples: 0.74x vs. 3.15x revenue; 2.10x vs. 11.20x EBITDA. The implied fair value is $0.57/share based on revenue, and $0.70/share based on EBITDA.
| Secur3d vs Larger Players | Business | MCAP, $M | Enterprise Value (EV, $M) | Revenue, $M | Gross Margin | EV/R (f) | EV/EBITDA (f) |
|---|---|---|---|---|---|---|---|
| SentinelOne | Cybersecurity | $11,701 | $10,777 | $1,549 | 73% | 6.42 | 48.93 |
| Qualys | Cybersecurity | $8,939 | $8,023 | $991 | 83% | 7.82 | 17.17 |
| Pegasystems | Enterprise Software | $8,042 | $7,634 | $2,447 | 76% | 2.94 | 10.78 |
| Tenable | Cybersecurity | $5,575 | $5,749 | $1,471 | 78% | 3.81 | 14.72 |
| SoundHound AI | AI | $3,831 | $3,553 | $286 | 42% | 10.01 | n/a |
| DoubleVerify | Digital Verification | $2,927 | $2,789 | $1,083 | 82% | 2.45 | 7.16 |
| C3.ai | Enterprise AI | $2,459 | $1,625 | $328 | 29% | 5.21 | n/a |
| Integral Ad Science | Digital Verification | $2,446 | $2,299 | $833 | 77% | 2.80 | 14.10 |
| Progress Software | Enterprise Software | $2,348 | $4,073 | $1,415 | 86% | 2.89 | 7.26 |
| BigBear.ai | Enterprise AI | $1,953 | $1,535 | $186 | 28% | 7.33 | n/a |
| Rapid7 | Cybersecurity | $1,221 | $1,586 | $1,207 | 69% | 1.36 | 7.20 |
| Coveo Solutions | Enterprise Software | $392 | $262 | $213 | 78% | 1.02 | 41.56 |
| Veritone | Enterprise AI | $181 | $231 | $128 | 66% | 1.61 | n/a |
| Intelligent Protection Management | Cybersecurity | $33 | $29 | $35 | 48% | 0.79 | n/a |
| VerifyMe | Brand Protection | $19 | $13 | $16 | 47% | 0.84 | n/a |
| CISO Global | Cybersecurity | $16 | $22 | $35 | 27% | 0.61 | n/a |
| AuthID | Identity Verification | $10 | $13 | $2 | n/a | 7.33 | n/a |
| Secur3D Holdings | Digital Asset Protection | $9 | $9 | n/a | n/a | 0.74 | 2.10 |
| Cyabra | AI / Social Intelligence | $7 | $9 | $10 | 85% | 0.76 | n/a |
| Average | 3.15 | 11.20 | |||||
| SECUR3D (Discount) | -77% | -81% | |||||
| SECUR3D (Fair Value @ Average Metrics) | $0.57 | $0.70 |
We are initiating coverage with a BUY rating, and a fair value estimate of $0.64/share, based on the average of our three valuation methodologies. The company is addressing a growing digital IP protection market, with a differentiated focus on 3D digital assets, and proactive infringement detection. With 14 customer and partner relationships established, we see potential for growth as the company converts early relationships into recurring revenue, and expands its customer base. However, competition is intense, making rapid market share gains through differentiation critical.
We believe the company is exposed to the following key risks (not exhaustive):
We are assigning a risk rating of 4 (Speculative).
Sid Rajeev, B.Tech, MBA, CFA — Head of Research, Fundamental Research Corp.
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Disclosures. Fees ranging between $30,000 and $40,000 will be paid to FRC by SECUR3D to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. The analyst and Fundamental Research Corp. “FRC” do not own any shares of the subject company, do not make a market or offer shares for sale of the subject company, and do not have any investment banking business with the subject company. Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE. Buy – Fair value is 12% above the current market price; or risk and reward is favorable. 4 (Speculative) - The company has little or no history of generating earnings or cash flow. Debt use is higher. These companies may be in start-up mode or in a turnaround situation. These companies should be considered speculative. The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (22%). ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST.
Protecting Digital Assets in the AI Era
Paused · 16:13 left · FRC · read by an AI voice



Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.