
We reiterate our BUY rating, and adjust our fair value estimate from $0.47 to $0.33/share, reflecting a more conservative valuation approach, rather than any deterioration in our outlook. In fact, our confidence in the exploration potential at Gold Run has increased since our previous report, supported by encouraging drilling results across all four tested prospects.
Maiden Drilling Points to a Larger Exploration Opportunity
Paused · 13:56 left · FRC · read by an AI voice
Disclosure: Lodestar Metals Corp. has paid FRC a fee for research coverage and distribution of reports. This fee creates a potential conflict of interest which readers should consider. See last page for other important disclosures, rating, and risk definitions.
All figures in C$.
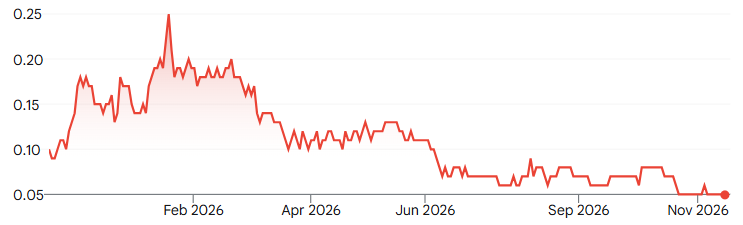
Price and Volume (1-year)
| YTD | 12M | |
|---|---|---|
| LSTR | -64% | -50% |
| TSXV | -20% | -9% |
| Gold | -11% | -8% |
| GOEX* | -11% | 0% |
| Key Financial Data (FYE - Dec 31) | 2026 (6M) | Current Cash |
|---|---|---|
| Cash | $1,396,092 | ~$800,000 |
| Working Capital | $1,401,668 | |
| Mineral Assets/PP&E | $1,202,577 | |
| Total Assets | $2,704,440 | |
| Net Income (Loss) | -$891,027 | |
| EPS | -$0.02 |
LSTR has two projects: gold-silver in Nevada (flagship), and lithium-polymetallic in Manitoba.
| Project | Location | Target Commodities |
|---|---|---|
| Gold Run | Nevada, U.S. | Gold, Silver |
| Peny | Manitoba, Canada | Lithium, Cesium, Tantalum, Copper, Zinc, Silver |
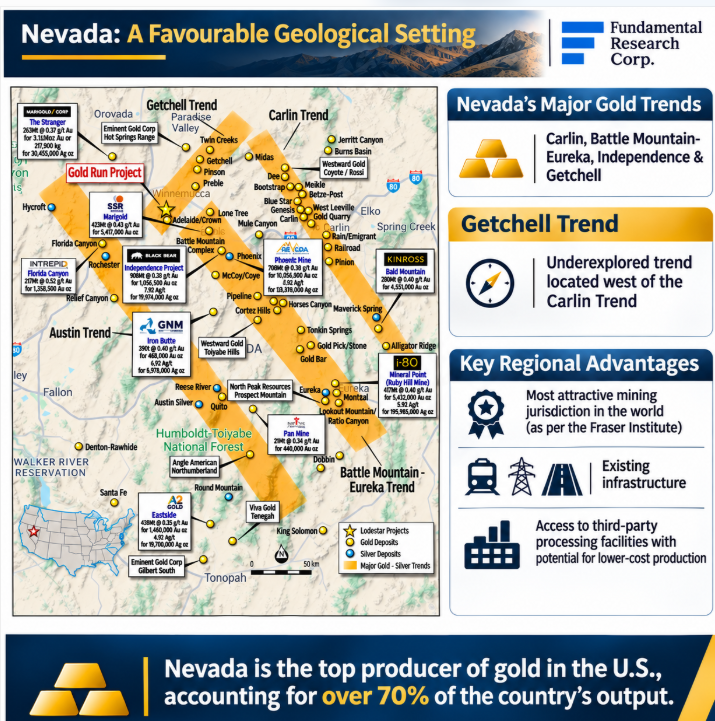
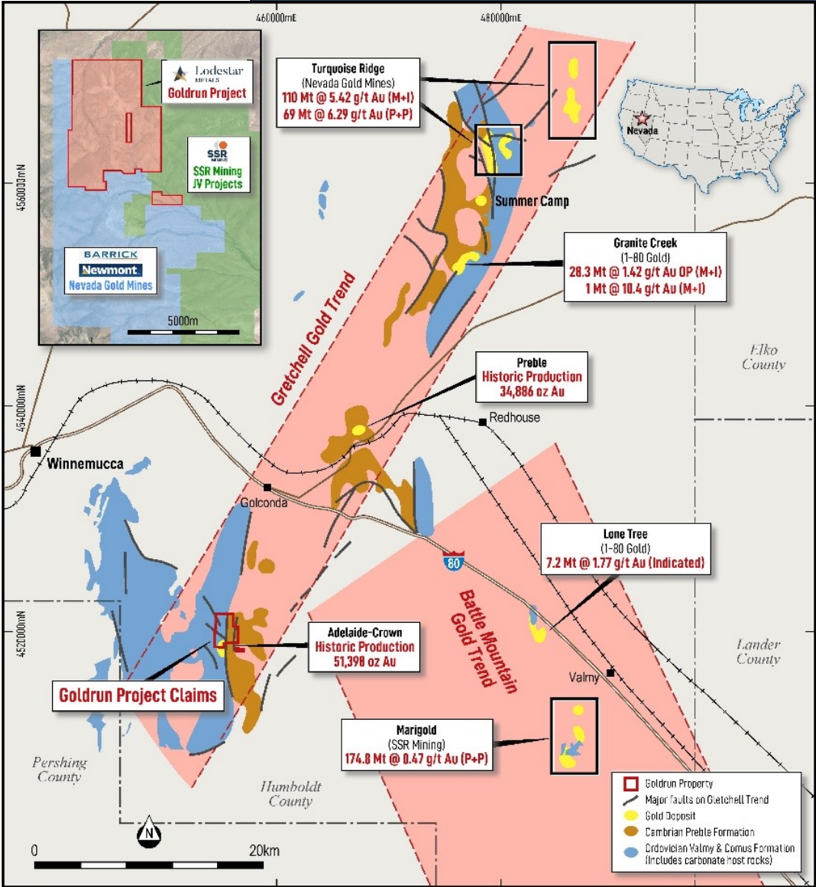
Nevada is the largest gold producing state in the U.S. Gold Run is situated on Nevada’s Getchell trend, immediately west of the prolific Carlin trend, which has produced hundreds of millions of ounces of gold, underscoring the property's exceptional regional mineral potential. The Getchell trend is a 60 km-long gold belt, with potential for high-grade, large-scale deposits.
This report primarily focuses on recent results from a maiden drill program at Gold Run.
Gold Run is located near major mining companies, including Barrick/Newmont and SSR Mining. Proximity to established mining operations adds strategic value, as successful exploration could make Gold Run an attractive acquisition target.
Near Major Gold Mines: Located 40 km south of Nevada Gold Mines’ Turquoise Ridge operation (~0.5 Moz annual production; ~15 Moz in reserves) and 30 km from SSR Mining’s Marigold mine (~5 Moz in reserves).
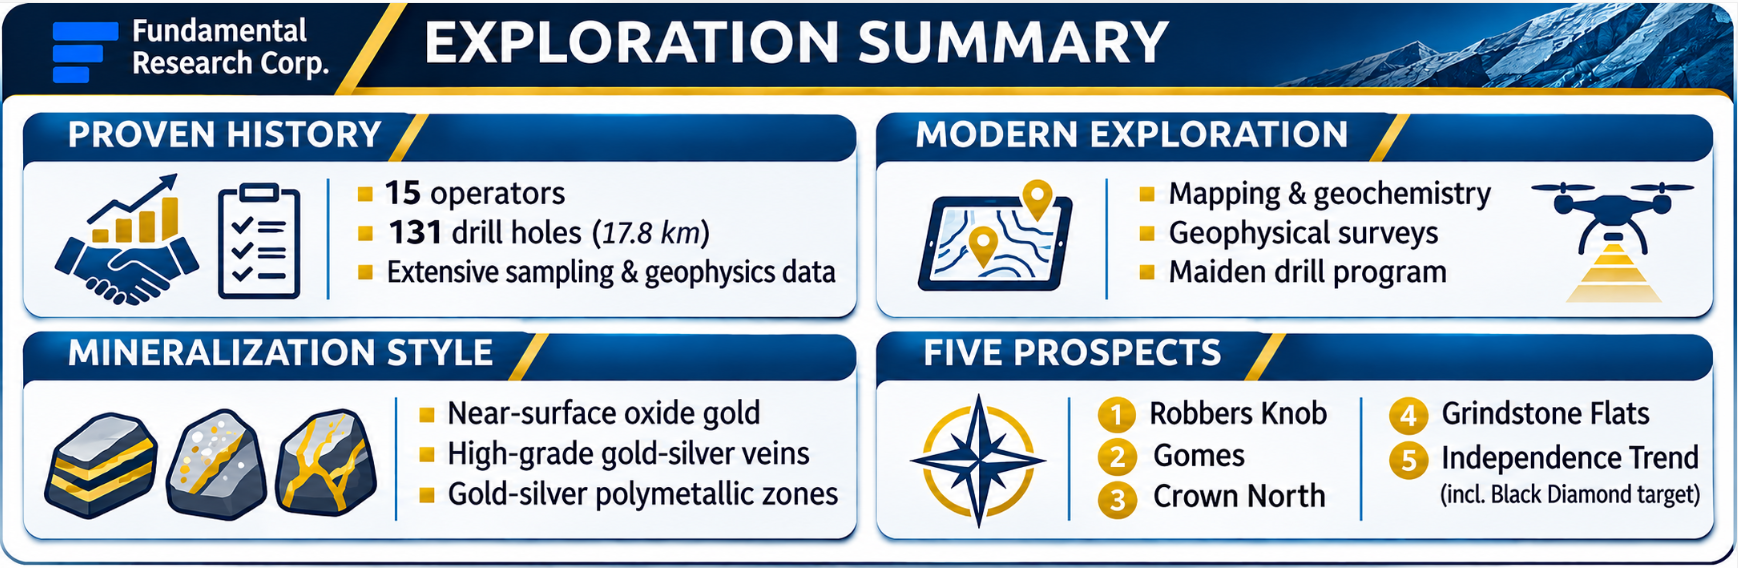
Existing Infrastructure: Roads, power, water, and third-party processing facilities, supporting offsite processing, and potentially lower development costs. Multiple Exploration Targets: Robbers Knob, Gomes, Crown North, Grindstone Flats, and Independence Trend (Black Diamond).
Last year, LSTR completed a comprehensive exploration program, including detailed mapping, encouraging soil sampling results, and magnetic and IP geophysical surveys.
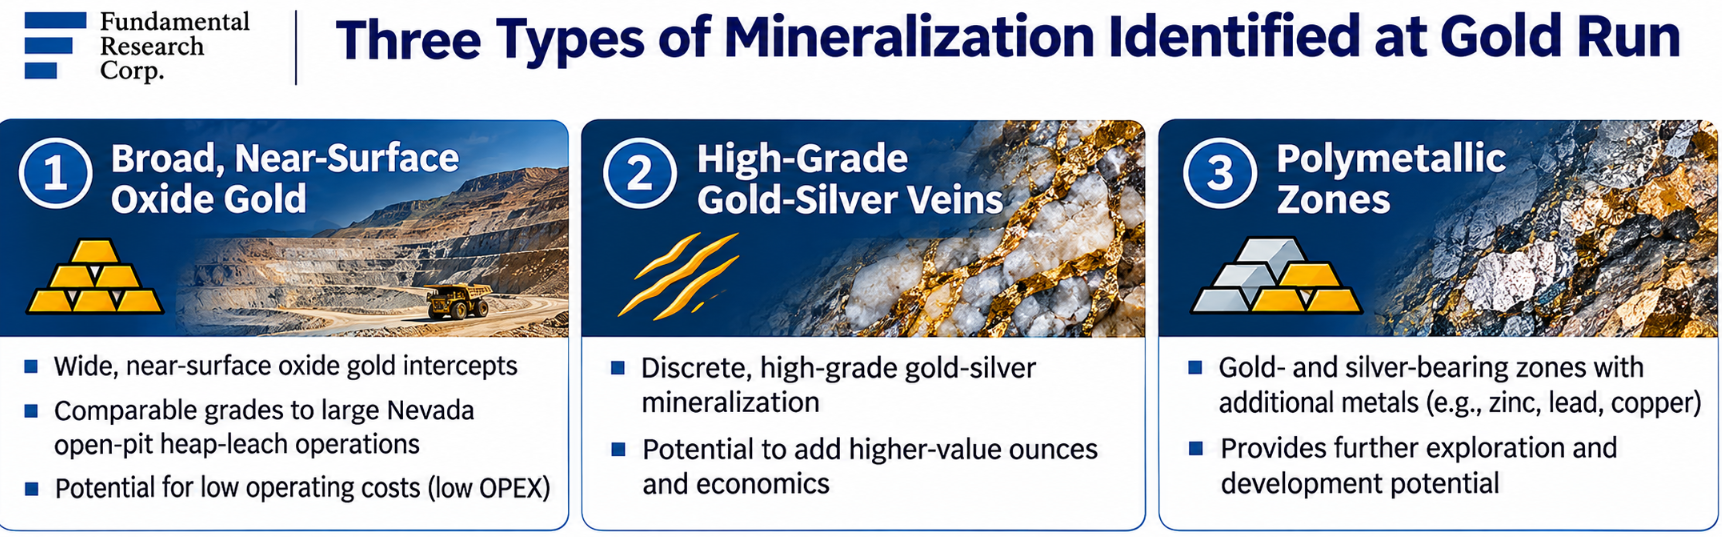
Exploration has identified three distinct mineralization styles, offering multiple potential development pathways, and reducing reliance on a single deposit type.
The company recently completed a maiden drill program (18 holes; 2,860 m), testing four prospects: Robbers Knob, Gomes, Crown North, and the Black Diamond target in the northern Independence Trend.
The drill results are promising.
2026 Drill Program
| Robbers Knob | Gomes | Crown North | Independence Trend (Black Diamond target) | Grindstone Flats |
|---|---|---|---|---|
| 6 holes / 1,143 m | 2 holes / 463 m | 2 holes / 312 m | 8 holes / 902 m | N/A |
Drilling was guided by historical data, soil sampling, magnetic surveys, and IP surveys, targeting both historical mineralization, and new opportunities for bulk-tonnage (large-scale, lower-grade), and high-grade gold-silver deposits. We were encouraged by the drill results, which reinforces our confidence in Gold Run’s exploration potential, and warrants further work to assess the scale, and continuity of mineralization.
We believe the results point to multiple opportunities for large-scale, and high-grade gold-silver discoveries.
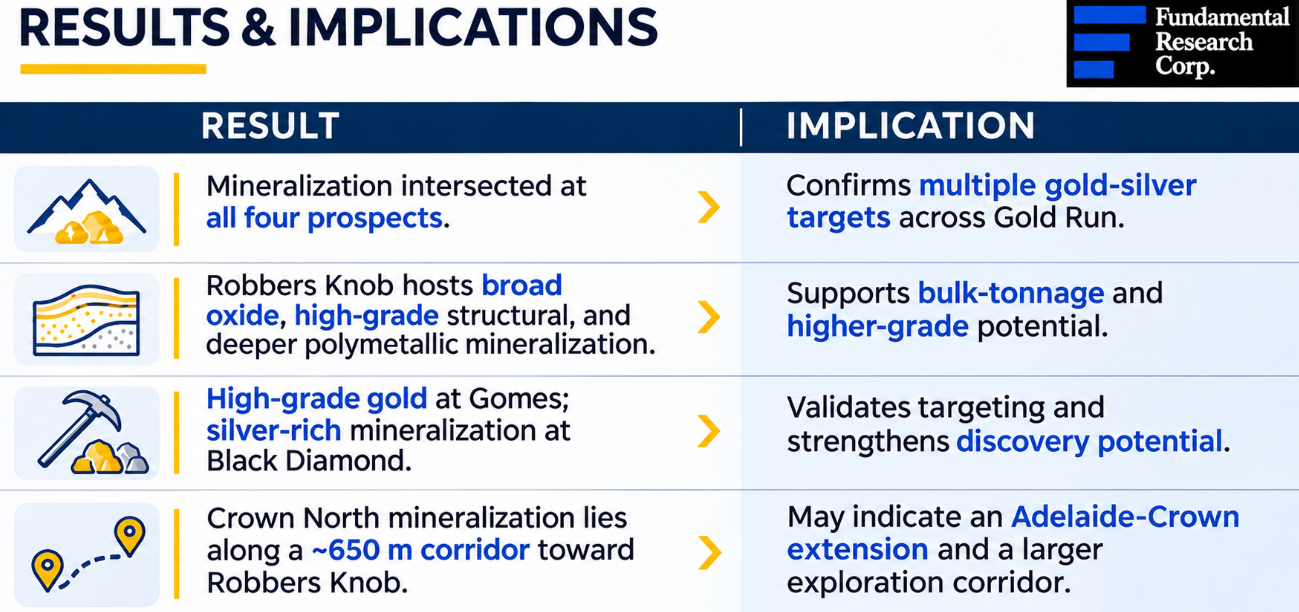
| RESULT | IMPLICATION |
|---|---|
| Mineralization intersected at all four prospects. | Confirms multiple gold-silver targets across Gold Run. |
| Robbers Knob hosts broad oxide, high-grade structural, and deeper polymetallic mineralization. | Supports bulk-tonnage and higher-grade potential. |
| High-grade gold at Gomes; silver-rich mineralization at Black Diamond. | Validates targeting and strengthens discovery potential. |
| Crown North mineralization lies along a ~650 m corridor toward Robbers Knob. | May indicate an Adelaide-Crown extension and a larger exploration corridor. |
Adelaide-Crown Analogy: Adelaide-Crown is a historically mined deposit owned by Barrick/Newmont. Gomes, Crown North, and Independence show similar mineralization, and potential extensions of the Adelaide-Crown system. The Crown pit sits just 50 m south of the Gold Run property boundary.
Key Drill Results
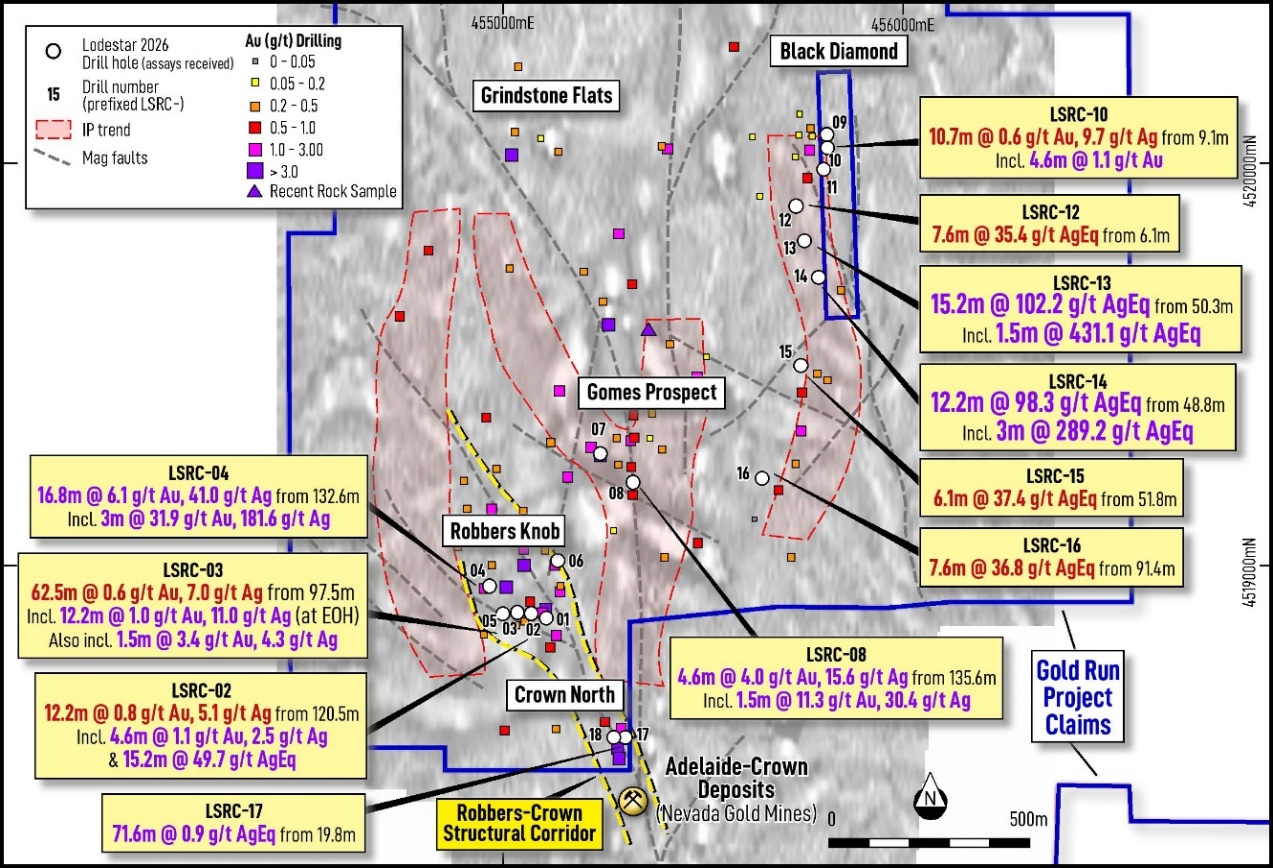
Grades across the four prospects range from 0.5–2.0 g/t gold, compared with typical Nevada grades of 0.5–1.0 g/t, with select intervals returning significantly higher grades.
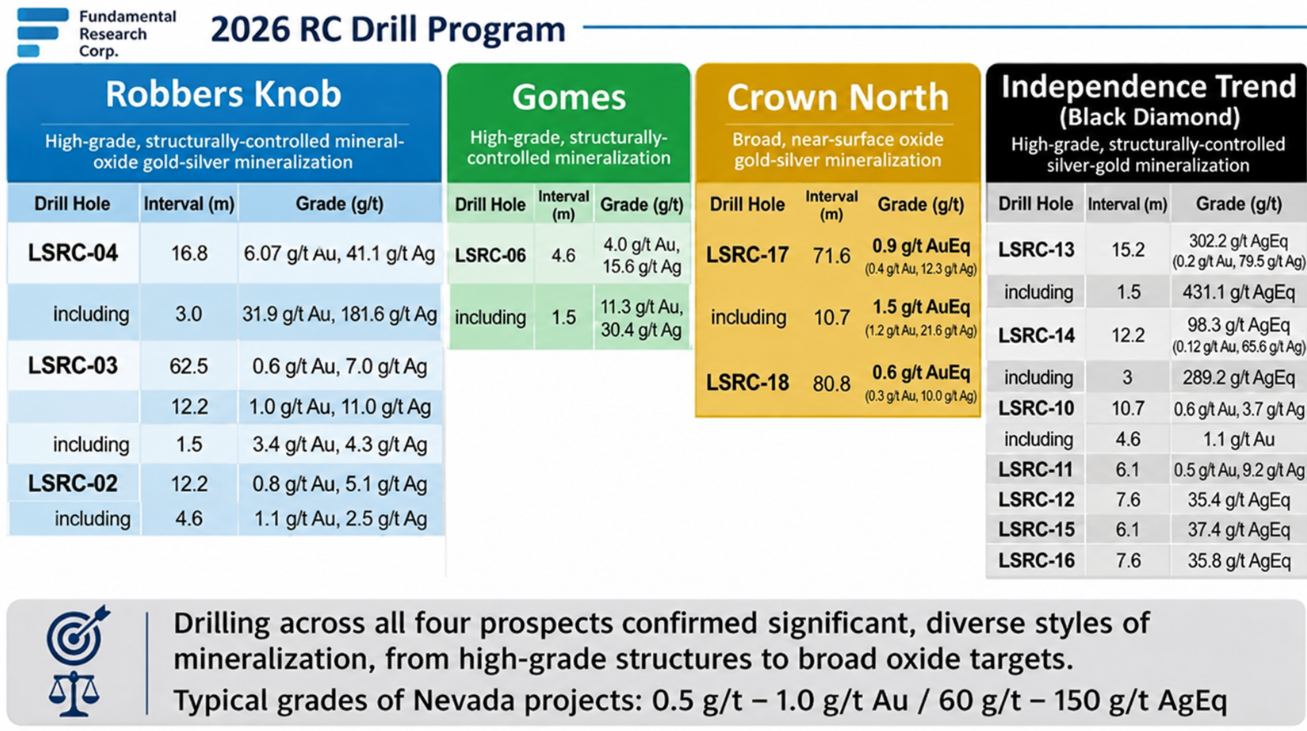
| Robbers Knob — High-grade, structurally-controlled mineral-oxide gold-silver mineralization | ||
|---|---|---|
| Drill Hole | Interval (m) | Grade (g/t) |
| LSRC-04 | 16.8 | 6.07 g/t Au, 41.1 g/t Ag |
| including | 3.0 | 31.9 g/t Au, 181.6 g/t Ag |
| LSRC-03 | 62.5 | 0.6 g/t Au, 7.0 g/t Ag |
| 12.2 | 1.0 g/t Au, 11.0 g/t Ag | |
| including | 1.5 | 3.4 g/t Au, 4.3 g/t Ag |
| LSRC-02 | 12.2 | 0.8 g/t Au, 5.1 g/t Ag |
| including | 4.6 | 1.1 g/t Au, 2.5 g/t Ag |
| Gomes — High-grade, structurally-controlled mineralization | ||
|---|---|---|
| Drill Hole | Interval (m) | Grade (g/t) |
| LSRC-06 | 4.6 | 4.0 g/t Au, 15.6 g/t Ag |
| including | 1.5 | 11.3 g/t Au, 30.4 g/t Ag |
| Crown North — Broad, near-surface oxide gold-silver mineralization | ||
|---|---|---|
| Drill Hole | Interval (m) | Grade (g/t) |
| LSRC-17 | 71.6 | 0.9 g/t AuEq (0.4 g/t Au, 12.3 g/t Ag) |
| including | 10.7 | 1.5 g/t AuEq (1.2 g/t Au, 21.6 g/t Ag) |
| LSRC-18 | 80.8 | 0.6 g/t AuEq (0.3 g/t Au, 10.0 g/t Ag) |
| Independence Trend (Black Diamond) — High-grade, structurally-controlled silver-gold mineralization | ||
|---|---|---|
| Drill Hole | Interval (m) | Grade (g/t) |
| LSRC-13 | 15.2 | 302.2 g/t AgEq (0.2 g/t Au, 79.5 g/t Ag) |
| including | 1.5 | 431.1 g/t AgEq |
| LSRC-14 | 12.2 | 98.3 g/t AgEq (0.12 g/t Au, 65.6 g/t Ag) |
| including | 3 | 289.2 g/t AgEq |
| LSRC-10 | 10.7 | 0.6 g/t Au, 3.7 g/t Ag |
| including | 4.6 | 1.1 g/t Au |
| LSRC-11 | 6.1 | 0.5 g/t Au, 9.2 g/t Ag |
| LSRC-12 | 7.6 | 35.4 g/t AgEq |
| LSRC-15 | 6.1 | 37.4 g/t AgEq |
| LSRC-16 | 7.6 | 35.8 g/t AgEq |
LSTR is integrating exploration results into a 3D geological model, with follow-up drilling planned at Robbers Knob and Crown North in 2027. Multiple targets provide several opportunities for discovery.
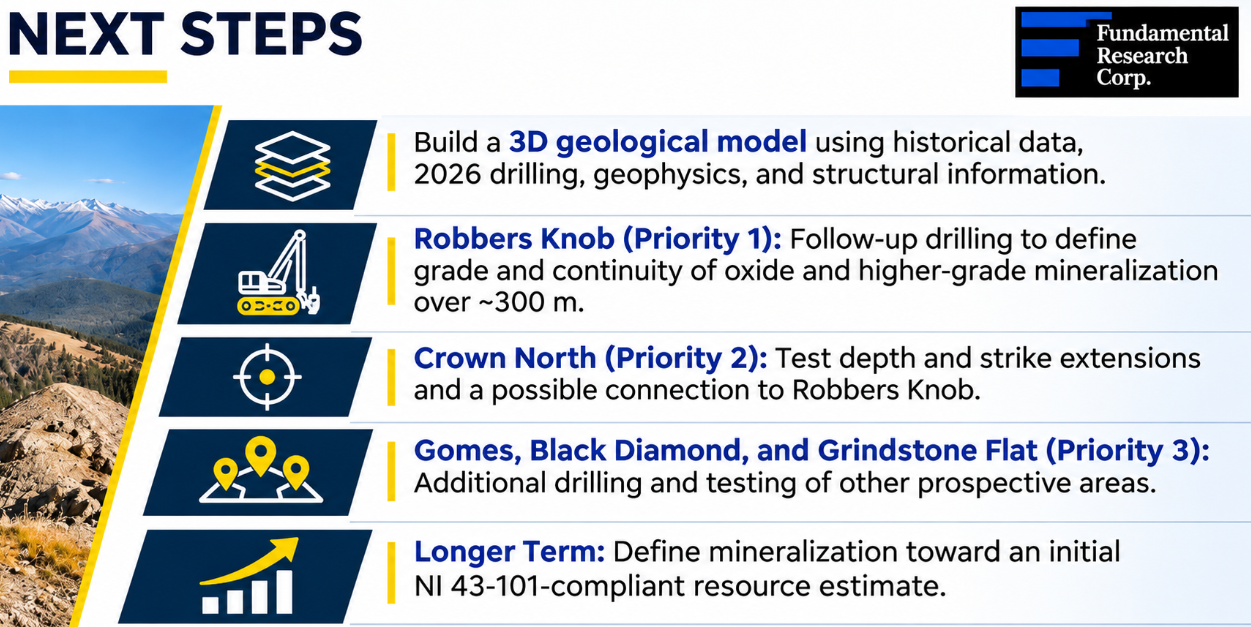
Management aims to systematically test all primary targets, assess the potential to expand mineralization, and ultimately establish an independent (NI 43-101-compliant) resource estimate. Based on historical results, favourable regional geology, and the property's underexplored nature, management is targeting a multi-million-ounce gold potential; a reasonable objective in our view, although substantial drilling will be required given the project's early stage. A key advantage is the presence of multiple prospects, offering several opportunities for discoveries.
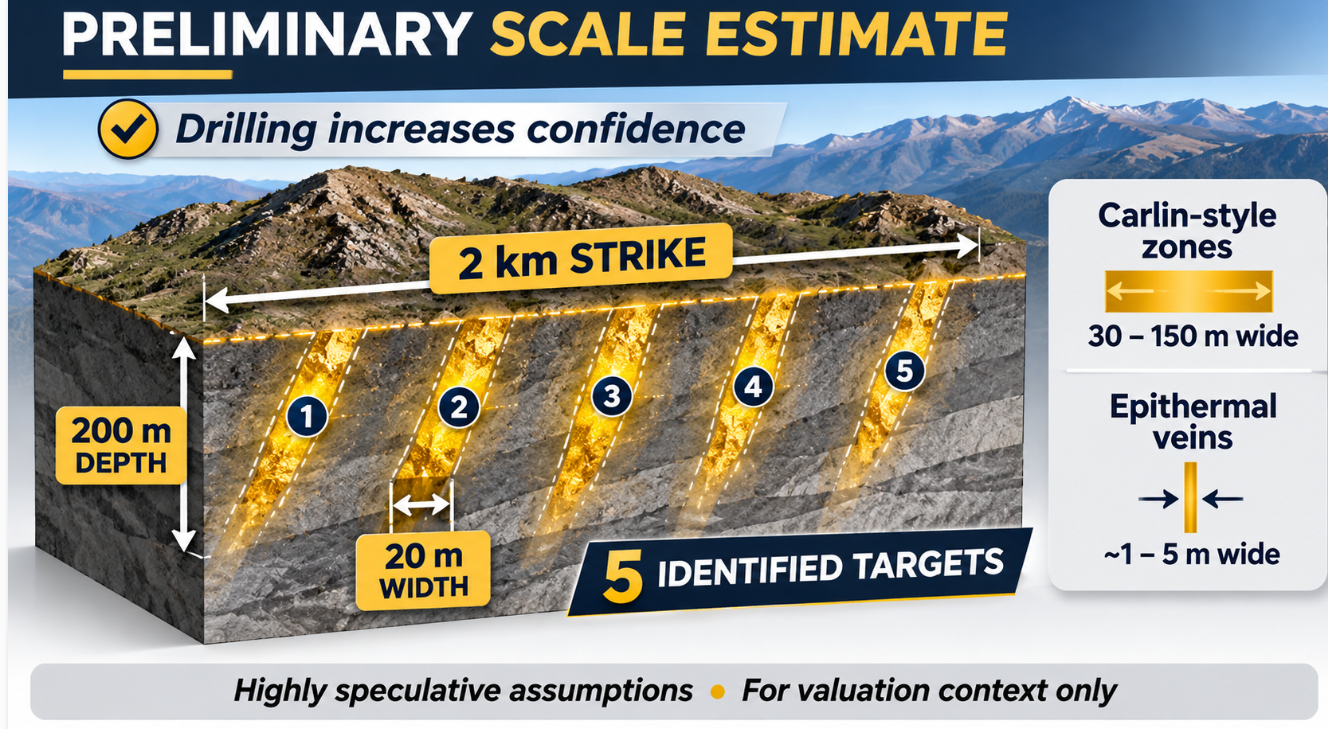
The latest drill results have increased our confidence in the project's potential. For valuation purposes, we retain assumptions of a 2 km strike length across five identified targets, 200 m depth, and 20 m width. For context, large-scale gold deposits in Nevada can feature mineralized zones 30–150 m wide, while narrower gold-silver veins typically range from 1–5 m. These assumptions remain highly speculative, but provide a preliminary basis for estimating potential scale, and benchmarking it against comparable gold projects.
Based on drilling results, regional geology, and comparable deposits, we believe projects hosting ~0.5 Moz of gold represent the most relevant peer group for valuation purposes.
| FRC Speculative Estimates | |
|---|---|
| Length (m) | 2,000 |
| Width (m) | 20 |
| Depth (m) | 200 |
| Specific Gravity | 2.6 |
| Tonnes (dilution: 50%) | 10,400,000 |
| Grade (gpt) | 1.5 |
| Contained Gold (oz) | 499,200 |
This approach remains consistent with our previous report, although recent drilling has increased our confidence in the project's potential. Note that this valuation methodology is highly speculative and preliminary, reflects our own independent analysis, and has not been endorsed or approved by the company.
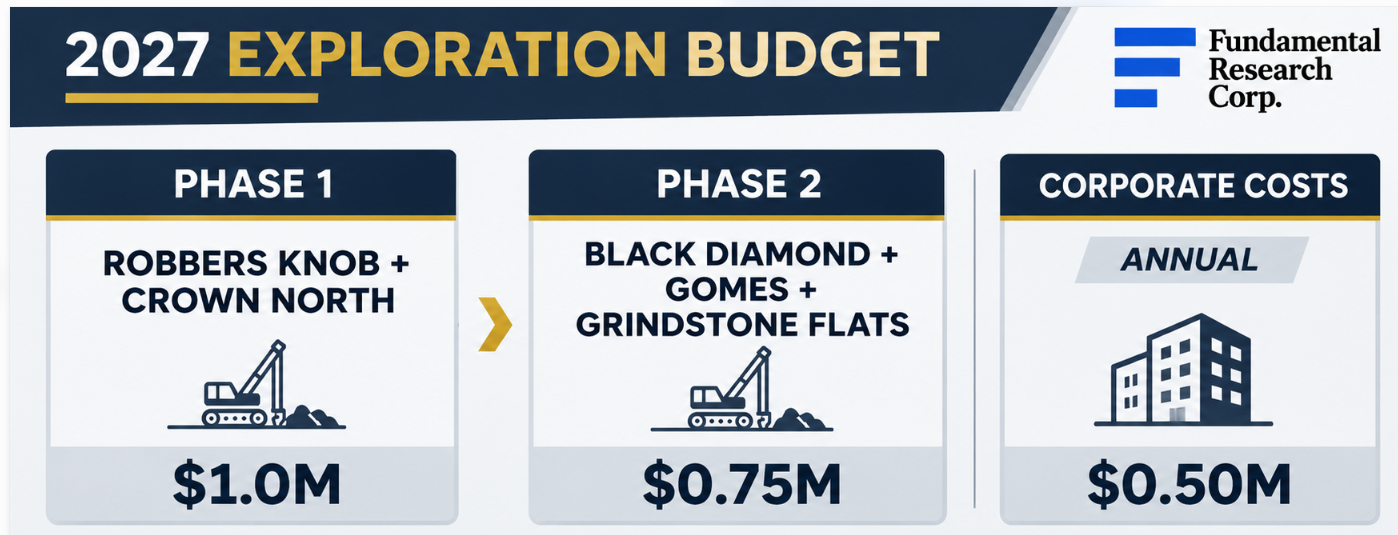
We estimate LSTR will need to raise ~$1.5M over the next six months.
| (in C$) (FYE - Dec 31) | 2026 (6M) | Current Cash |
|---|---|---|
| Cash | $1,396,092 | ~$800,000 |
| Working Capital | $1,401,668 | |
| Current Ratio | 14.99 | |
| Debt | - | |
| Monthly Burn Rate (G&A) | -$89,061 | |
| Cash Spent on Properties | -$869,995 | |
| Cash from Financing Activities | $1,493,134 |
The 2027 budget is $2.25M.
None of the options or warrants outstanding are in-the-money.
| Options | # | Exercise Price (C$) | Amount |
|---|---|---|---|
| Total | 5,151,825 | $0.09 | $475,100 |
| In-the-Money | - | - | - |
| Warrants | # | Exercise Price (C$) | Amount |
|---|---|---|---|
| Total | 18,347,569 | $0.20 | $3,632,524 |
| In-the-Money | - | - | - |
LSTR is trading at just $7/oz based on our preliminary estimate on Gold Run, compared with a comparables average of $65/oz, an 89% discount. All companies selected in the study are Nevada-focused gold juniors. Overall, LSTR is the most undervalued gold junior on the list.
| Gold Juniors | Enterprise Value ($,M) | EV / Resource* | |
|---|---|---|---|
| 1 | i-80 Gold | $2,016 | $171.61 |
| 2 | Scorpio Gold Corp | $76 | $145.60 |
| 3 | NV Gold | $36 | $144.00 |
| 4 | P2 Gold | $314 | $136.23 |
| 5 | West Vault Mining | $92 | $92.09 |
| 6 | Viva Gold | $37 | $65.47 |
| 7 | Lahontan Gold | $88 | $50.44 |
| 8 | A2 Gold | $36 | $48.39 |
| 9 | Nevada King Gold | $40 | $35.73 |
| 10 | Getchell Gold | $46 | $31.02 |
| 11 | Western Exploration | $29 | $29.44 |
| 12 | Bravada Gold | $16 | $21.53 |
| 13 | Lodestar Metals | $2 | $7.13 |
| Average (excl outliers) | $65.43 |
| Gold Run - 50% of FRC's Preliminary Speculative Estimate (oz) | 249,600 |
|---|---|
| Average EV/ Resource Ratio (comparables) | $65.43 |
| Fair Value of Gold Run | $16,332,241 |
| Working Capital net of Debt | $800,000 |
| Fair Value of LSTR | $17,132,241 |
| No. of Shares (treasury stock method) | 51,518,248 |
| Fair Value per Share (C$) | $0.33 |
For this study, we have applied 100% of measured and indicated resources (higher-confidence categories) and 50% of inferred resources (lower-confidence category). For Gold Run, we have applied a 50% discount to our preliminary estimate, reflecting highly conservative assumptions. While our confidence in the project has increased, we previously used 100% of our estimate for valuation purposes, which we now believe was aggressive. We have therefore taken a more conservative approach.
Relevant Nevada Precedent: SSR Mining is acquiring Roxmore Resources, owner of the Converse project, which hosts a 5.2 Moz gold resource averaging 0.51 g/t, for an enterprise value of $549M, or $149/oz (based on 100% of M&I, and 50% of inferred resources). Located ~25 km from Gold Run, we believe the transaction highlights strategic interest in Nevada's large-scale, low-grade gold assets. By comparison, our valuation assumption of $65/oz for comparables is relatively more conservative.
We reiterate our BUY rating, and adjust our fair value estimate from $0.47 to $0.33/share, reflecting a more conservative valuation approach, rather than any deterioration in our outlook. In fact, our confidence in the exploration potential at Gold Run has increased since our previous report, supported by encouraging drilling results across all four tested prospects. We believe the current valuation provides significant upside potential, subject to successful exploration, and greater clarity on the scale of mineralisation.
We are maintaining our risk rating of 5 (Highly Speculative). We believe the company is exposed to the following key risks (not exhaustive):
Sid Rajeev, B.Tech, MBA, CFA — Head of Research, Fundamental Research Corp.
Nina Rose Coderis, B.Sc (Geology) — Equity Analyst, Fundamental Research Corp.
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Buy – Fair value is 12% above the current market price; or risk and reward is favorable
Hold – Fair value is between 5% to 12% above the current market price
Sell – Fair value is 5% above, or less, than the current market value; or risk and reward is unfavorable
Suspended or Rating N/A— Coverage and ratings suspended until more information can be obtained from the company regarding recent events.
1 (Low Risk) - The company operates in an industry where it has a strong position (for example a monopoly, high market share etc.) or operates in a regulated industry. The future outlook is stable or positive for the industry. The company generates positive free cash flow and has a history of profitability. The capital structure is conservative with little or no debt.
2 (Below Average Risk) - The company operates in an industry where the fundamentals and outlook are positive. The industry and company are relatively less sensitive to systematic risk than companies with a Risk Rating of 3. The company has a history of profitability and has demonstrated its ability to generate positive free cash flows (though current free cash flow may be negative due to capital investment). The company’s capital structure is conservative with little to modest use of debt.
3 (Average Risk) - The company operates in an industry that has average sensitivity to systematic risk. The industry may be cyclical. Profits and cash flow are sensitive to economic factors although the company has demonstrated its ability to generate positive earnings and cash flow. Debt use is in line with industry averages, and coverage ratios are sufficient.
4 (Speculative) - The company has little or no history of generating earnings or cash flow. Debt use is higher. These companies may be in start-up mode or in a turnaround situation. These companies should be considered speculative.
5 (Highly Speculative) - The company has no history of generating earnings or cash flow. They may operate in a new industry with new, and unproven products. Products may be at the development stage, testing, or seeking regulatory approval. These companies may run into liquidity issues and may rely on external funding. These stocks are considered highly speculative.
Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE.
Analyst Certification: The views expressed in this report accurately reflect the personal views of the analyst, and no part of their compensation was, is, or will be directly or indirectly related to the specific recommendation or views expressed.
Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The analyst and Fundamental Research Corp. “FRC” does not own any shares of the subject company, does not make a market or offer shares for sale of the subject company, and does not have any investment banking business with the subject company. Fees ranging between $20,000 and $30,000 have been paid to FRC by Lodestar Metals to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. FRC takes steps to mitigate conflicts including setting fees in advance and utilizing analysts who must abide by CFA Institute Code of Ethics and Standards of Professional Conduct. Additionally, analysts may not trade in any security under coverage. Our full editorial control of all research, timing of release of the reports, and release of liability for negative reports are protected contractually. The issuer has agreed to a minimum coverage term and coverage cannot be unilaterally terminated. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time.
The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (28%).
Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The analyst and Fundamental Research Corp. “FRC” does not own any shares of the subject company, does not make a market or offer shares for sale of the subject company, and does not have any investment banking business with the subject company. Fees ranging between $20,000 and $30,000 have been paid to FRC by Lodestar Metals Corp. to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. FRC takes steps to mitigate conflicts including setting fees in advance and utilizing analysts who must abide by CFA Institute Code of Ethics and Standards of Professional Conduct. Additionally, analysts may not trade in any security under coverage. Our full editorial control of all research, timing of release of the reports, and release of liability for negative reports are protected contractually. The issuer has agreed to a minimum coverage term and coverage cannot be unilaterally terminated. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time.
Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
👏
Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.