
We reiterate our BUY rating, and adjust our fair value estimate from $1.54 to $1.41/share (the average of our DCF and comparables valuations). Despite the downward revision, we believe significant production growth potential, strong liquidity, and a 100% drilling success rate remain underappreciated, with shares trading at a 71% discount to peers across key metrics. With two new wells online, 17 additional drilling locations, and a potential NYSE American ADR listing, we believe the company offers compelling exposure to near-term production growth, and valuation upside potential.
Disclosure: Brookside Energy Limited has paid FRC a fee for research coverage and distribution of reports. This fee creates a potential conflict of interest which readers should consider. See last page for other important disclosures, rating, and risk definitions.
All figures in A$ except commodity prices, which are in US$.
Price and Volume (1-year)
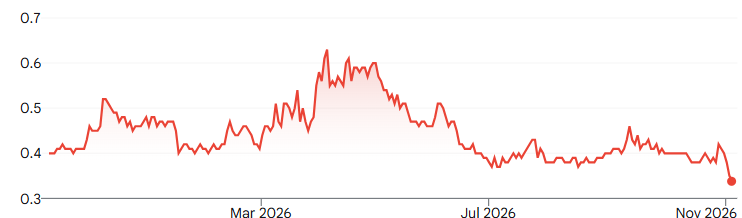
| YTD | 12M | |
|---|---|---|
| BRK | -29% | -15% |
| ASX | 3% | 1% |
| Sector* | 35% | 39% |
| YE: Dec 31st (A$) | 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|---|---|---|
| Production (boepd) | 244 | 908 | 1,397 | 1,440 | 1,814 | 1,388 | 2,157 |
| Revenue | $12,580,636 | $52,996,833 | $51,436,980 | $46,902,292 | $53,789,020 | $47,117,457 | $66,170,636 |
| EBITDA | -$1,125,147 | $22,421,635 | $26,883,601 | $17,713,681 | $18,129,381 | $13,851,233 | $23,065,742 |
| Net Income | -$2,611,336 | $15,096,105 | $16,647,566 | $2,832,406 | $2,731,257 | -$1,426,220 | $5,714,163 |
| EPS | -$0.10 | $0.35 | $0.17 | $0.03 | $0.03 | -$0.02 | $0.06 |
| Debt | - | - | - | - | - | - | - |
| Assets | $40,762,129 | $93,761,401 | $95,117,173 | $127,686,807 | $114,084,202 | $111,998,152 | $117,712,315 |
* Brookside Energy has paid FRC a fee for research coverage and distribution of reports. See last page for other important disclosures, rating, and risk definitions. All figures in A$ except commodity prices, which are in US$.
BRK operates in the Anadarko Basin, a mature oil and gas region revitalized by horizontal drilling, and fracking. The basin is estimated to host tens of billions of boe in recoverable resources, supporting decades of future drilling potential (American Association of Petroleum Geologists). BRK operates 11 producing wells (PDP), and has 17 proved undeveloped locations (PUDs/planned for future development), across 5,000+ acres.
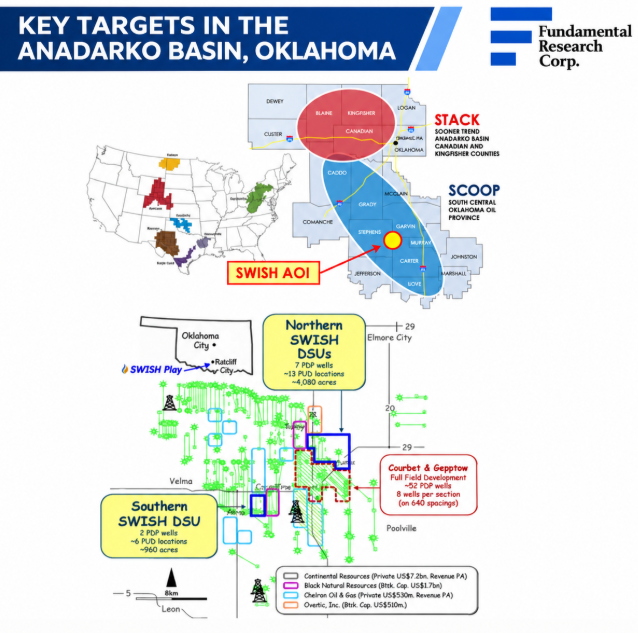
BRK has a 100% success rate, with all 11 wells successfully drilled on the first attempt.
FY2025 Net Reserve Estimates (As at 31 December 2025)
| Reserve Class | Oil (bbl) | NGL (bbl) | Gas (Mcf) | BOE |
|---|---|---|---|---|
| Proved Developed Producing | 596,421 | 852,230 | 8,091,402 | 2,797,218 |
| Proved Developed Non-Producing | 7,815 | - | 18,300 | 10,865 |
| Proved Undeveloped | 746,065 | 735,989 | 6,245,853 | 2,523,030 |
| Total Proved | 1,350,301 | 1,588,219 | 14,355,555 | 5,331,113 |
| Probable Undeveloped | 1,819,500 | 2,319,235 | 18,323,264 | 7,192,612 |
| Grand Total | 3,169,801 | 3,907,454 | 32,678,819 | 12,523,725 |
Existing wells have an expected productive life of ~20 years.
| Reserves (mmboe) | 2022 | 2023 | 2024 | 2025 | YoY |
|---|---|---|---|---|---|
| Proved Developed Producing (PDP) | 1.07 | 1.77 | 2.65 | 2.80 | 6% |
| Proved Developed Non-Producing | 0.49 | 0.01 | 0.01 | 0.01 | 0% |
| Proved Undeveloped | 2.14 | 2.31 | 2.32 | 2.52 | 9% |
| Total Proved | 3.70 | 4.09 | 4.98 | 5.33 | 7% |
| Probable Undeveloped | 8.17 | 7.47 | 7.37 | 7.19 | -2% |
| Total Proved + Probable | 11.87 | 11.56 | 12.35 | 12.52 | 1% |
Production declined 11% QoQ in Q3 to 1,290 boepd, 7% below our estimate, due to natural declines, and no new wells. In addition, revenue fell 27% QoQ, 5% below our estimate, reflecting lower oil prices, and production.
Production Data and Key Metrics
| Production | Q1-2025 | Q2-2025 | Q3-2025 | Q4-2025 | Q1-2026 | Q2-2026 | Q3-2026 | QoQ | YoY |
|---|---|---|---|---|---|---|---|---|---|
| Gross Production (boe) | 273,838 | 249,871 | 270,780 | 250,753 | 216,419 | 216,196 | 192,918 | -11% | -29% |
| Net Production (boe) | 172,762 | 158,792 | 167,377 | 154,228 | 131,996 | 127,732 | 114,000 | -11% | -32% |
| - per day | 1,920 | 1,847 | 1,828 | 1,701 | 1,495 | 1,404 | 1,290 | -8% | -29% |
| - production mix (% of liquids) | 56% | 56% | 55% | 55% | 52% | 58% | 55% | -5% | 0% |
| Net Sales Volume (boe) | 171,079 | 137,732 | 163,779 | 150,385 | 138,985 | 124,565 | 116,143 | -7% | -29% |
| Operating Summary | Q1-2025 | Q2-2025 | Q3-2025 | Q4-2025 | Q1-2026 | Q2-2026 | Q3-2026 | QoQ | YoY |
|---|---|---|---|---|---|---|---|---|---|
| Blended Realised Price (US$/boe) | $40 | $37 | $35 | $31 | $31 | $43 | $34 | -21% | -4% |
| Revenue Attributable to Sales (US$) | n/a | n/a | n/a | n/a | $4,287,000 | $5,318,000 | $3,907,000 | -27% | n/a |
| Cash Receipts from Customers (A$) | $18,141,000 | $14,420,000 | $13,881,000 | $12,035,379 | $10,252,000 | $9,795,000 | $8,333,000 | -15% | -40% |
| Net Operating Cash Flow (A$) | $4,554,000 | $6,538,000 | $6,360,000 | $4,130,465 | $3,477,000 | $933,000 | $2,026,000 | 117% | -68% |
We expect a strong Q4 rebound, as the two newly completed wells ramp up production. BRK ended Q3 with $6M in cash, and an undrawn $35M credit facility, providing $41M in available liquidity.
| Liquidity and Capital Structure (A$) YE December 31 |
2025 | Q1-2026 | Q2-2026 | Q3-2026 | Sector |
|---|---|---|---|---|---|
| Cash | $11,855,293 | $14,535,000 | $14,522,000 | $5,898,000 | |
| Working Capital | -$4,682,781 | ||||
| Current Ratio | 0.78 | 0.90 | |||
| LT Debt | $0 | ||||
| Total Debt | $0 | ||||
| Total Debt / Capital | 0% | 46% |
Two new wells commence production, with production growth potential.
The company is advancing the first two of 19 proved undeveloped drilling locations identified in its December 2025 reserve report. Both wells have completed stimulation, and commenced initial sales, increasing BRK’s producing well count to 11. Initial production rates are expected shortly. Based on regional well performance, we estimate initial production could reach 750 – 1,000 boepd (net).
BRK has expanded its development program, securing 1%–12% working interests in five proposed horizontal wells in the region. Total investment is estimated at ~$3.5M. The wells are not yet producing, and will be developed by third-party operators. If successfully developed, we estimate they could add ~50–120 boe/d of net production, providing growth with limited capital, and operating responsibilities.
Since our last report, consensus oil price forecasts are up 3%.
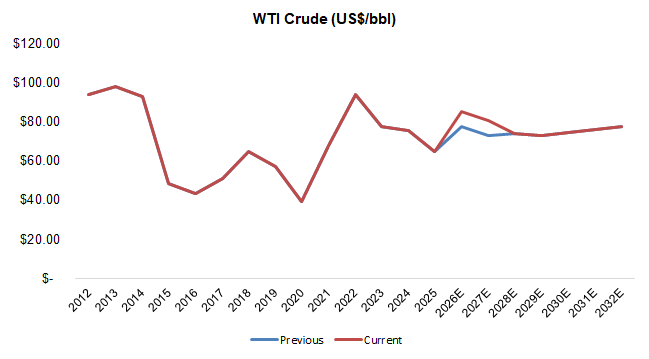
We lowered our 2026 and 2027 revenue and EPS estimates, reflecting lower than expected Q3 production, partially offset by higher oil price forecasts.
| 2026E (Old) | 2026E (New) | 2027E (Old) | 2027E (New) | |
|---|---|---|---|---|
| WTI Crude (US$/bbl) | $77.78 | $85.44 | $73.17 | $80.67 |
| Net Production (boe) | 578,924 | 506,628 | 877,933 | 787,309 |
| Daily Production (boepd) | 1,586 | 1,388 | 2,405 | 2,157 |
| Revenue | $51,030,884 | $47,117,457 | $72,803,447 | $66,170,636 |
| EBITDA | $18,853,182 | $13,851,233 | $29,166,506 | $23,065,742 |
| Net Income | $2,825,437 | -$1,426,220 | $10,594,774 | $5,714,163 |
| EPS | $0.03 | -$0.02 | $0.11 | $0.06 |
We have left our long-term production outlook largely unchanged.
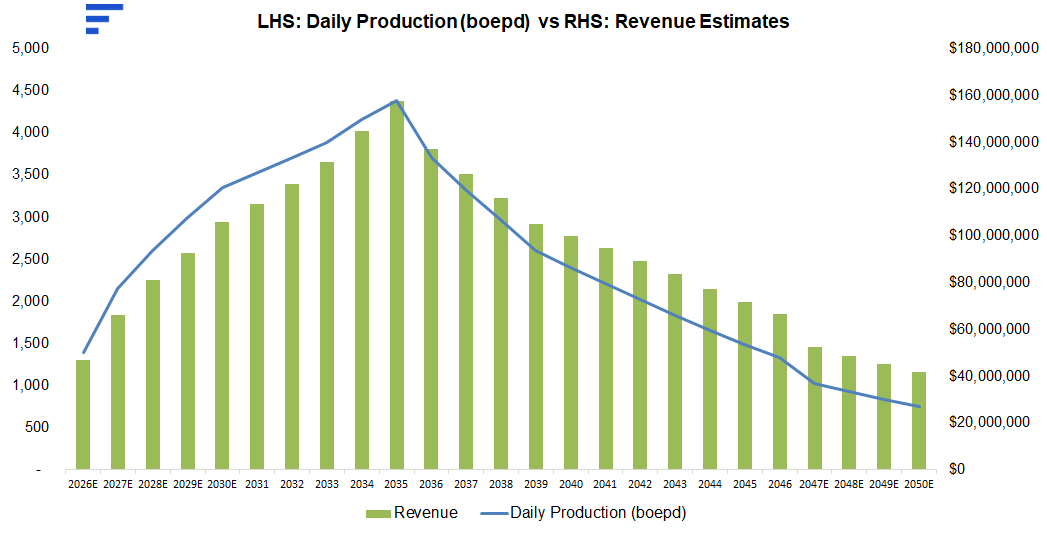
As a result, our DCF valuation declined from $2.01 to $1.95/share.
| DCF Model | 2026E | 2027E | 2028E | 2029E | 2048E | 2049E | 2050E |
|---|---|---|---|---|---|---|---|
| Cash from Operations | $14,007,252 | $21,429,524 | $27,841,994 | $31,832,992 | $4,181,733 | $2,101,868 | $92,002 |
| CAPEX | -$18,032,000 | -$17,514,000 | -$17,514,000 | -$17,514,000 | - | - | - |
| Free Cash Flow | -$4,024,748 | $3,915,524 | $10,327,994 | $14,318,992 | $4,181,733 | $2,101,868 | $92,002 |
| Present Value | -$3,747,091 | $3,314,002 | $7,946,686 | $10,015,898 | $478,270 | $218,539 | $8,696 |
| Discount Rate | 10.0% |
|---|---|
| Terminal Growth | 3.0% |
| Present Value | $178,169,531 |
| Cash - Debt (end of 2025) | $5,898,000 |
| Fair Value | $184,067,531 |
| Shares O/S | 94,600,000 |
| Value per Share ($) | $1.95 |
Sector multiples are down 8% since our last report. BRK trades at an average discount of 71% (previously 73%) to comparables. Applying sector multiples, we arrive at a comparable valuation of $0.88/share (previously $1.06/share), driven by lower sector multiples, and our lower revenue and EBITDA estimates.
| Enterprise Value (EV, A$M) | Daily Production (boepd) | 2P Reserves (MMBOE) | EV/Daily Produciton (A$/boepd) | EV/2P Reserves (A$/boe) | EV/R (f) | EV/EBITDA (f) | |
|---|---|---|---|---|---|---|---|
| Ring Energy | $999 | 20,500 | 153.00 | $48,732 | $6.53 | 1.89 | 3.34 |
| Prairie Operating | $770 | 28,000 | 121.00 | $27,500 | $6.36 | 1.20 | 3.11 |
| Sandridge | $547 | 19,500 | 69.10 | $28,051 | $7.92 | 1.80 | 2.73 |
| PEDEVCO | $395 | 6,500 | 32.00 | $60,769 | $12.34 | 1.84 | 4.12 |
| Kolibri Global Energy | $385 | 4,600 | 57.60 | $83,696 | $6.68 | 3.00 | 3.93 |
| Epsilon Energy | $295 | 4,650 | 33.12 | $63,441 | $8.91 | 3.10 | 7.00 |
| Evolution Petroleum | $278 | 7,380 | 27.10 | $37,669 | $10.26 | 2.12 | 6.11 |
| Lotus Creek Exploration Inc. | $181 | 3,590 | 11.18 | $50,418 | $16.20 | 3.46 | n/a |
| Touchstone Exploration Inc. | $173 | 4,739 | 40.38 | $36,506 | $4.28 | 2.00 | 4.98 |
| Arrow Exploration Corp. | $163 | 4,500 | 13.62 | $36,222 | $11.97 | 0.70 | 1.12 |
| Highwood Asset Management | $95 | 5,040 | 66.44 | $18,849 | $1.43 | 1.00 | 1.79 |
| Prairie Provident Resources Inc. | $77 | 3,467 | 24.40 | $22,209 | $3.16 | 2.01 | n/a |
| ROK Resources Inc. | $51 | 3,475 | 19.42 | $14,676 | $2.63 | 0.59 | 1.78 |
| Brookside Energy | $26 | 2,157 | 12.52 | $12,177 | $2.10 | 0.40 | 1.14 |
| Oil & Gas Production | 2.90 | 5.00 | |||||
| Average | $38,637 | $7.20 | 1.87 | 3.55 | |||
| BRK (Discount) | -68% | -71% | -79% | -68% | |||
| Fair Value Estimate @ Sector Average | $0.94 | $1.01 | $0.99 | $0.58 | |||
| Average | $0.88 | ||||||
We reiterate our BUY rating, and adjust our fair value estimate from $1.54 to $1.41/share (the average of our DCF and comparables valuations). Despite the downward revision, we believe significant production growth potential, strong liquidity, and a 100% drilling success rate remain underappreciated, with shares trading at a 71% discount to peers across key metrics. With two new wells online, 17 additional drilling locations, and a potential NYSE American ADR listing, we believe the company offers compelling exposure to near-term production growth, and valuation upside potential.
We are maintaining our risk rating of 3 (Average). We believe the company is exposed to the following key risks (not exhaustive):
| Income Statements (A$) YE December 31 |
2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|
| Revenue | $46,902,292 | $53,789,020 | $47,117,457 | $66,170,636 |
| Royalties expense | -$22,400,604 | -$23,213,212 | -$19,789,332 | -$28,453,373 |
| Production expense | -$2,397,148 | -$7,677,788 | -$7,067,618 | -$8,602,183 |
| Gross profit | $22,104,540 | $22,898,020 | $20,260,506 | $29,115,080 |
| SG&A | -$3,170,029 | -$5,146,458 | -$5,661,104 | -$5,944,159 |
| Other revenue, net of expenses | -$787,497 | $473,219 | -$648,000 | |
| Share-based expenses | -$433,333 | -$95,400 | -$100,170 | -$105,179 |
| EBITDA | $17,713,681 | $18,129,381 | $13,851,233 | $23,065,742 |
| Depreciation | -$15,083,248 | -$15,629,125 | -$15,570,120 | -$15,964,021 |
| EBIT | $2,630,433 | $2,500,256 | -$1,718,888 | $7,101,721 |
| Interest expense | -$691,298 | -$684,855 | -$297,763 | -$297,763 |
| Interest revenue | $997,294 | $307,950 | $338,745 | $338,745 |
| EBT | $2,936,429 | $2,123,351 | -$1,677,906 | $7,142,703 |
| Income tax expense | $251,686 | -$1,428,541 | ||
| Unusual/non-recurring expense | -$104,023 | $607,906 | ||
| Net Income | $2,832,406 | $2,731,257 | -$1,426,220 | $5,714,163 |
| EPS | $0.03 | $0.03 | -$0.02 | $0.06 |
| Balance Sheets (A$) YE December 31 |
2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|
| Assets | ||||
| Cash | $11,391,127 | $11,855,293 | $7,070,545 | $10,986,069 |
| A/R | $8,327,305 | $4,333,520 | $4,550,196 | $4,777,706 |
| Others | $96,732 | $402,851 | $422,994 | $444,143 |
| Current Assets | $19,815,164 | $16,591,664 | $12,043,734 | $16,207,918 |
| PP&E | $17,843 | $179,287 | $179,287 | $179,287 |
| Exploration assets | $32,992,833 | $25,087,313 | $26,318,253 | $27,093,242 |
| Others | $74,860,967 | $72,225,938 | $73,456,878 | $74,231,867 |
| Total Assets | $127,686,807 | $114,084,202 | $111,998,152 | $117,712,315 |
| Liabilities & Shareholders' Equity | ||||
| A/P | $24,215,527 | $17,032,954 | $17,032,954 | $17,032,954 |
| Others | $4,928,022 | $4,241,491 | $4,241,491 | $4,241,491 |
| Current Liabilities | $29,143,549 | $21,274,445 | $21,274,445 | $21,274,445 |
| Others | $3,134,477 | $801,542 | $801,542 | $801,542 |
| Total Liabilities | $32,278,026 | $22,075,987 | $22,075,987 | $22,075,987 |
| Shareholders' Equity | $95,408,781 | $92,008,215 | $89,922,165 | $95,636,328 |
| Total Liabilities and SE | $127,686,807 | $114,084,202 | $111,998,152 | $117,712,315 |
| Cash Flow Statements (A$) YE December 31 |
2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|
| Net Income | $2,832,406 | $2,731,257 | -$1,426,220 | $5,714,163 |
| Non-cash items | $15,620,604 | $15,829,390 | $15,670,290 | $15,964,021 |
| Changes in working capital | $2,597,324 | $2,428,706 | -$236,819 | -$248,659 |
| Cash from Operating Activities | $21,050,334 | $20,989,353 | $14,007,252 | $21,429,524 |
| Equity | -$99,000 | -$279,160 | -$760,000 | |
| Debt | -$22,117 | -$133,910 | ||
| Other | -$29,189 | -$180,934 | ||
| Cash From Financing Activities | -$150,306 | -$594,004 | -$760,000 | - |
| PP&E | -$21,059 | -$73,830 | ||
| Exploration | -$36,815,106 | -$18,693,551 | -$18,032,000 | -$17,514,000 |
| Others | $0 | -$1,224,766 | ||
| Cash From Investing Activities | -$36,836,165 | -$19,992,147 | -$18,032,000 | -$17,514,000 |
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Buy – Fair value is 12% above the current market price; or risk and reward is favorable
Hold – Fair value is between 5% to 12% above the current market price
Sell – Fair value is 5% above, or less, than the current market value; or risk and reward is unfavorable
Suspended or Rating N/A— Coverage and ratings suspended until more information can be obtained from the company regarding recent events.
1 (Low Risk) - The company operates in an industry where it has a strong position (for example a monopoly, high market share etc.) or operates in a regulated industry. The future outlook is stable or positive for the industry. The company generates positive free cash flow and has a history of profitability. The capital structure is conservative with little or no debt.
2 (Below Average Risk) - The company operates in an industry where the fundamentals and outlook are positive. The industry and company are relatively less sensitive to systematic risk than companies with a Risk Rating of 3. The company has a history of profitability and has demonstrated its ability to generate positive free cash flows (though current free cash flow may be negative due to capital investment). The company’s capital structure is conservative with little to modest use of debt.
3 (Average Risk) - The company operates in an industry that has average sensitivity to systematic risk. The industry may be cyclical. Profits and cash flow are sensitive to economic factors although the company has demonstrated its ability to generate positive earnings and cash flow. Debt use is in line with industry averages, and coverage ratios are sufficient.
4 (Speculative) - The company has little or no history of generating earnings or cash flow. Debt use is higher. These companies may be in start-up mode or in a turnaround situation. These companies should be considered speculative.
5 (Highly Speculative) - The company has no history of generating earnings or cash flow. They may operate in a new industry with new, and unproven products. Products may be at the development stage, testing, or seeking regulatory approval. These companies may run into liquidity issues and may rely on external funding. These stocks are considered highly speculative.
Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE.
Analyst Certification: The views expressed in this report accurately reflect the personal views of the analyst, and no part of their compensation was, is, or will be directly or indirectly related to the specific recommendation or views expressed.
Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The analyst and Fundamental Research Corp. “FRC” do not own any shares of the subject company, do not make a market or offer shares for sale of the subject company, and do not have any investment banking business with the subject company. Fees ranging between $30,000 and $40,000 have been paid to FRC by Brookside Energy to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. FRC takes steps to mitigate conflicts including setting fees in advance and utilizing analysts who must abide by CFA Institute Code of Ethics and Standards of Professional Conduct. Additionally, analysts may not trade in any security under coverage. Our full editorial control of all research, timing of release of the reports, and release of liability for negative reports are protected contractually. The issuer has agreed to a minimum coverage term and coverage cannot be unilaterally terminated. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time.
The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (22%).
This report contains "forward looking" statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company's products/services in the marketplace; acceptance in the marketplace of the Company's new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company's periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. A report initiating coverage will most often be updated quarterly while a report issuing a rating may have no further or less frequent updates because the subject company is likely to be in earlier stages where nothing material may occur quarter to quarter.
Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
Batting 100%; Poised for Q4 Rebound on Two New Wells
Paused · 9:28 left · FRC · read by an AI voice
Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.