
Namib Minerals Ordinary Shares holds 7.2 Moz of gold resources across three Zimbabwe mines, with How Mine currently active and Mazowe and Redwing advancing toward production.
From One Mine to Three: An Emerging Gold Producer
Paused · 17:15 left · FRC · read by an AI voice
Disclosure: Namib Minerals Ordinary Shares has paid FRC a fee for research coverage and distribution of reports. This fee creates a potential conflict of interest which readers should consider. See last page for other important disclosures, rating, and risk definitions.
All figures in US$ unless otherwise specified.
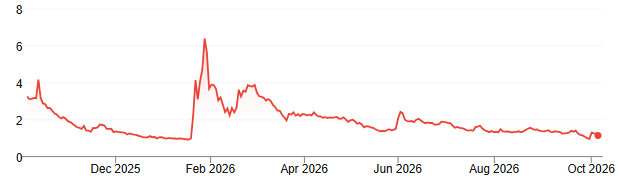
Price and Volume (1-year)
| YTD | 12M | |
|---|---|---|
| NAMM | -14% | -51% |
| GDXJ | -10% | 16% |
| Gold | -8% | 1% |
| NASDAQ | 10% | 10% |
| Key Financial Data (FYE - Dec 31) | 2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|
| Gold Sales (oz) | 37,346 | 24,860 | 26,500 | 39,824 |
| Revenue ($M) | $85.88 | $82.60 | $111.41 | $159.29 |
| Adj. Net Income ($M) | $9.31 | $2.25 | $22.39 | $43.78 |
| Adj. EPS ($) | $0.18 | $0.04 | $0.40 | $0.78 |
| Debt ($M) | $2.50 | $5.18 | $13.90 | $13.90 |
| Total Assets ($M) | $51.00 | $62.79 | $86.44 | $123.26 |
* Namib Minerals has paid FRC a fee for research coverage and distribution of reports. See last page for other important disclosures, rating, and risk definitions. All figures in US$ unless otherwise specified.
NAMM was established in 2024, by South African mining entrepreneur Mzi Godfrey Khumalo, through the Southern SelliBen Trust, which currently holds a 61% ownership stake. The company began trading on Nasdaq in 2025.
NAMM owns three underground gold mines in Zimbabwe, one operational, with 7.2 Moz in combined resources.
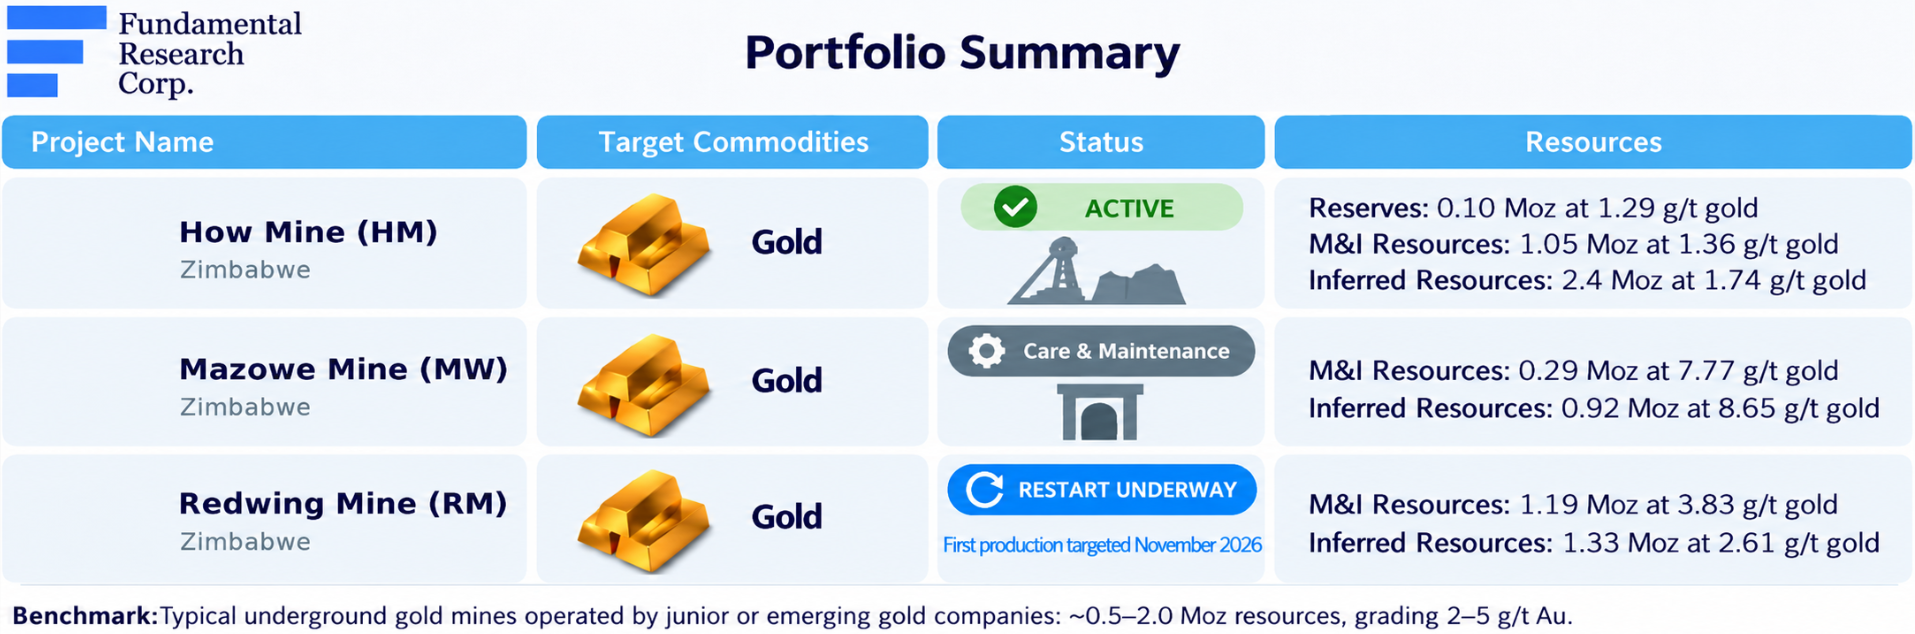
Portfolio Summary
| Project Name | Target Commodities | Status | Resources |
|---|---|---|---|
| How Mine (HM) Zimbabwe | Gold | ACTIVE | Reserves: 0.10 Moz at 1.29 g/t gold M&I Resources: 1.05 Moz at 1.36 g/t gold Inferred Resources: 2.4 Moz at 1.74 g/t gold |
| Mazowe Mine (MW) Zimbabwe | Gold | Care & Maintenance | M&I Resources: 0.29 Moz at 7.77 g/t gold Inferred Resources: 0.92 Moz at 8.65 g/t gold |
| Redwing Mine (RM) Zimbabwe | Gold | RESTART UNDERWAY First production targeted November 2026 |
M&I Resources: 1.19 Moz at 3.83 g/t gold Inferred Resources: 1.33 Moz at 2.61 g/t gold |
NAMM acquired the three mines from Metallon Corporation, a UK-based gold mining company, for $67M, payable by Khumalo, and the Southern SelliBen Trust.
Located across prolific Zimbabwean gold belts, the mines benefit from established infrastructure, reducing development and capital requirements.
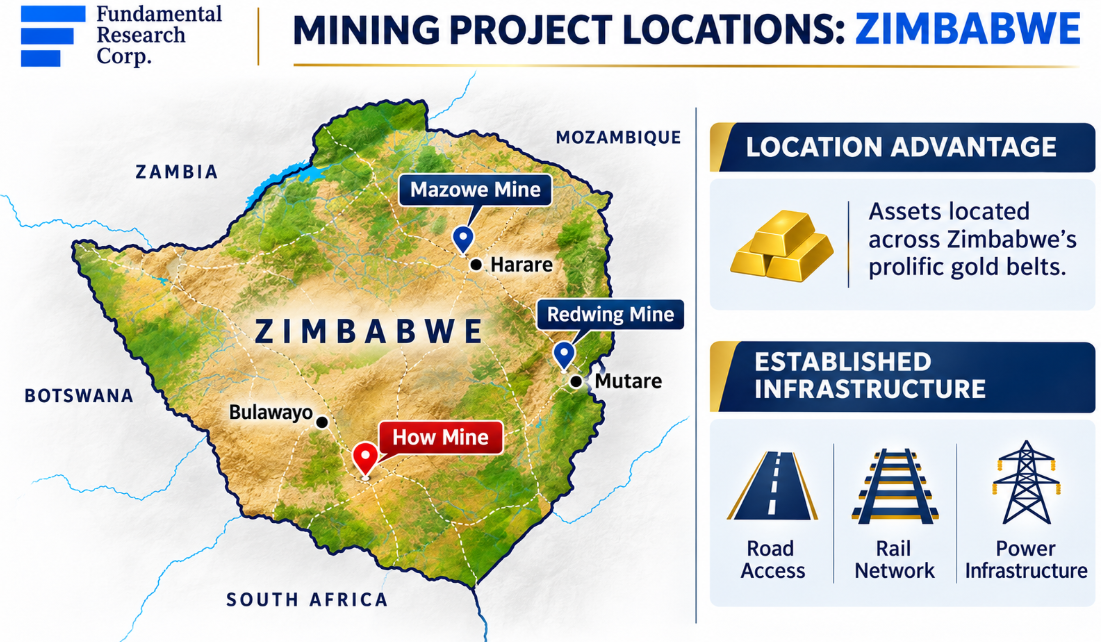
Zimbabwe is a major African gold producer, with a long history of gold production. Prospective geology and government incentives are favourable, while regulatory, FOREX, and security risks remain.
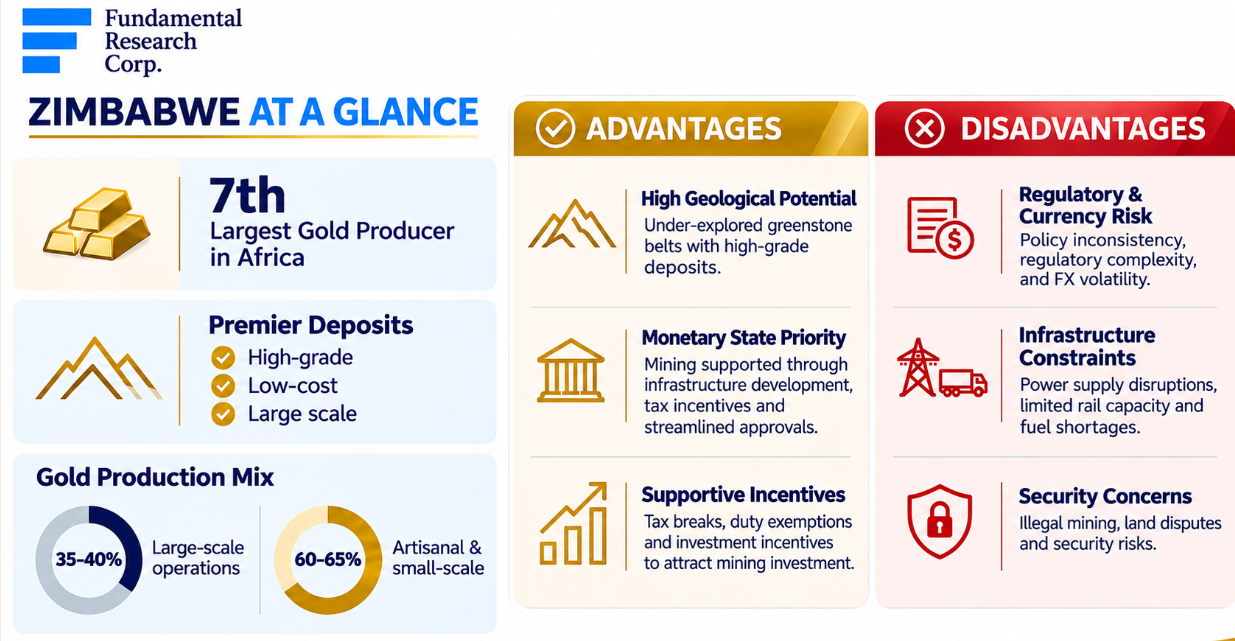
The following sections provide an overview of NAMM’s gold mines, and their development potential.
The flagship mine spans 2,408 hectares, and includes an underground gold mine, and processing facilities. Located ~22 km southeast of Bulawayo, and ~120 km northwest of Caledonia Mining’s Blanket mine, one of Zimbabwe’s largest and lowest-cost underground gold producers.
HM hosts a classic orogenic gold deposit comprising several high-grade mineralized lenses. The deposit extends 1.2 km along strike, ranges from 2–15 m in width, and remains open to a depth of 1.2 km. Overall, we believe these dimensions are consistent with a sizeable underground gold deposit.
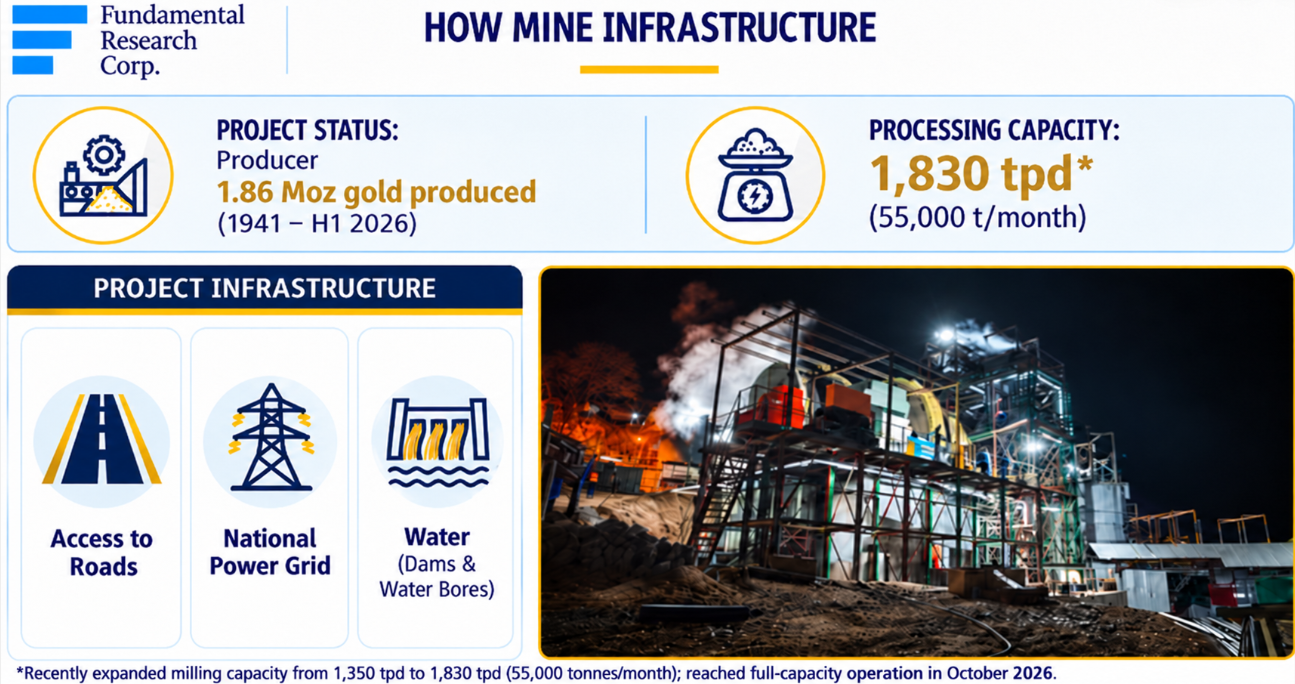
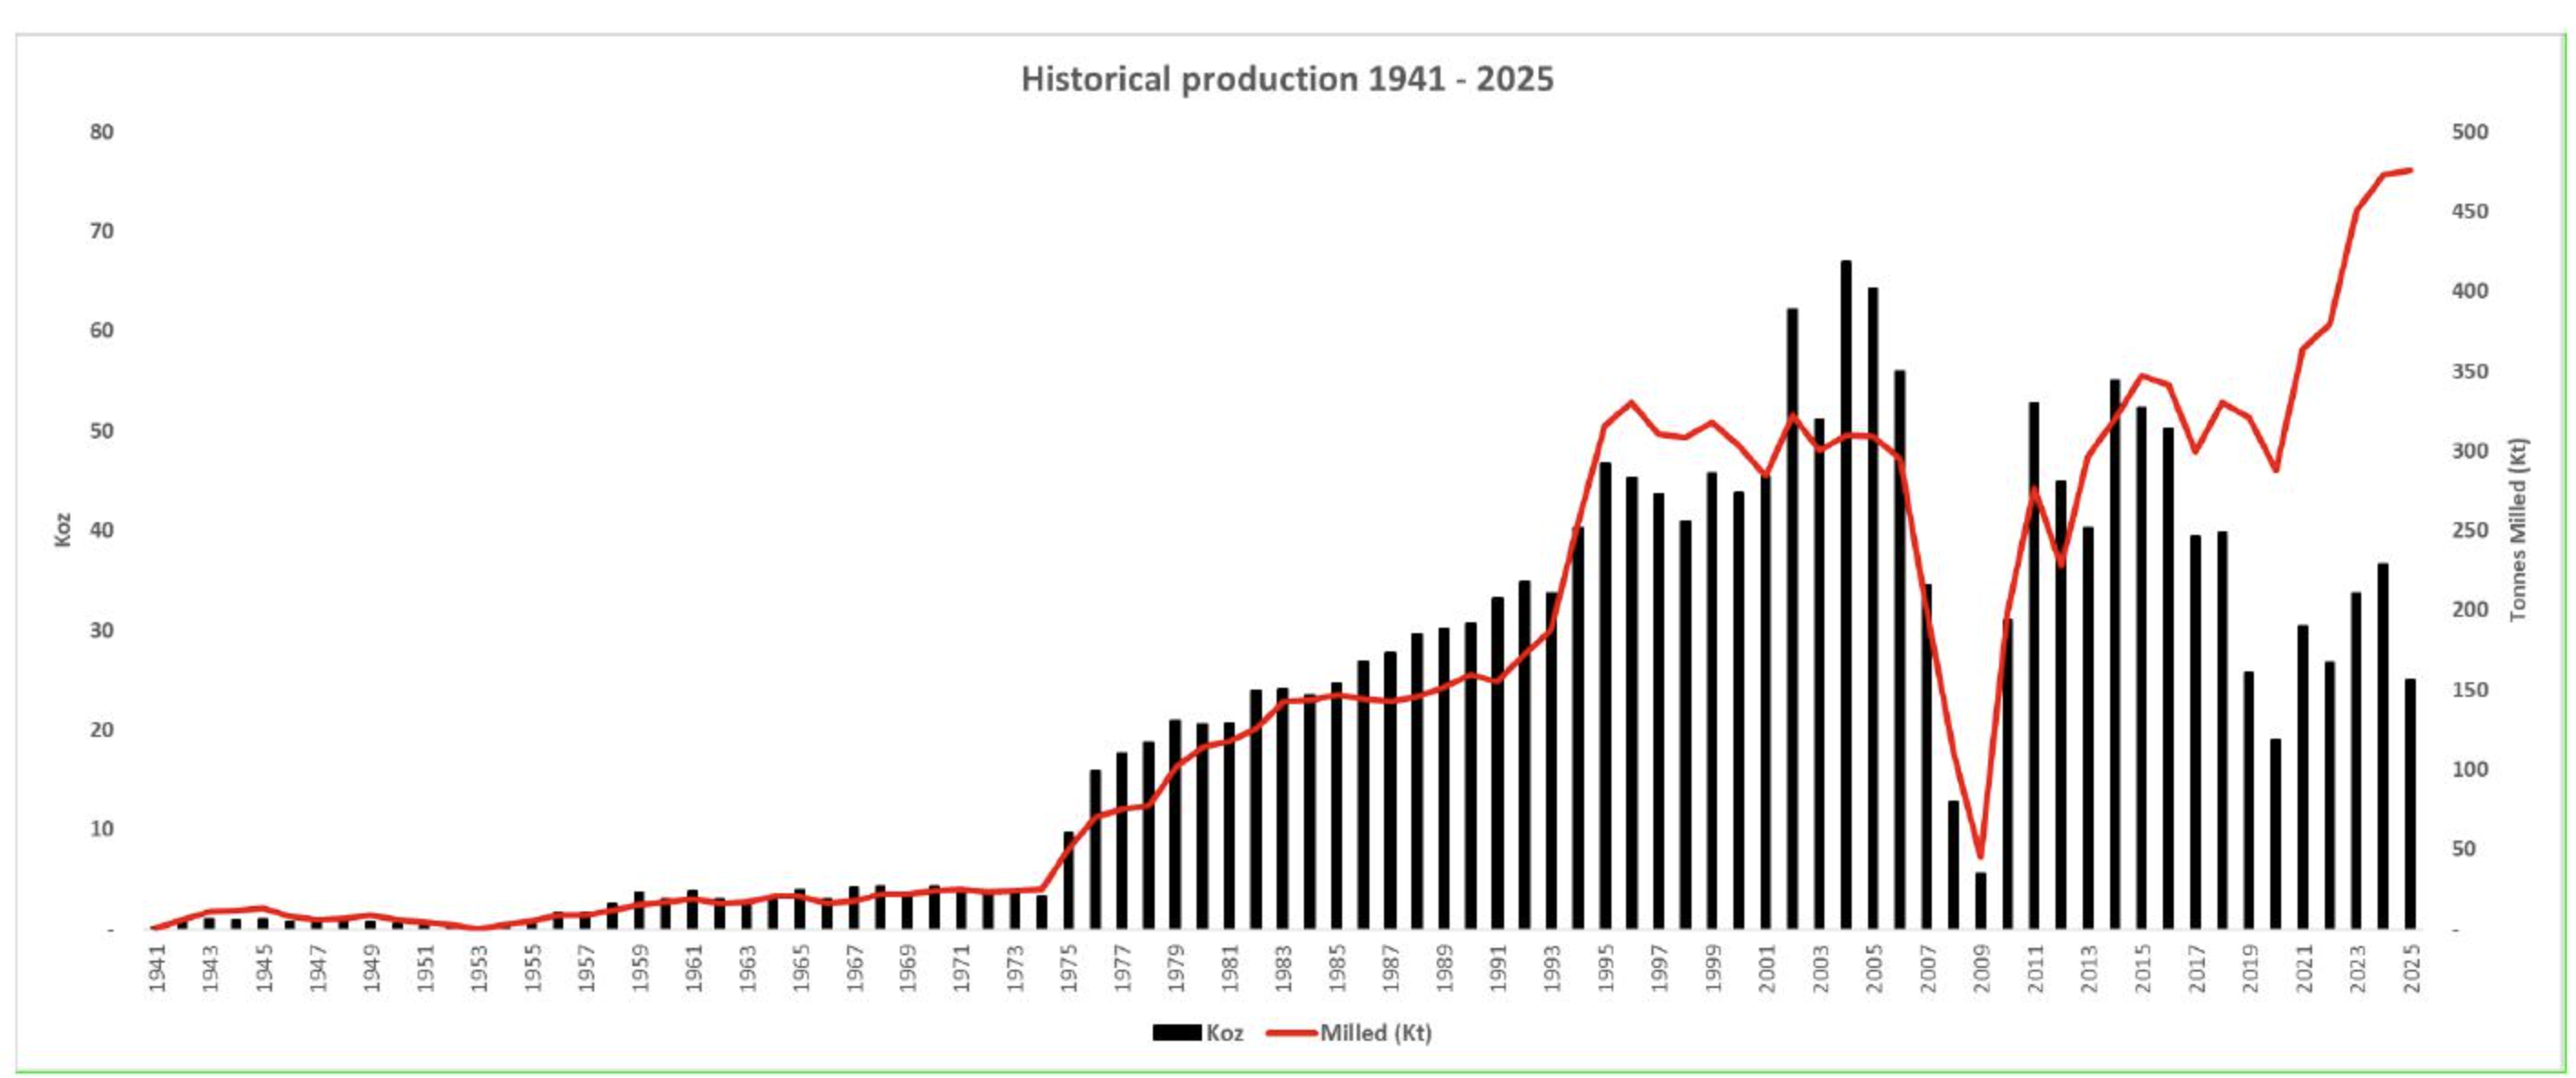
Orogenic gold deposits are typically large-scale, supporting long-life mining operations. Long production history: Produced ~1.86 Moz of gold from 1941 to June 2026.
Production History, 1941-2025
HM hosts 3.4 Moz in resources, above the typical 0.5–2.0 Moz range for junior-owned gold projects. In addition, average grade of 1.6 g/t is below the typical 2–5 g/t for underground gold mines; however, cash costs of ~$1,500–$1,600/oz are within the $1,200–$1,700/oz industry range, supported by coarse, free-milling gold that is inexpensive to recover.
How Mine Resources (2025)
| Category | Tonnes (Mt) | Grade (g/t Au) | Contained Gold (Moz) | Benchmark |
|---|---|---|---|---|
| Measured | 13.7 | 1.32 | 0.58 | Resource size: 0.5–2.0 Moz Grade: 2–5 g/t Au |
| Indicated | 10.2 | 1.41 | 0.46 | |
| M&I | 23.9 | 1.36 | 1.05 | |
| Inferred | 43.0 | 1.74 | 2.40 | |
| Total | 66.9 | 1.61 | 3.44 |
Production has declined from 2024 levels due to lower grades, but is expected to recover following the recent expansion of mill capacity from ~1,350 tpd, to ~1,830 tpd.
| How Mine Performance Metrics | 2023 | 2024 | 2025 | H1 2026 |
|---|---|---|---|---|
| Gold Sales, oz | 33,585 | 37,239 | 24,860 | 11,357 |
| Tonnage, kt | 450 | 473 | 476 | 233 |
| Grade, g/t Au | 3.00 | 2.66 | 1.84 | 1.70 |
| Recovery, % | 90% | 90% | 89% | 88% |
| Average Net Realized Price, $/oz | $1,784 | $2,184 | $3,156 | $4,195 |
| C1 Cost/oz, $/oz | $1,185 | $1,159 | $1,535 | $1,576 |
| Gross Profit, $/oz | $599 | $1,025 | $1,621 | $2,376 |
| AISC/oz, $/oz | $1,366 | $1,392 | $2,146 | $2,534 |
2026 production guidance is 26,500–27,000 oz (+7–9% YoY); we believe full ramp-up could support annual production above 30,000 oz. Gross profit per ounce rose from $1,032 in 2024, to $2,376 in H1-2026, driven by higher gold prices.
Management plans $11M in exploration drilling from 2026–2029, averaging $2.7M annually.
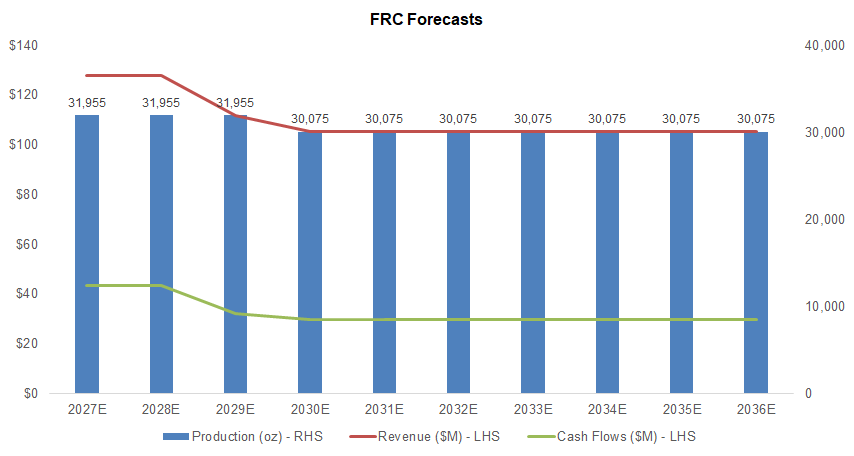
We believe the current resource base could support a multi-decade mine life, providing a foundation for long-term, recurring cash flow. We also believe resource expansion, and mine-life extension potential, remains significant, particularly at depth, with drilling identifying mineralization below the current ~1 km operating depth.
Redwing is a former gold mine on a 1,254-hectare property, located 20 km northeast of Mutare, a commercial and industrial hub.
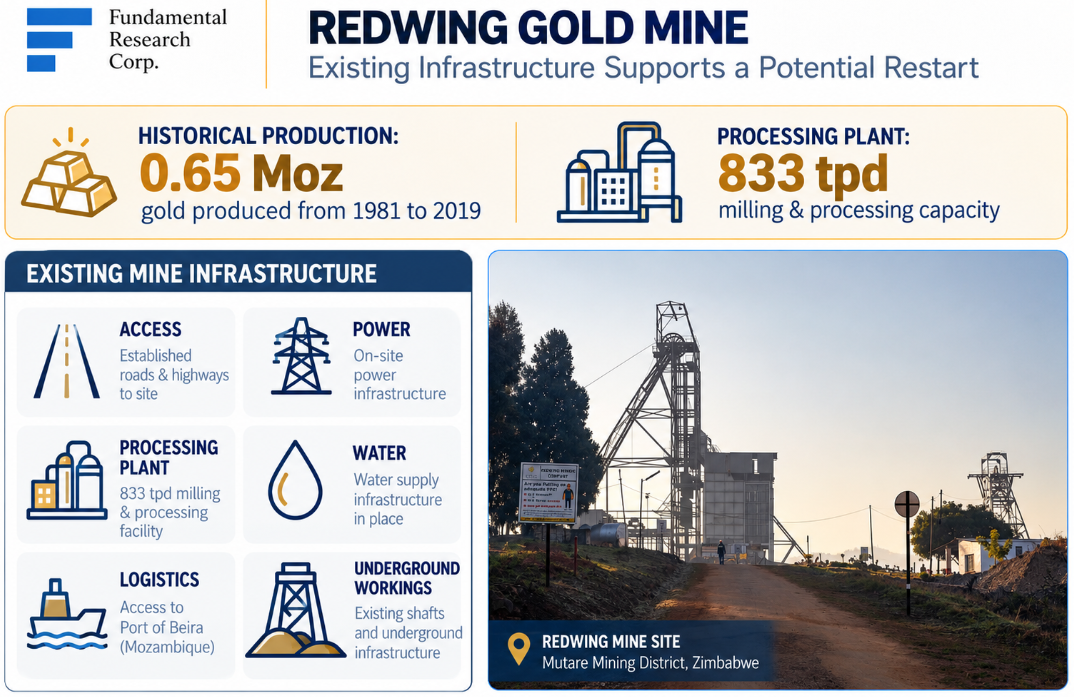
Redwing hosts a relatively large, medium-grade gold resource.
Redwing Mine Resources (2025)
| Category | Tonnes (Mt) | Grade (g/t Au) | Contained Gold (Moz) | Benchmark |
|---|---|---|---|---|
| Measured | 1.45 | 2.92 | 0.14 | Resource size: 0.5–2.0 Moz Grade: 2–5 g/t Au |
| Indicated | 8.20 | 3.99 | 1.05 | |
| M&I | 9.65 | 3.83 | 1.19 | |
| Inferred | 15.83 | 2.61 | 1.33 | |
| Total | 25.48 | 3.07 | 2.52 |
After nearly four decades of production, the mine was placed on care and maintenance in 2019 due to declining grades and funding constraints. Flooding and illegal mining have since complicated the restart.
In May 2026, Zimbabwe restricted small-scale gold mining to locally owned operators, requiring foreign-owned mines to produce at least 640 oz/month or invest $15M by January 2027. Redwing does not meet these thresholds, prompting NAMM to develop a plan to resume production.
Large-scale production could resume within three years of securing financing, subject to a feasibility study, infrastructure upgrades and mine rehabilitation.
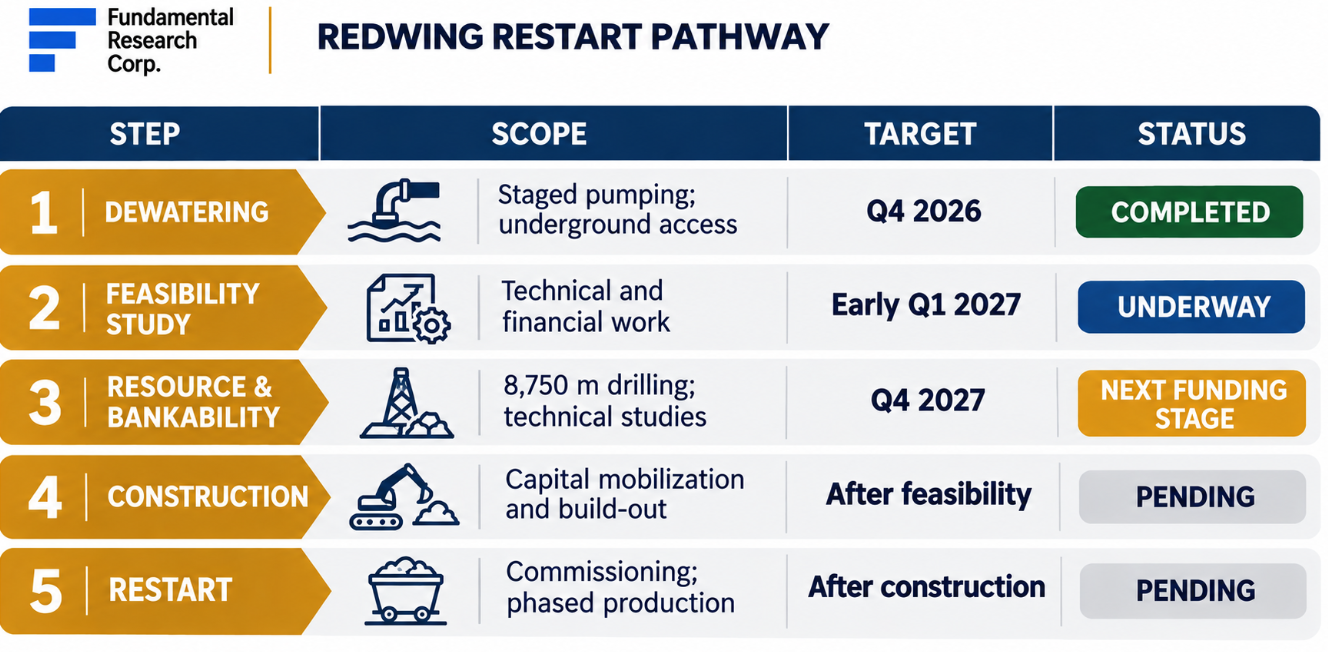
REDWING RESTART PATHWAY
| STEP | SCOPE | TARGET | STATUS |
|---|---|---|---|
| 1 DEWATERING | Staged pumping; underground access | Q4 2026 | COMPLETED |
| 2 FEASIBILITY STUDY | Technical and financial work | Early Q1 2027 | UNDERWAY |
| 3 RESOURCE & BANKABILITY | 8,750 m drilling; technical studies | Q4 2027 | NEXT FUNDING STAGE |
| 4 CONSTRUCTION | Capital mobilization and build-out | After feasibility | PENDING |
| 5 RESTART | Commissioning; phased production | After construction | PENDING |
Dewatering was completed in September 2026, restoring underground access. NAMM is now re-equipping the mine, refurbishing the processing plant and upgrading infrastructure, with $30M in restart CAPEX. Initial production is targeted at 10,000 t/month (~835 oz/month) in 2027, exceeding the 640 oz/month threshold.
NAMM is also advancing a larger-scale feasibility study, including 8,750 m of resource-definition drilling, and technical work through Q4-2027. The company has signed a term sheet for a proposed $30M loan facility from Ecobank, a pan-African commercial banking group, to fund resource-definition and bankability studies. Ecobank may also arrange construction financing, potentially reducing future funding risk.
NAMM is anticipating first gold pour this month.
Mazowe is a past-producing mine located on a 1,956-hectare property. Located 50 km northwest of Harare, and 50 km southwest of Freda Rebecca, one of Zimbabwe’s largest gold producing mines. Produced 1.36 Moz (1962–2018); suspended due to declining performance, and funding constraints.
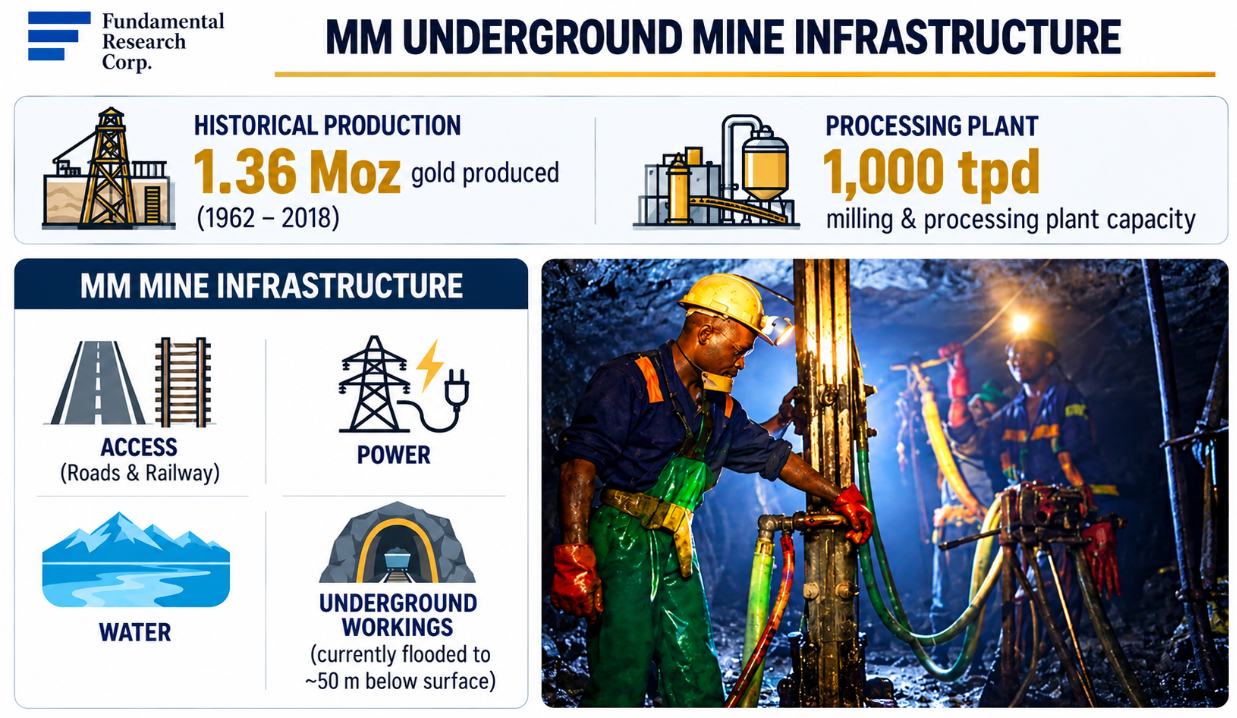
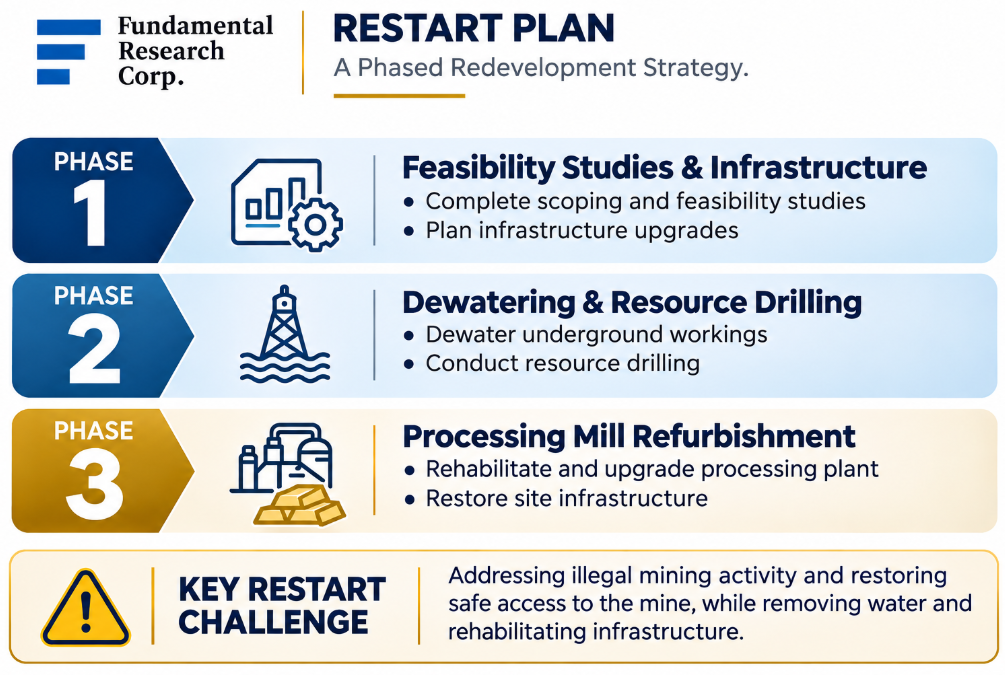
Mazowe has been mined since the 1890s, producing 1.36 Moz of gold from 1962–2018. Production declined from 10–12 koz annually in 2012–2016, to ~6 koz in 2017, and ~1 koz in 2018, reflecting lower grades, limited exploration, and development, and poor plant performance. The mine entered care and maintenance in 2018, and was subsequently affected by flooding and illegal mining, complicating the restart. Management is pursuing a phased restart involving dewatering, infrastructure rehabilitation, and feasibility studies.
Mazowe hosts a modest resource with exceptionally high grades.
Mazowe Mine Resources (2025)
| Category | Tonnes (Mt) | Grade (g/t Au) | Contained Gold (Moz) | Benchmark |
|---|---|---|---|---|
| Measured | 0.26 | 9.01 | 0.08 | Resource size: 0.5–2.0 Moz Grade: 2–5 g/t Au |
| Indicated | 0.91 | 7.42 | 0.22 | |
| M&I | 1.17 | 7.77 | 0.29 | |
| Inferred | 3.29 | 8.65 | 0.92 | |
| Total | 4.46 | 8.42 | 1.21 |
Under Zimbabwe’s new regulations, NAMM must restart production at Mazowe by January 2027 or pursue an alternative strategy. We expect management to announce its strategy for the project shortly. We believe Mazowe has the potential to support annual gold production of 75–100 Koz.
We believe the company is led by an experienced team with deep expertise across mining, finance, capital markets, energy, governance, and African operations.
Four of the six directors are independent, supporting board oversight and governance. Management, directors, and key shareholders collectively own 71% of outstanding shares, aligning their interests with other investors. However, we believe the low public float may constrain liquidity, and increase share price volatility.
| Management and Board | Shares | % of Total |
|---|---|---|
| Tulani Sikwila, Chairman and CEO | 4,838,126 | 8.6% |
| Siphesihle Mchunu, CFO & Director | 977,399 | 1.7% |
| Wendy Luhabe, Lead Independent Director | - | - |
| Dennis Johnson, Independent Director | - | - |
| Tito Martins, Independent Director | - | - |
| Pascoal Alberto Bacela, Independent Director | - | - |
| Institutions / Others | Shares | % of Total |
| The Southern SelliBen Trust | 20,208,973 | 35.7% |
| Core SA (Khumalo-controlled) | 10,000,000 | 17.7% |
| Mzilikazi Khumalo (direct) | 4,000,000 | 7.1% |
| Total - Management/ Directors / Institutions | 40,024,498 | 70.8% |
Production has declined due to lower grades; higher mill capacity at HM, and Redwing’s restart, should drive recovery.
| Operating Metrics | 2023 | 2024 | 2025 | H1 2025 | H1 2026 | YoY |
|---|---|---|---|---|---|---|
| Gold production (oz) | 33,700 | 36,600 | 25,000 | 12,741 | 11,373 | -11% |
| Gold sales (oz) | 33,994 | 37,346 | 24,860 | 12,226 | 11,357 | -7% |
| Tonnes milled (kt) | 454 | 478 | 476 | 236 | 233 | -1% |
| Head grade (g/t) | 2.6 | 2.7 | 1.9 | 1.9 | 1.7 | -11% |
| Recovery (%) | 90% | 90% | 89% | 89% | 88% | -1% |
| Avg. net realized gold price ($/oz) | $1,776 | $2,185 | $3,156 | $2,827 | $4,195 | 48% |
| C1 cash cost ($/oz) | $1,174 | $1,150 | $1,653 | $1,510 | $1,576 | 4% |
| AISC ($/oz) | $1,628 | $1,535 | $2,546 | $2,462 | $3,078 | 25% |
H1-2026 revenue rose 40% YoY, and adjusted EBITDA increased 76% YoY, while EPS improved from ($0.24) to ($0.09), driven by higher gold prices despite lower production. Gross and EBITDA margins remained well above sector averages.
| Financial Summary | 2023 | 2024 | 2025 | H1 2025 | H1 2026 | YoY |
|---|---|---|---|---|---|---|
| Revenue | $65.10 | $85.88 | $82.60 | $36.38 | $50.84 | 40% |
| Gross Profit | $25.20 | $42.93 | $41.50 | $16.10 | $29.84 | 85% |
| EBITDA | $16.20 | $22.83 | $18.10 | $0.40 | $16.14 | N/A |
| EBITDA (Adj.) | $20.26 | $24.55 | $29.00 | $10.77 | $19.00 | 76% |
| Net Income | $3.60 | $3.59 | $101.18 | -$11.90 | -$4.76 | N/A |
| EPS | $0.07 | $0.07 | $1.96 | -$0.24 | -$0.09 | N/A |
| Net Income (Adj.) | $3.60 | $9.31 | $2.25 | -$6.60 | $6.53 | N/A |
| EPS (Adj.) | $0.07 | $0.18 | $0.04 | -$0.13 | $0.12 | N/A |
| Margins | 2023 | 2024 | 2025 | H1 2025 | H1 2026 | Sector |
|---|---|---|---|---|---|---|
| Gross (pre-D&A) | 38.7% | 50.0% | 50.2% | 44.3% | 58.7% | 20.4% |
| EBITDA | 24.9% | 26.6% | 21.9% | 1.1% | 31.7% | |
| EBITDA (Adj.) | 31.1% | 28.6% | 35.1% | 29.6% | 37.4% | 13.1% |
| EBIT | 20.7% | 21.8% | 13.1% | -6.3% | 26.0% | 11.8% |
| Net (Adj.) | 5.5% | 10.8% | 2.7% | -18.2% | 12.9% | 10.3% |
The balance sheet is strained due to negative working capital, although debt levels remain modest relative to assets.
| Summary of Cash Flows ($M) | 2023 | 2024 | 2025 | H1 2025 | H1 2026 | YoY |
|---|---|---|---|---|---|---|
| Cash Flow From Operations | $14.92 | $19.13 | $13.79 | $5.77 | $9.29 | 61% |
| Cash flow Used in investing | -$5.63 | -$10.07 | -$12.39 | -$5.65 | -$10.74 | N/A |
| Cash flow Used in financing | -$9.07 | -$9.65 | $0.80 | $0.53 | $1.37 | 158% |
| Foreign Exchange Rate Adj. | -$0.01 | -$0.01 | $0.01 | -$0.02 | -$0.05 | N/A |
| Net Change in Cash | $0.21 | -$0.60 | $2.21 | $0.63 | -$0.13 | N/A |
| Free Cash Flows | $9.29 | $9.06 | $1.40 | $0.12 | -$1.45 | N/A |
We believe stronger H2-2026 and 2027 cash flows will strengthen the balance sheet.
| Liquidity Analysis ($M) | 2023 | 2024 | 2025 | Q2 2026 | Sector |
|---|---|---|---|---|---|
| Cash & Equivalents | $0.30 | $0.70 | $1.89 | $1.80 | |
| Working Capital | -$37.00 | -$37.00 | -$37.40 | -$42.90 | |
| Current Ratio | 0.10 | 0.20 | 0.30 | 0.32 | 1.90 |
| Debt | $2.40 | $2.50 | $5.18 | $7.40 | |
| LT Debt | - | $1.40 | $2.01 | $1.80 | |
| Debt/Capital | N/A | N/A | N/A | N/A | 17.40% |
| LT Debt/Capital | 0.0% | N/A | N/A | N/A | 12.10% |
Our sum-of--parts DCF valuation is $4.60/share. Redwing is commencing small-scale production, while Mazowe remains pre-development. We use preliminary assumptions, and higher discount rates for both projects, reflecting their early-stage status, and pending feasibility studies.
| Valuation Summary | ||
|---|---|---|
| How Mine | $220,384,697 | $2.60 |
| Redwing Mine | $38,992,881 | $0.46 |
| Mazowe Mine | $167,324,625 | $1.98 |
| Working Capital, net of LT Debt | -$37,158,000 | -$0.44 |
| Fair Value | $389,544,203 | $4.60 |
| DCF Valuation - HM | |
|---|---|
| Annual Throughput (tonnes) | 660,000 |
| Years of Operation | 15 |
| Au grade (gpt) | 1.62 |
| Au Recovery | 89% |
| Avg. Annual Au Production (oz) | 30,075 |
| Average Price of Au ($/oz) - 2029+ | $3,500 |
| Avg. Cash Costs ($/oz) | $1,650 |
| Initial CAPEX ($) | - |
| Discount Rate | 11.5% |
| After-Tax Net Asset Value ($) | $220,384,697 |
| No. of Shares * | 84,622,406 |
| Fair Value / Share | $2.60 |
| DCF Valuation - Redwing | |
|---|---|
| Annual Throughput (tonnes) | 304,045 |
| Years of Operation | 15 |
| Au grade (gpt) | 3.07 |
| Au Recovery | 89% |
| Avg. Annual Au Production (oz) | 26,584 |
| Average Price of Au ($/oz) - 2029+ | $3,500 |
| Avg. Cash Costs ($/oz) | $1,300 |
| Initial CAPEX ($M) | $165 |
| Discount Rate | 15.0% |
| After-Tax Net Asset Value ($) | $38,992,881 |
| No. of Shares * | 84,622,406 |
| Fair Value / Share | $0.46 |
| DCF Valuation - Mazowe | |
|---|---|
| Annual Throughput (tonnes) | 365,000 |
| Years of Operation | 10 |
| Au grade (gpt) | 8.42 |
| Au Recovery | 89% |
| Avg. Annual Au Production (oz) | 87,528 |
| Average Price of Au ($/oz) - 2029+ | $3,500 |
| Avg. Cash Costs ($/oz) | $1,300 |
| Initial CAPEX ($M) | $135 |
| Discount Rate | 20.0% |
| After-Tax Net Asset Value ($) | $167,324,625 |
| No. of Shares * | 84,622,406 |
| Fair Value / Share | $1.98 |
Gold prices remain a key driver of our valuation.
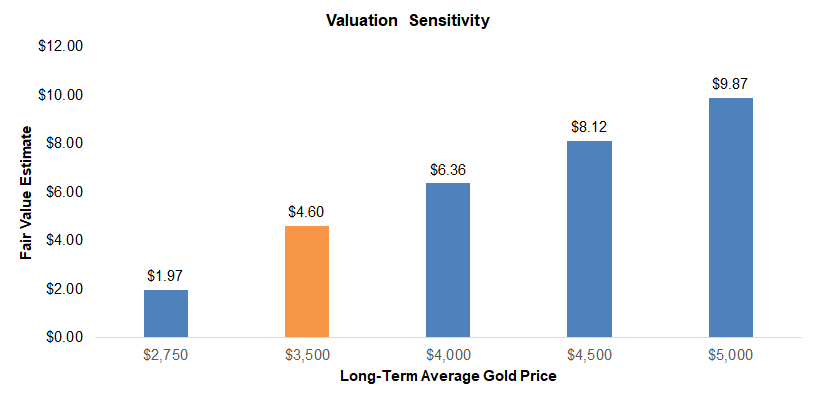
We also valued NAMM based on the average forward valuation multiples of junior gold miners. NAMM trades at 0.8x forward revenue vs. 1.6x for comparables, a 46% discount. Similarly, NAMM trades at 1.9x forward EBITDA vs. 2.8x for comparables, a 31% discount. Applying comparable average multiples implies fair value estimates of $2.47/share based on revenue, and $4.50/share based on EBITDA.
| Junior Gold Producers | Enterprise Value ($M) | MCAP ($M) | EV/Forward Revenue | EV / Forward EBITDA |
|---|---|---|---|---|
| Orezone Gold Corporation (TSX:ORE) | $1,373 | $1,358 | 1.33 | 2.61 |
| Alkane Resources Ltd (ASX:ALK) | $1,195 | $1,485 | 1.85 | 3.43 |
| McEwen Inc. (NYSE:MUX) | $899 | $862 | 3.48 | 6.07 |
| Mako Mining Corp. (TSXV:MKO) | $565 | $637 | 2.70 | 4.83 |
| Galiano Gold Inc. (TSX:GAU) | $524 | $519 | 0.77 | 1.69 |
| Goldgroup Mining Inc. (TSXV:GORO) | $460 | $476 | 1.71 | N/A |
| Caledonia Mining (NYSEAM:CMCL) | $362 | $387 | 1.09 | 2.17 |
| Integra Resources Corp. (TSXV:ITR) | $347 | $427 | 1.12 | 3.44 |
| TRX Gold Corporation (TSX:TRX) | $311 | $300 | 2.44 | 3.02 |
| Thor Explorations Ltd. (TSXV:THX) | $232 | $425 | 0.61 | 0.85 |
| Serabi Gold plc (AIM:SRB) | $132 | $195 | 0.61 | 1.11 |
| Namib Minerals (NasdaqGM:NAMM) | $107 | $46 | 0.84 | 1.94 |
| Average (excl. outliers) | 1.55 | 2.83 | ||
| Fair Value of NAMM @ Sector Average | $2.47 | $4.50 | ||
| NAMM’s Discount | -46% | -31% |
We are initiating coverage with a BUY rating, and a fair value estimate of $4.04/share, based on the average of our DCF and comparables valuations. We believe NAMM’s production growth, and restart opportunities are not fully reflected in its share price. The anticipated first gold pour at Redwing, continued production growth at How, and progress toward restarting Mazowe could help unlock further value.
We are assigning a risk rating of 4 (Highly Speculative).
We believe the company is exposed to the following key risks (not exhaustive):
| Income Statement ($M, except EPS) | 2023 | 2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|---|
| Revenue | $65.10 | $85.88 | $82.60 | $111.41 | $159.29 |
| Production costs | -$36.70 | -$38.67 | -$36.96 | -$42.34 | -$62.95 |
| Royalties | -$3.20 | -$4.28 | -$4.14 | -$6.13 | -$7.96 |
| Gross profit | $25.20 | $42.93 | $41.50 | $62.95 | $88.37 |
| G&A expenses | -$9.00 | -$20.10 | -$23.40 | -$22.46 | -$26.95 |
| EBITDA | $16.20 | $22.83 | $18.10 | $40.49 | $61.42 |
| D&A | -$2.70 | -$4.14 | -$7.27 | -$7.81 | -$11.71 |
| EBIT | $13.50 | $18.69 | $10.83 | $32.68 | $49.71 |
| Interest expense | -$2.40 | -$1.52 | -$1.95 | -$2.19 | -$3.07 |
| EBT | $11.10 | $17.17 | $8.88 | $30.48 | $46.64 |
| Other items | -$7.40 | -$13.58 | $92.30 | -$20.60 | -$15.36 |
| Net income | $3.60 | $3.59 | $101.18 | $9.89 | $31.28 |
| EPS ($) | $0.07 | $0.07 | $1.96 | $0.18 | $0.56 |
| Adj. Net Income | $3.60 | $9.31 | $2.25 | $22.39 | $43.78 |
| Adj. EPS | $0.07 | $0.18 | $0.04 | $0.40 | $0.78 |
| Cash Flows ($M) | 2023 | 2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|---|
| Cash flow from operations (CFO) | |||||
| Net income / (loss) | $3.59 | $3.56 | $101.18 | $9.89 | $31.28 |
| D&A | $2.71 | $4.14 | $7.27 | $7.81 | $11.71 |
| Working capital & other adjustments | $8.62 | $11.43 | -$94.66 | -$4.70 | -$5.90 |
| CFO | $14.92 | $19.13 | $13.79 | $12.99 | $37.09 |
| Cash flow from investing (CFI) | |||||
| Capital expenditures | -$5.63 | -$10.07 | -$12.39 | -$17.50 | -$30.00 |
| CFI | -$5.63 | -$10.07 | -$12.39 | -$17.50 | -$30.00 |
| Cash flow from financing (CFF) | |||||
| Debt proceeds | — | — | $4.00 | $8.72 | $0.00 |
| Debt repayments & lease payments | -$5.83 | -$9.65 | -$3.21 | ||
| Other financing activities | -$3.24 | — | $0.01 | ||
| CFF | -$9.07 | -$9.65 | $0.80 | $8.72 | $0.00 |
| Balance Sheet ($M) | 2023 | 2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|---|
| Cash & Equivalents | $0.30 | $0.70 | $1.89 | $6.10 | $13.19 |
| A/R & other current assets | $1.70 | $5.10 | $10.37 | $16.60 | $26.55 |
| Inventories | $2.30 | $3.20 | $3.91 | $7.43 | $8.92 |
| Total current assets | $4.30 | $9.00 | $16.17 | $30.12 | $48.66 |
| PP&E & others | $36.60 | $42.10 | $46.62 | $56.32 | $74.60 |
| Total assets | $41.00 | $51.00 | $62.79 | $86.44 | $123.26 |
| A/P & other current liabilities | $38.90 | $44.90 | $50.39 | $55.43 | $60.97 |
| Current borrowings | $2.40 | $1.10 | $3.18 | $5.60 | $5.60 |
| Total current liabilities | $41.30 | $46.00 | $53.57 | $61.03 | $66.57 |
| Long-term borrowings | $0.00 | $1.40 | $2.01 | $8.30 | $8.30 |
| Other long-term liabilities | $28.00 | $34.60 | $46.49 | $46.49 | $46.49 |
| Total liabilities | $69.30 | $82.00 | $102.07 | $115.83 | $121.37 |
| Shareholders’ equity / (deficit) | -$28.30 | -$30.90 | -$39.28 | -$29.39 | $1.89 |
| Total SE & Liabilities | $41.00 | $51.00 | $62.79 | $86.44 | $123.26 |
Sid Rajeev, B.Tech, MBA, CFA — Head of Research, Fundamental Research Corp.
Nina Rose Coderis, B.Sc (Geology) — Equity Analyst, Fundamental Research Corp.
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Buy – Fair value is 12% above the current market price; or risk and reward is favorable
Hold – Fair value is between 5% to 12% above the current market price
Sell – Fair value is 5% above, or less, than the current market value; or risk and reward is unfavorable
Suspended or Rating N/A— Coverage and ratings suspended until more information can be obtained from the company regarding recent events.
1 (Low Risk) - The company operates in an industry where it has a strong position (for example a monopoly, high market share etc.) or operates in a regulated industry. The future outlook is stable or positive for the industry. The company generates positive free cash flow and has a history of profitability. The capital structure is conservative with little or no debt.
2 (Below Average Risk) - The company operates in an industry where the fundamentals and outlook are positive. The industry and company are relatively less sensitive to systematic risk than companies with a Risk Rating of 3. The company has a history of profitability and has demonstrated its ability to generate positive free cash flows (though current free cash flow may be negative due to capital investment). The company’s capital structure is conservative with little to modest use of debt.
3 (Average Risk) - The company operates in an industry that has average sensitivity to systematic risk. The industry may be cyclical. Profits and cash flow are sensitive to economic factors although the company has demonstrated its ability to generate positive earnings and cash flow. Debt use is in line with industry averages, and coverage ratios are sufficient.
4 (Speculative) - The company has little or no history of generating earnings or cash flow. Debt use is higher. These companies may be in start-up mode or in a turnaround situation. These companies should be considered speculative.
5 (Highly Speculative) - The company has no history of generating earnings or cash flow. They may operate in a new industry with new, and unproven products. Products may be at the development stage, testing, or seeking regulatory approval. These companies may run into liquidity issues and may rely on external funding. These stocks are considered highly speculative.
Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE.
Analyst Certification: The views expressed in this report accurately reflect the personal views of the analyst, and no part of their compensation was, is, or will be directly or indirectly related to the specific recommendation or views expressed.
Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The analyst and Fundamental Research Corp. “FRC” does not own any shares of the subject company, does not make a market or offer shares for sale of the subject company, and does not have any investment banking business with the subject company. Fees ranging between $25,000 and $35,000 have been paid to FRC by Namib Minerals to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. FRC takes steps to mitigate conflicts including setting fees in advance and utilizing analysts who must abide by CFA Institute Code of Ethics and Standards of Professional Conduct. Additionally, analysts may not trade in any security under coverage. Our full editorial control of all research, timing of release of the reports, and release of liability for negative reports are protected contractually. The issuer has agreed to a minimum coverage term and coverage cannot be unilaterally terminated. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time.
The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (22%).
This report contains "forward looking" statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company's products/services in the marketplace; acceptance in the marketplace of the Company's new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company's periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. A report initiating coverage will most often be updated quarterly while a report issuing a rating may have no further or less frequent updates because the subject company is likely to be in earlier stages where nothing material may occur quarter to quarter.
Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.