
We are reiterating our BUY rating, and adjusting our fair value estimate from $0.98 to $1.09/share. MQM offers exposure to a diversified portfolio of critical minerals and gold projects, anchored by the potentially significant Lac Otelnuk iron ore project.
A Sleeping Giant in Canada’s Critical Minerals Sector
Paused · 15:01 left · FRC · read by an AI voice
Disclosure: MetalQuest Mining Inc. has paid FRC a fee for research coverage and distribution of reports. This fee creates a potential conflict of interest which readers should consider. See last page for other important disclosures, rating, and risk definitions.
All figures are in C$, except for commodity prices.
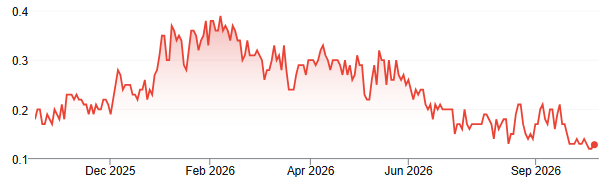
Price and Volume (1-year)
| YTD | 12M | |
|---|---|---|
| MQM | -60% | -34% |
| TSXV | -17% | -13% |
| SETM* | -18% | -4% |
| Key Financial Data (FYE - Jan 31) | |
|---|---|
| (C$) | FY2027 (6M) |
| Cash | $1,061,472 |
| Working Capital | $4,057,467 |
| Mineral Assets | $1,002,215 |
| Total Assets | $5,228,517 |
| Net Income (Loss) | -$303,973 |
| EPS | -$0.01 |
Diversified Gold and Critical Metals Portfolio: Since our previous report in February 2026, the company has added two gold projects, applied for a magnesium mining lease, and expanded its Ring of Fire land package.
The following sections provide an overview of MQM’s projects.
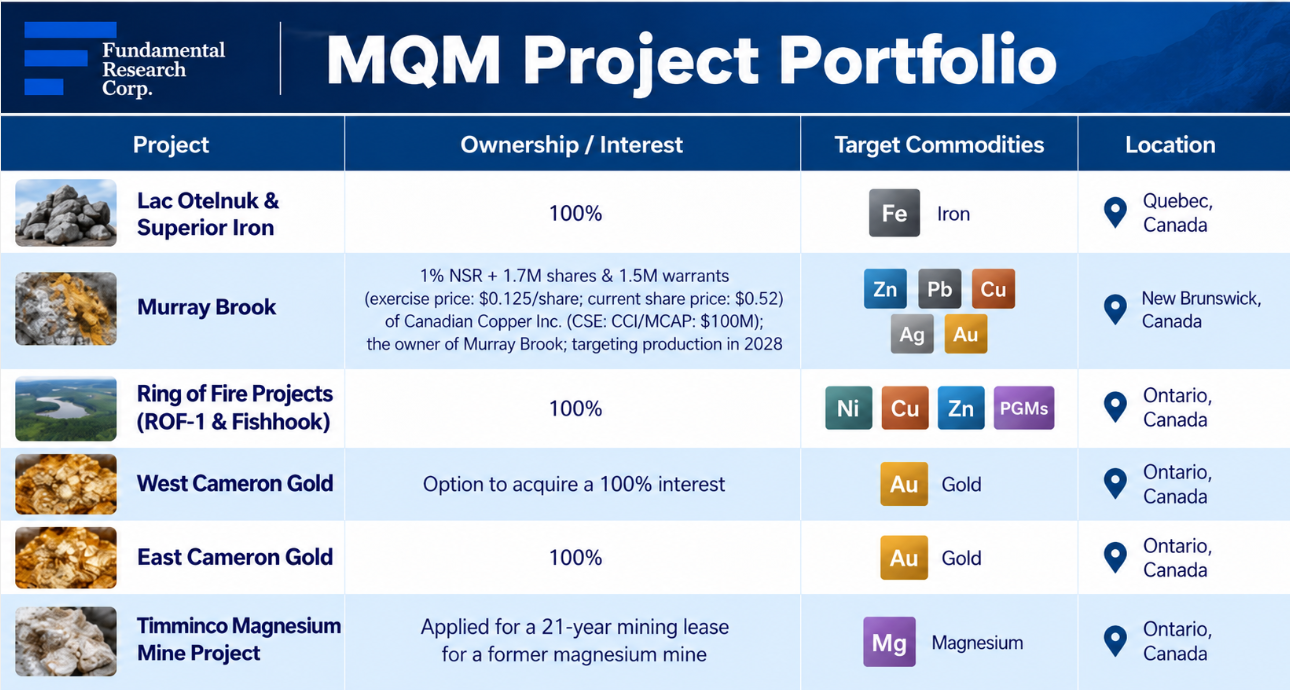
| Project | Ownership / Interest | Target Commodities | Location |
|---|---|---|---|
| Lac Otelnuk & Superior Iron | 100% | Fe Iron | Quebec, Canada |
| Murray Brook | 1% NSR + 1.7M shares & 1.5M warrants (exercise price: $0.125/share; current share price: $0.52) of Canadian Copper Inc. (CSE: CCI/MCAP: $100M); the owner of Murray Brook; targeting production in 2028 | Zn Pb Cu Ag Au | New Brunswick, Canada |
| Ring of Fire Projects (ROF-1 & Fishhook) | 100% | Ni Cu Zn PGMs | Ontario, Canada |
| West Cameron Gold | Option to acquire a 100% interest | Au Gold | Ontario, Canada |
| East Cameron Gold | 100% | Au Gold | Ontario, Canada |
| Timminco Magnesium Mine Project | Applied for a 21-year mining lease for a former magnesium mine | Mg Magnesium | Ontario, Canada |
Lac Otelnuk is MQM’s flagship and most advanced project. The 1,100 km-long Labrador Trough produces 100% of Canada’s iron ore. The project is located 165 km northwest of Schefferville, benefiting from access to rail transportation, port facilities, road infrastructure, and low-cost hydroelectric power.
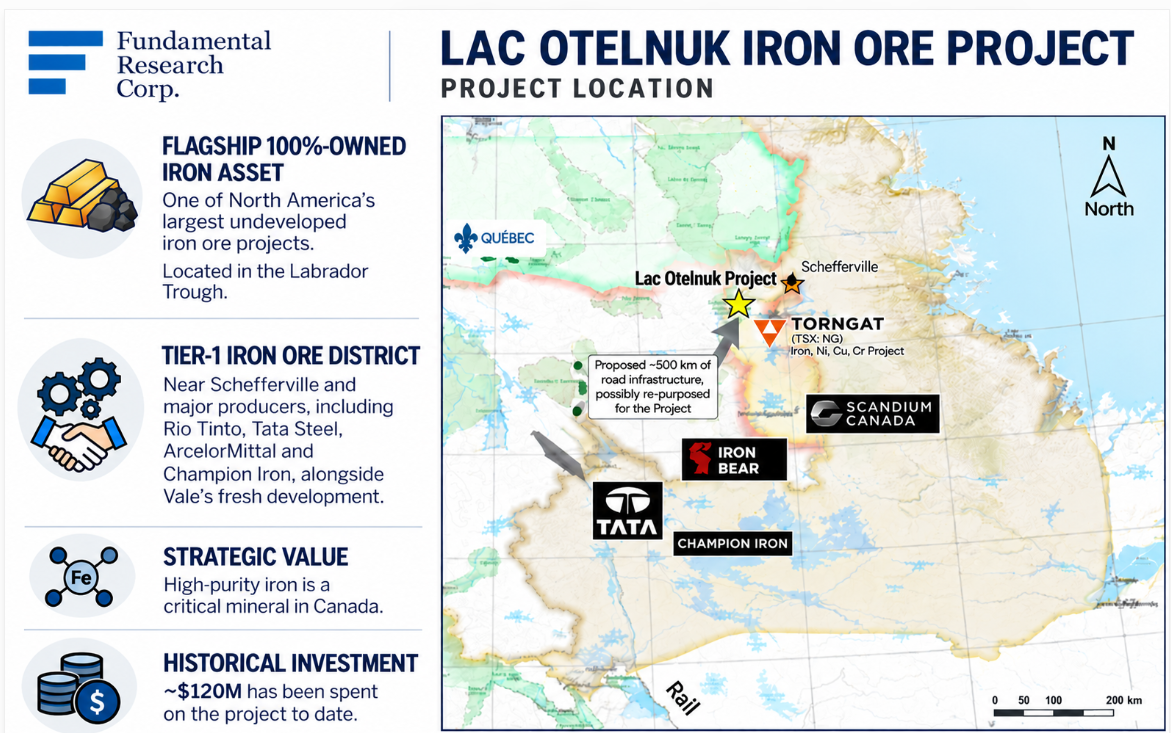
Lac Otelnuk hosts a large, near-surface iron (Fe) deposit. Metallurgical (recovery) tests indicate potential to produce 68% Fe iron, well above the ~62% standard benchmark, potentially qualifying for premium pricing.
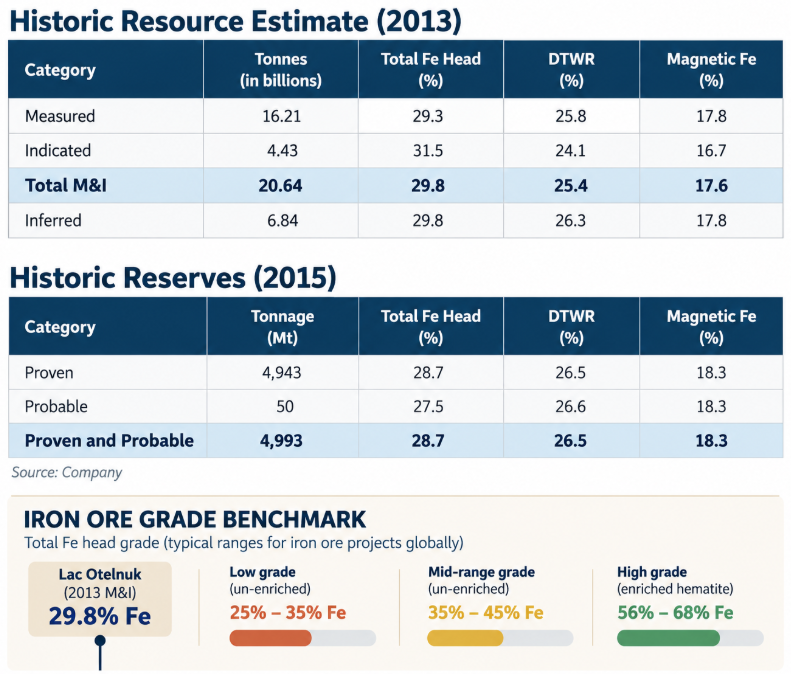
Historic Resource Estimate (2013)
| Category | Tonnes (in billions) | Total Fe Head (%) | DTWR (%) | Magnetic Fe (%) |
|---|---|---|---|---|
| Measured | 16.21 | 29.3 | 25.8 | 17.8 |
| Indicated | 4.43 | 31.5 | 24.1 | 16.7 |
| Total M&I | 20.64 | 29.8 | 25.4 | 17.6 |
| Inferred | 6.84 | 29.8 | 26.3 | 17.8 |
Historic Reserves (2015)
| Category | Tonnage (Mt) | Total Fe Head (%) | DTWR (%) | Magnetic Fe (%) |
|---|---|---|---|---|
| Proven | 4,943 | 28.7 | 26.5 | 18.3 |
| Probable | 50 | 27.5 | 26.6 | 18.3 |
| Proven and Probable | 4,993 | 28.7 | 26.5 | 18.3 |
A historical 2015 feasibility study valued the project at $7.4B, based on $105/t iron ore vs. $91/t spot.
2015 FS Highlights (All figures in US$)
| Project Parameters | Open-Pit / 30% Equity: 70% Debt |
|---|---|
| Pre Tax NPV8%, US$M | US$10,388 M |
| Pre Tax IRR | 15.8% |
| After Tax NPV8% | US$5,240 M |
| After Tax IRR | 13.0% |
| Payback, AT | 7.3 years |
| Initial CAPEX (US$M) | US$9,384 M (Phase 1) and US$4,802 M (Phase 2) |
| LOM Annual Production, Mt | 30 Mt (Phase 1) and 50 Mt (Phase 2) |
| OPEX, US$/t concentrate | US$34.21/t (Phase 1) and US$31.12/t (Phase 2) |
| Project Life | 30 years |
| After Tax Cash Flow, US$M | US$47,674 M |
MQM recently completed fieldwork to review historical data and collect ~550 kg of drill core samples for testing. A 26-week metallurgical program is underway at COREM, a mineral-processing research centre, to assess the potential of producing high-grade, low-silica iron suitable for lower-carbon steelmaking, with support from AtkinsRéalis, an engineering and consulting firm. AtkinsRéalis has also developed a technical plan to update the mine design, financial models, and environmental standards.
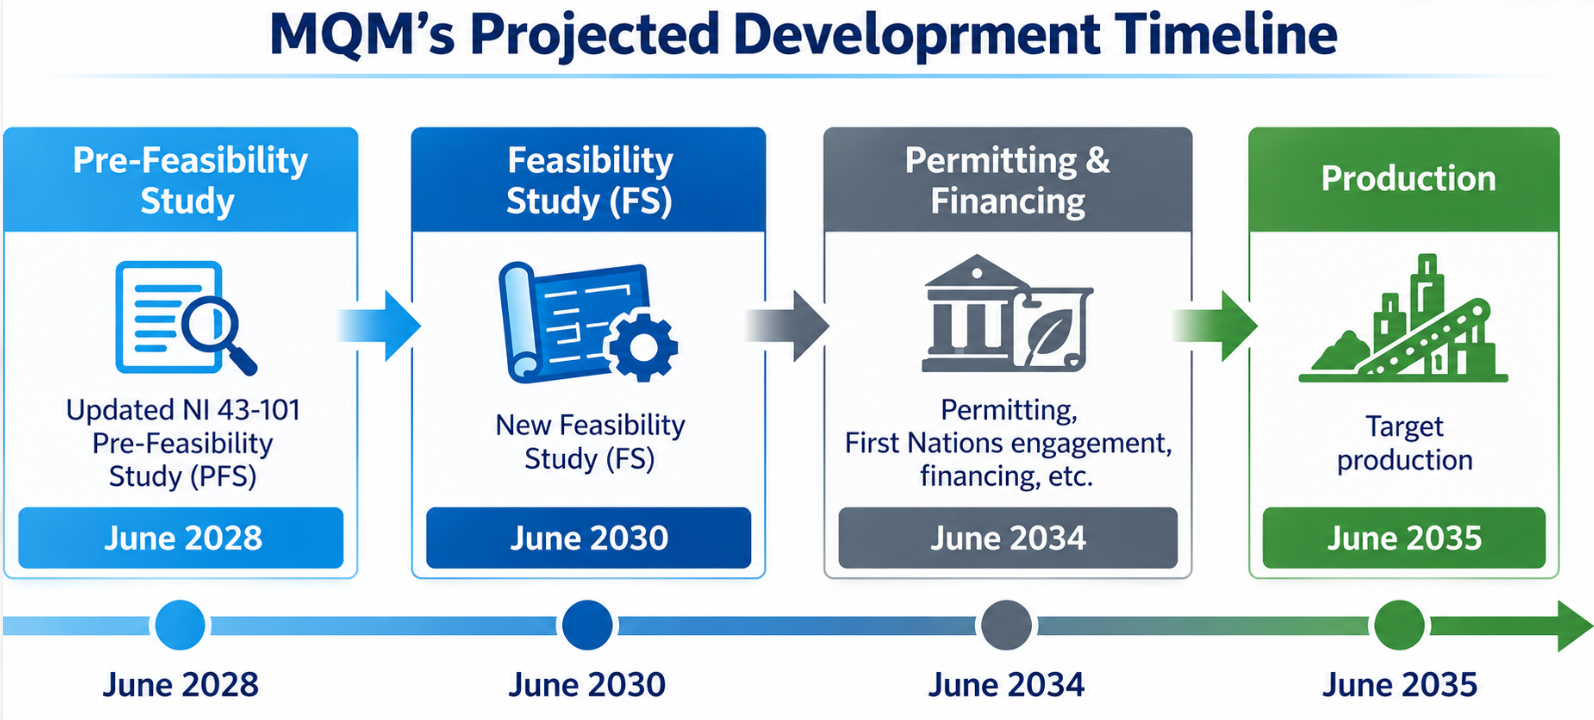
MQM is seeking a strategic partner to finance and advance the project, while maintaining engagement with First Nations communities. To attract strategic partners, MQM is updating the 2015 feasibility study, targeting completion by 2028, with potential production within 10 years.
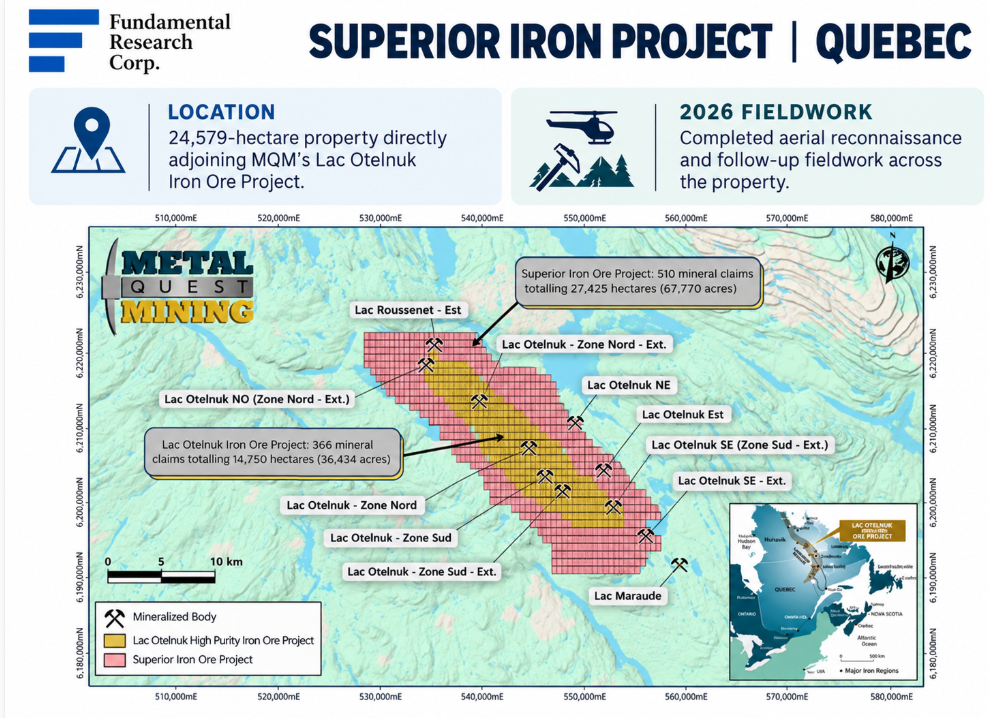
Superior Iron is an early-stage exploration asset, directly adjoining the Lac Otelnuk project. MQM is currently conducting geophysical, and environmental studies, with an independent NI 43-101 report targeted by year-end.
In March 2026, MQM entered into an option to acquire a 100% interest in the West Cameron gold project in the Kenora Mining District. The company subsequently expanded its land position by staking the East Cameron gold project.
Both projects are located in an underexplored, but increasingly active gold region. ~10 km from Seva Mining’s Cameron Lake gold project, which hosts 1.2 Moz of gold. Targeting orogenic gold deposits, known for their potential for high grades.
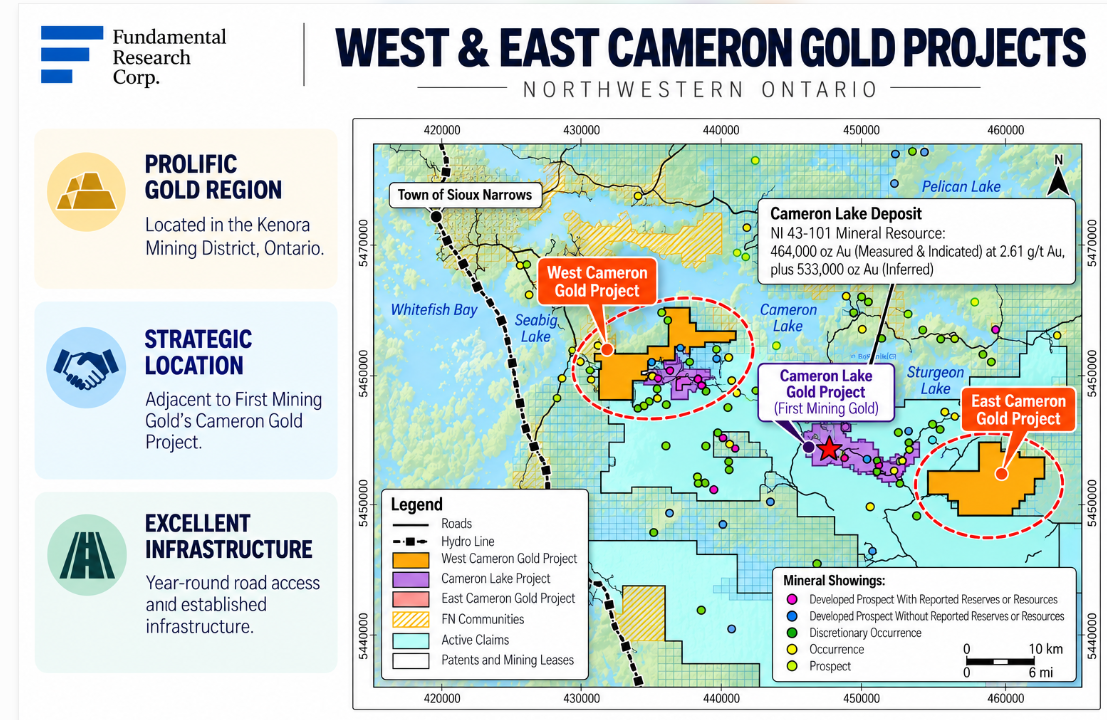
Both projects follow the Cameron Lake Fault, which may have channelled gold-bearing fluids, creating a favourable setting for gold exploration. Ongoing soil sampling at West Cameron aims to generate drill targets.
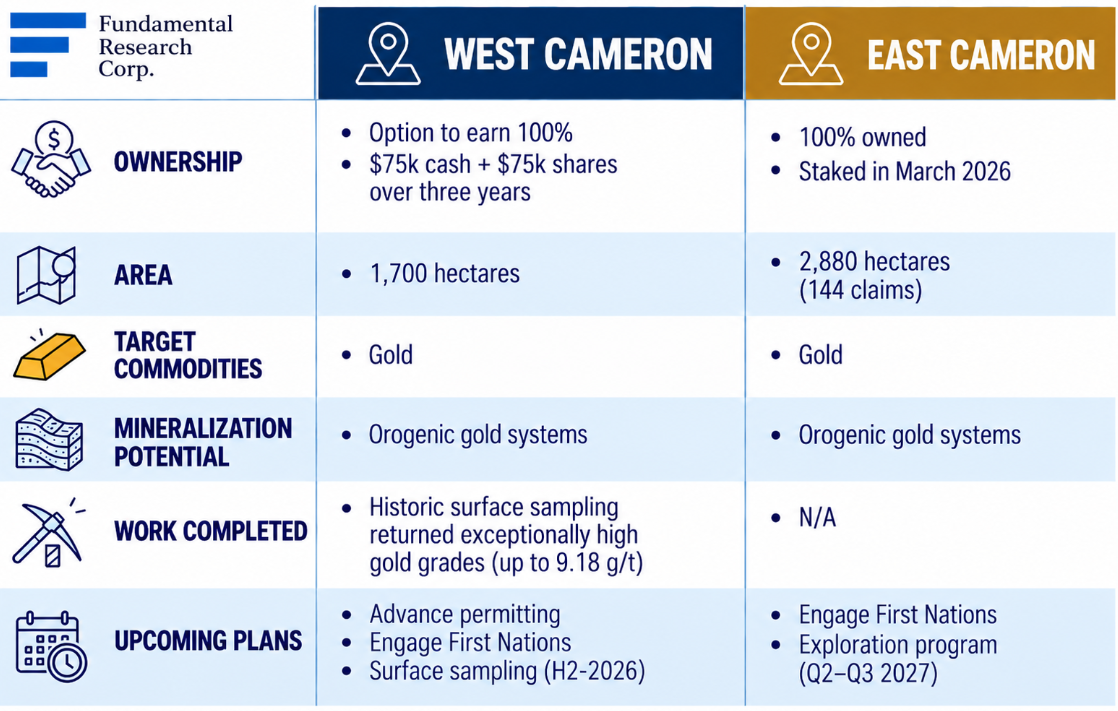
| WEST CAMERON | EAST CAMERON | |
|---|---|---|
| OWNERSHIP | Option to earn 100% $75k cash + $75k shares over three years |
100% owned Staked in March 2026 |
| AREA | 1,700 hectares | 2,880 hectares (144 claims) |
| TARGET COMMODITIES | Gold | Gold |
| MINERALIZATION POTENTIAL | Orogenic gold systems | Orogenic gold systems |
| WORK COMPLETED | Historic surface sampling returned exceptionally high gold grades (up to 9.18 g/t) | N/A |
| UPCOMING PLANS | Advance permitting Engage First Nations Surface sampling (H2-2026) |
Engage First Nations Exploration program (Q2–Q3 2027) |
MQM owns two polymetallic projects in the Ring of Fire: ROF-1 and Fishhook. The company recently expanded Fishhook by staking 294 additional claims covering ~5,880 hectares (~14,500 acres).
Both projects have seen limited historical exploration. ROF-1 targets nickel, copper and PGMs, while Fishhook is prospective for copper, zinc, nickel, and PGMs. ROF-1 lies ~10 km from the advanced-stage Eagle’s Nest nickel-copper-PGE deposit owned by Wyloo Metals, highlighting its location within a prospective critical-minerals district.
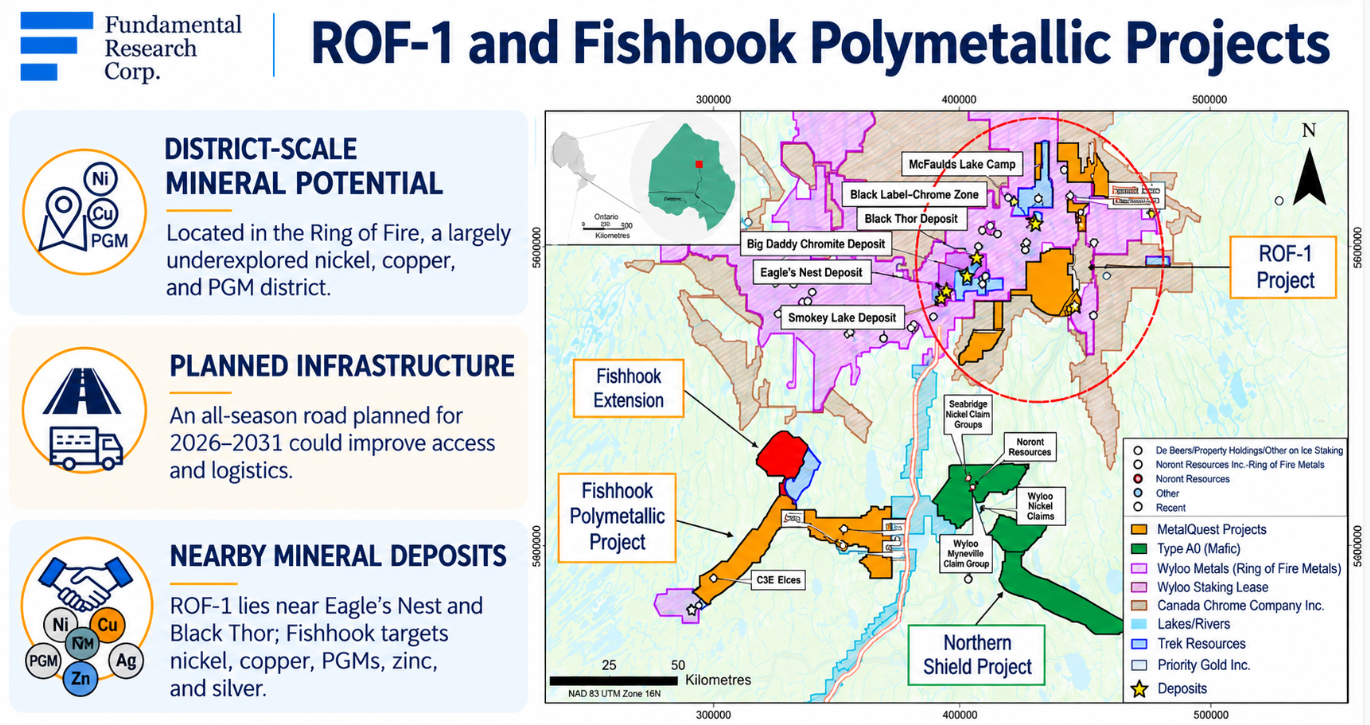
Ontario is advancing all-season road access to the Ring of Fire, potentially improving access for exploration and future development. The company plans early-stage exploration, including data compilation, mapping, geochemical surveys, and drilling.
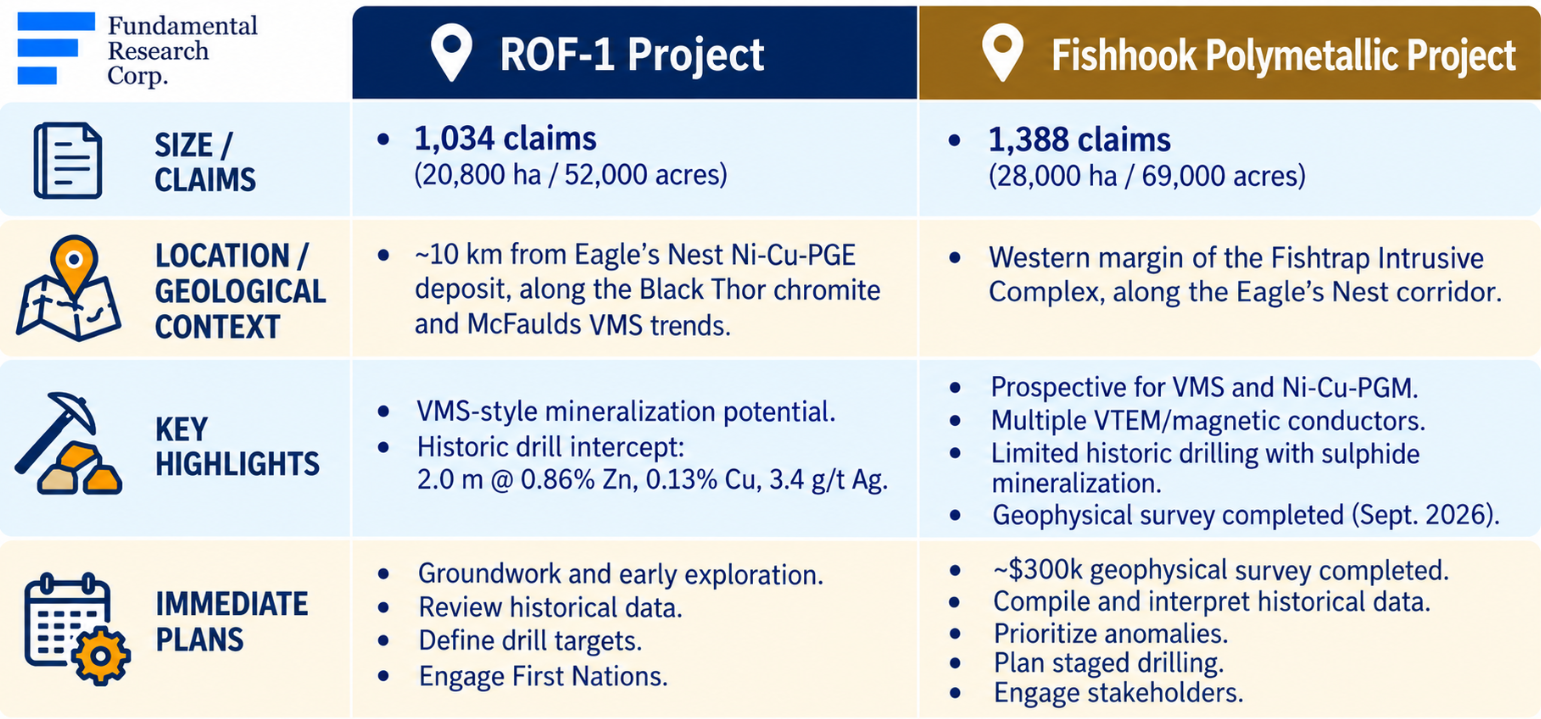
| ROF-1 Project | Fishhook Polymetallic Project | |
|---|---|---|
| SIZE / CLAIMS | 1,034 claims (20,800 ha / 52,000 acres) | 1,388 claims (28,000 ha / 69,000 acres) |
| LOCATION / GEOLOGICAL CONTEXT | ~10 km from Eagle’s Nest Ni-Cu-PGE deposit, along the Black Thor chromite and McFaulds VMS trends. | Western margin of the Fishtrap Intrusive Complex, along the Eagle’s Nest corridor. |
| KEY HIGHLIGHTS | VMS-style mineralization potential. Historic drill intercept: 2.0 m @ 0.86% Zn, 0.13% Cu, 3.4 g/t Ag. |
Prospective for VMS and Ni-Cu-PGM. Multiple VTEM/magnetic conductors. Limited historic drilling with sulphide mineralization. Geophysical survey completed (Sept. 2026). |
| IMMEDIATE PLANS | Groundwork and early exploration. Review historical data. Define drill targets. Engage First Nations. |
~$300k geophysical survey completed. Compile and interpret historical data. Prioritize anomalies. Plan staged drilling. Engage stakeholders. |
Overall, we believe these projects allow MQM low-cost entry into a district with renewed exploration activity, amid growing government interest in critical minerals.
MQM holds a $1.5M equity stake in CCI, plus a 1% NSR royalty on Murray Brook. Third-party financing commitments support project advancement, and validate Murray Brook’s potential.
Specifically, MQM holds ~1.7M shares and ~1.5M warrants (exercise price: $0.125; current share price: $0.52) in Canadian Copper Inc. (MCAP: $100M), representing a current market value of $1.5M.
MQM also retains a 1% NSR royalty on CCI’s Murray Brook project in New Brunswick’s Bathurst Mining District. Murray Brook hosts a large, low-grade, open-pit polymetallic deposit. A recent Preliminary Economic Assessment outlined an after-tax NPV7% of $171M, and an IRR of 36%, based on $4.25/lb copper (spot: $6.40/lb), with a relatively low initial CAPEX of $64M (metal prices are in US$).
In April 2026, CCI secured commitments for up to $96M in project financing from OR Royalties, a leading precious-metals royalty and streaming company, and Ocean Partners, a global metals trading and financing firm. We believe support from established industry financiers validates the project’s potential, supports its advancement, and could enhance the value of MQM’s equity and royalty interests.
Magnesium is designated as a critical mineral by the U.S., EU, and Canada, with North America relying heavily on imports. China accounts for 85%–90% of global primary magnesium production, while North America lacks primary magnesium production, underscoring the strategic importance of developing domestic sources.
Located in mining-friendly Ontario, the project benefits from highway and power access and sits directly across from an operating magnesium and aluminum casting facility. Western nations are seeking to expand domestic production to reduce reliance on China’s dominant supply position. MQM plans data validation, drilling, and an initial resource estimate.
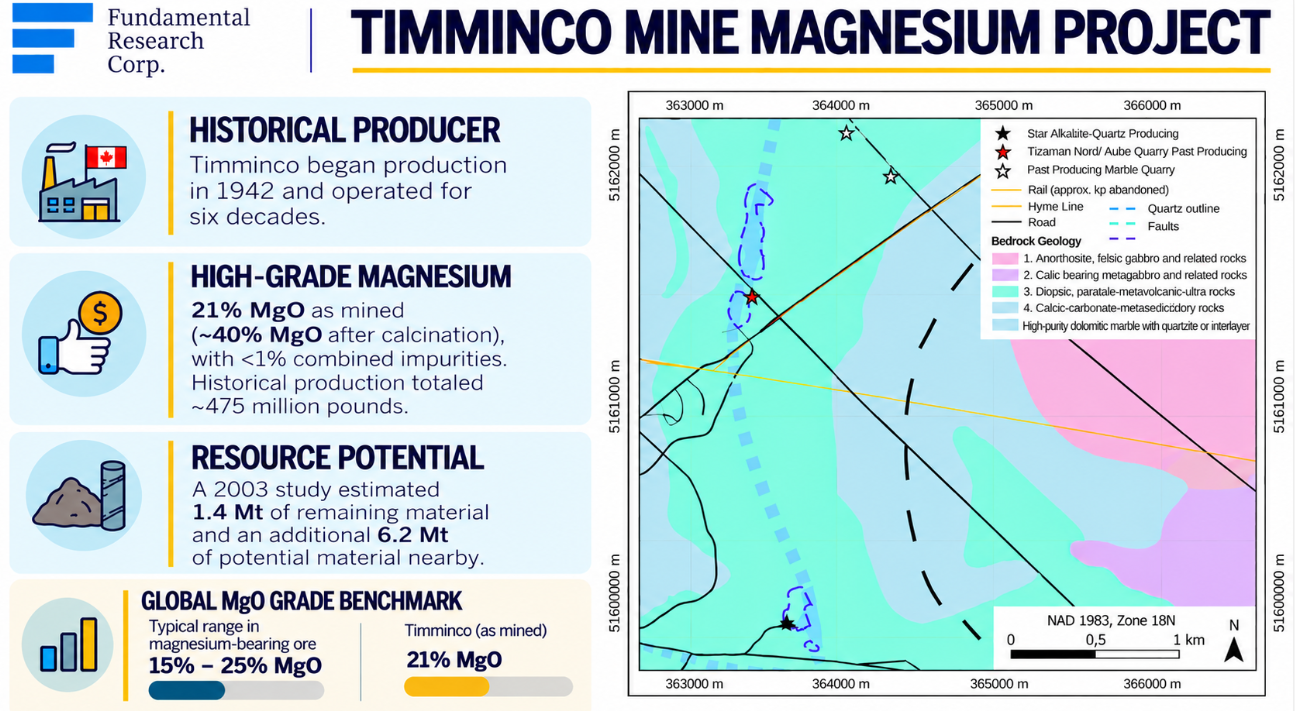
MQM has applied for a 21-year mining lease over the former Timminco (Haley Station) magnesium mine in Ontario. If secured, we believe the property would diversify MQM’s portfolio and provide exposure to a critical mineral for which North America remains heavily import-dependent. However, the project’s economic potential has yet to be assessed.
MQM has a healthy balance sheet, with $4M in working capital, and no debt.
| (in C$) - YE: Jan 31st | FY2027 (6M) |
|---|---|
| Cash | $1,061,472 |
| Working Capital | $4,057,467 |
| Current Ratio | 25.03 |
| Monthly Burn Rate (G&A) | -$107,751 |
| Cash Spent on Properties | -$486,878 |
| Cash from Financing Activities | $280,371 |
Additionally, MQM can raise up to $0.55M from in-the-money options and warrants.
| Options | # | Exercise Price | Amount |
|---|---|---|---|
| Total | 6,410,000 | $0.23 | $1,476,750 |
| In-the-Money | 850,000 | $0.10 | $85,000 |
| Warrants | # | Exercise Price | Amount |
|---|---|---|---|
| Total | 10,559,478 | $0.27 | $2,817,923 |
| In-the-Money | 4,686,229 | $0.10 | $468,623 |
MQM’s EV/Resource and EV/AT-NPV multiples are materially below those of comparable iron ore juniors, suggesting the market undervalues Lac Otelnuk.
| Joyce Lake | Hopes Advance | Zanaga | Lac Otelnuk | |
|---|---|---|---|---|
| Owner | Century Global / TSX: CNT (91.6% interest) | Oceanic Iron Ore / TSXV: FEO | Zanaga Iron Ore/ AIM: ZIOC | MetalQuest Mining / TSXV: MQM |
| Location | Canada | Canada | Republic of Congo | Canada |
| Resource (Contained Iron) | M&I - 14 Mt at 58.6% Fe Inferred - 515 Kt at 62.1% Fe |
M&I - 516 Mt at 32.1% Fe Inferred - 82 Mt at 32.5% Fe |
M&I - 2.4 Bt at 32.1% Fe Inferred - 651 Kt at 31.0% Fe |
M&I - 3.6 Bt at 17.6% Fe Inferred - 1.2 Bt at 17.8% Fe |
| Stage | FS | PEA | FS | FS |
| Mine Life | 7 years | 28 years | 30 years | 30 years |
| CAPEX | $270M | US$1.2B | Phase 1: US$2.2B Phase 2: US$2.5B |
Phase 1: US$9.3B Phase 2: US$4.8B |
| Annual Production | 2.5 Mtpa | 5 Mtpa | 30 Mtpa | Phase 1: 30 Mtpa Phase 2: 50 Mtpa |
| AT-NPV | $185M (8%) | US$2.3B (8%) | US$1.3B (10%) | US$5.2B (8%) |
| AT - IRR | 20% | 22% | 18% | 13% |
| Iron Price | US$125/t | US$101/t | US$60//t | US$105/t |
| Enterprise Value (EV)- $M | $4 | $121 | $51 | $2.00 |
| EV/Contained Resource ($/t) | $0.31 | $0.22 | $0.02 | $0.0005 |
| EV/AT-NPV8% | 2.4% | 3.9% | 2.9% | 0.03% |
We made no material changes to our valuation on the Lac Otelnuk project. However, our per-share valuation increased from $0.86 to $0.92, reflecting a lower diluted share count, due to fewer in-the-money options and warrants following the recent share price decline.
| DCF Valuation - Lac Otelnuk | |
|---|---|
| Operating Life (years) | 30 |
| Annual Production (concentrates) | 30 Mt (Years 1-10) / 50 Mt (Years 11-30) |
| LT Average Iron Ore Price (US$/t) | $110 |
| Operating Cost (LOM) in US$/t | $38 |
| Initial CAPEX -US$B | $11.60 |
| Discount Rate | 12.5% |
| After-Tax Net Asset Value ($M) | $45,746,288 |
| Fair Value/Share | $0.92 |
Similarly, we raised our long-term copper price forecast from $3.75/lb to $4.25/lb; as a result, our valuation of the NSR on the Murray Brook project increased from $0.08 to $0.09/share.
| NSR Valuation - Murray Brook | |
|---|---|
| Operating Life (years) | 13 |
| Annual Copper Equiv. Production (Mlb) | 30 |
| LT Average Price of Cu (US$/lb) | $4.25 |
| Discount Rate | 15% |
| After-Tax Net Asset Value (C$M) | $4,558,853 |
| Fair Value per Share (C$) | $0.09 |
Using a sum-of-the-parts valuation, our fair value estimate increased from $0.98 to $1.09/share. Given their early-stage nature, we are not currently assigning a value to the company’s other projects.
| Valuation Summary | Shares | Value/Share |
|---|---|---|
| Lac Otelnuk (iron) | $45,746,288 | $0.92 |
| Murray Brook (polymetallic) - 1% NSR | $4,558,853 | $0.09 |
| Superior Iron Project | - | - |
| Ring of Fire Projects | - | - |
| West Cameron & East Cameron Gold Projects | - | - |
| Working Capital | $4,057,467 | $0.08 |
| Fair Value | $54,362,609 | $1.09 |
We are reiterating our BUY rating, and adjusting our fair value estimate from $0.98 to $1.09/share. MQM offers exposure to a diversified portfolio of critical minerals and gold projects, anchored by the potentially significant Lac Otelnuk iron ore project. Despite recent share price weakness, we believe the market continues to underappreciate the portfolio’s potential. With a healthy balance sheet, multiple exploration catalysts, and opportunities to advance projects through strategic partnerships, we believe MQM offers significant upside potential.
We are maintaining our risk rating of 5 (Highly Speculative). We believe the company is subject to the following risks:
Sid Rajeev, B.Tech, MBA, CFA — Head of Research, Fundamental Research Corp.
Nina Rose Coderis, B.Sc (Geology) — Equity Analyst, Fundamental Research Corp.
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Buy – Fair value is 12% above the current market price; or risk and reward is favorable
Hold – Fair value is between 5% to 12% above the current market price
Sell – Fair value is 5% above, or less, than the current market value; or risk and reward is unfavorable
Suspended or Rating N/A— Coverage and ratings suspended until more information can be obtained from the company regarding recent events.
1 (Low Risk) - The company operates in an industry where it has a strong position (for example a monopoly, high market share etc.) or operates in a regulated industry. The future outlook is stable or positive for the industry. The company generates positive free cash flow and has a history of profitability. The capital structure is conservative with little or no debt.
2 (Below Average Risk) - The company operates in an industry where the fundamentals and outlook are positive. The industry and company are relatively less sensitive to systematic risk than companies with a Risk Rating of 3. The company has a history of profitability and has demonstrated its ability to generate positive free cash flows (though current free cash flow may be negative due to capital investment). The company’s capital structure is conservative with little to modest use of debt.
3 (Average Risk) - The company operates in an industry that has average sensitivity to systematic risk. The industry may be cyclical. Profits and cash flow are sensitive to economic factors although the company has demonstrated its ability to generate positive earnings and cash flow. Debt use is in line with industry averages, and coverage ratios are sufficient.
4 (Speculative) - The company has little or no history of generating earnings or cash flow. Debt use is higher. These companies may be in start-up mode or in a turnaround situation. These companies should be considered speculative.
5 (Highly Speculative) - The company has no history of generating earnings or cash flow. They may operate in a new industry with new, and unproven products. Products may be at the development stage, testing, or seeking regulatory approval. These companies may run into liquidity issues and may rely on external funding. These stocks are considered highly speculative.
Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE.
Analyst Certification: The views expressed in this report accurately reflect the personal views of the analyst, and no part of their compensation was, is, or will be directly or indirectly related to the specific recommendation or views expressed.
Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The analyst and Fundamental Research Corp. “FRC” does not own any shares of the subject company, does not make a market or offer shares for sale of the subject company, and does not have any investment banking business with the subject company. Fees ranging between $20,000 and $30,000 have been paid to FRC by MetalQuest Mining to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. FRC takes steps to mitigate conflicts including setting fees in advance and utilizing analysts who must abide by CFA Institute Code of Ethics and Standards of Professional Conduct. Additionally, analysts may not trade in any security under coverage. Our full editorial control of all research, timing of release of the reports, and release of liability for negative reports are protected contractually. The issuer has agreed to a minimum coverage term and coverage cannot be unilaterally terminated. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time.
The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (22%).
This report contains "forward looking" statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company's products/services in the marketplace; acceptance in the marketplace of the Company's new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company's periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. A report initiating coverage will most often be updated quarterly while a report issuing a rating may have no further or less frequent updates because the subject company is likely to be in earlier stages where nothing material may occur quarter to quarter.
Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.
Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.