
We reiterate our BUY rating, and raise our fair value estimate from $0.32 to $0.37/share. The Wedge project offers significant exploration upside, supported by high-grade drill results, and its location in the established BMC.
Shares Surge as Drilling Reveals Bigger Potential
Paused · 11:43 left · FRC · read by an AI voice
Disclosure: Nine Mile Metals Ltd. has paid FRC a fee for research coverage and distribution of reports. This fee creates a potential conflict of interest which readers should consider. See last page for other important disclosures, rating, and risk definitions.
All figures in C$ unless otherwise specified.
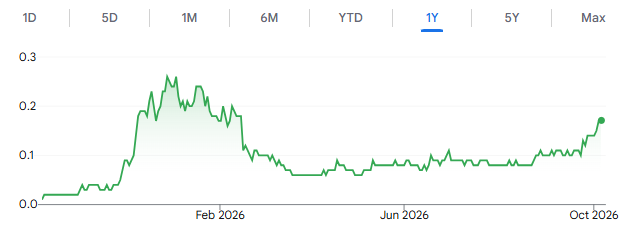
Price and Volume (1-year)
| YTD | 12M | |
|---|---|---|
| NINE | -50% | 500% |
| CSE | -17% | -25% |
| SETM* | -13% | -12% |
| Key Financial Data (FYE - Sep 30) | |
|---|---|
| C$ | Q3-FY2026 |
| Cash | $4,917,772 |
| Working Capital | $4,982,397 |
| Mineral Assets/PP&E | $5,006,198 |
| Total Assets | $10,269,442 |
| Adj. Net Income (Loss) | -$2,480,195 |
| Adj. EPS | -$0.01 |
* Qualified Person: Gary Lohman, B.Sc., P.Geo., VP Exploration of Nine Mile Metals.
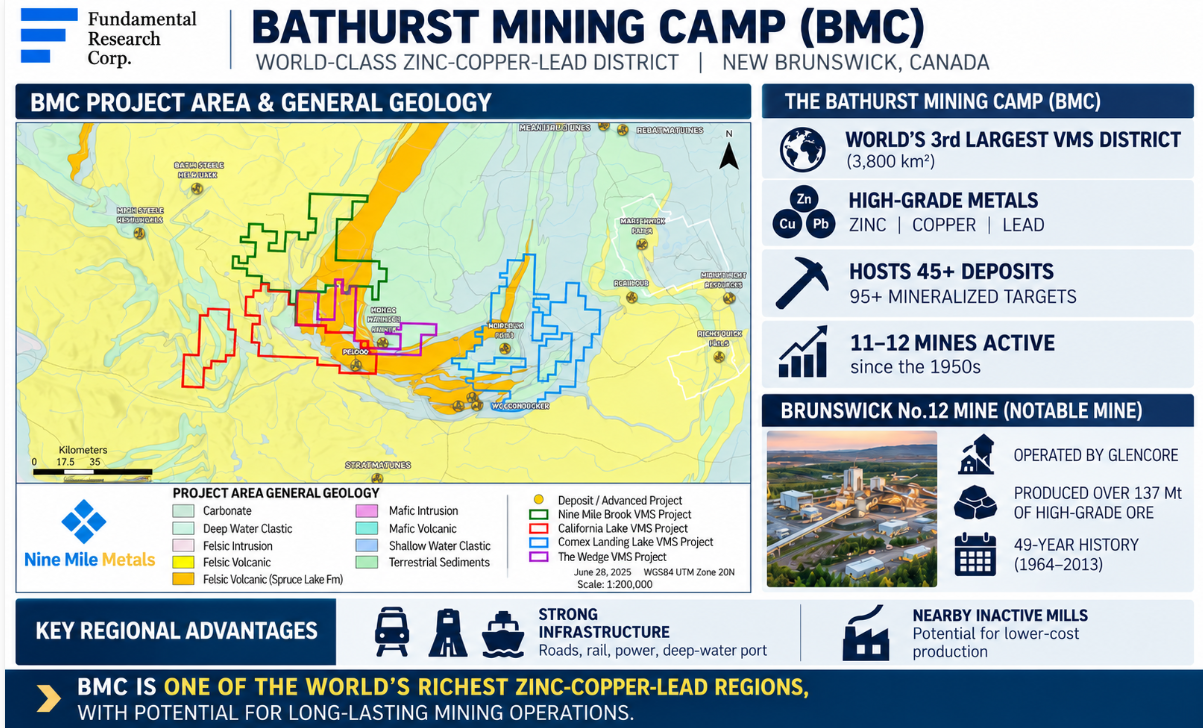
NINE has four critical mineral projects spanning 137 km² in the Bathurst Mining Camp (BMC), demonstrating strong management conviction in the region.
| Projects | Target Commodities | Status |
|---|---|---|
| Wedge (36 sq. km) | Copper, Lead, Zinc, Silver and Gold | A former copper-lead-zinc producer; surface sampling, geophysics, and drilling completed |
| Nine Mike Brook (50 sq. km) | Copper, Lead, Zinc, Silver and Gold | Bulk sampling, geophysics, and drilling completed |
| California Lake (36 sq. km) | Copper, Lead, Zinc, Silver and Gold | Geophysics and drilling completed |
| Canoe Landing Lake (15 sq. km) | Copper, Lead, Zinc, Silver and Gold | Geophysics completed |
The 3,800 km² BMC is one of the world’s largest VMS districts, known for high-grade zinc, copper, and lead deposits that often occur in clusters. Existing mills in the region could potentially enable NINE to reach production faster and at lower cost, without building its own processing facility.
The main focus of this report is the recent drilling results from the Wedge project, which continues to demonstrate the potential to expand mineralization well beyond the historic mine. At its other flagship project, Nine Mile Brook, drilling is expected to resume in Q2-2027. The company is also advancing its collaboration with Glencore to evaluate whether high-grade material can be processed directly at Glencore’s Horne Smelter, potentially eliminating the need for milling and reducing development costs and timelines. We anticipate an update on this initiative in the coming weeks. Successful tests could potentially pave the way for a joint project, or even an M&A opportunity, making these tests highly anticipated.
The project hosts the historic Wedge deposit, mined from 1962–1968, producing 1.5 Mt at 2.88% copper, 0.65% lead, 1.81% zinc and 20.6 g/t silver, equivalent to ~100 Mlbs of CuEq. These grades are well above the 0.5–1% copper grades typical of global copper mines.
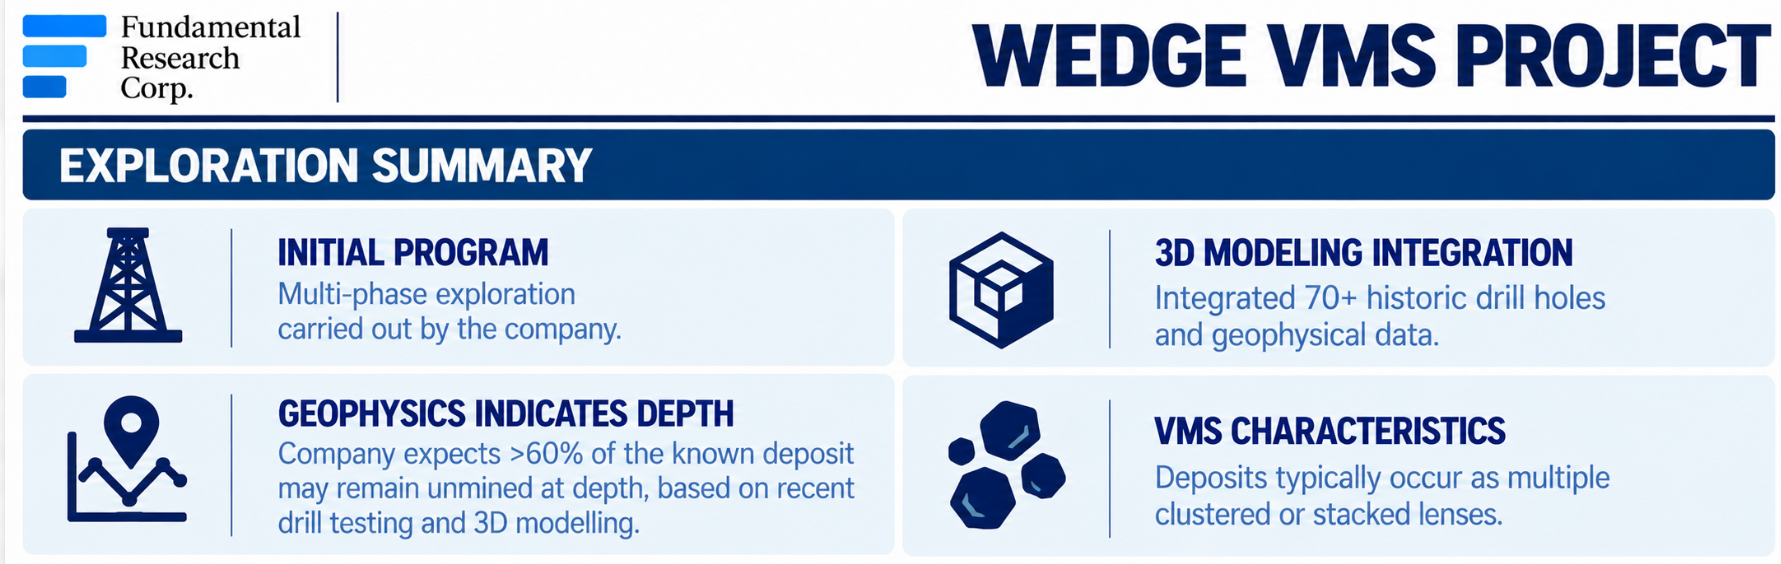
Mining ceased following an underground collapse, not due to a lack of resources. Historic studies suggest the mined area could contain an additional 38 Mlbs of CuEq. Only the upper portion of the deposit was mined, with recent studies and drilling suggesting the lower 60% remains unmined. Based on this, we believe the historic mine area could contain ~200 Mlbs of additional CuEq potential.
Management’s near-term goal is to evaluate the remaining mineralization within the historic mine area, and fully test several untested targets across the property.
The project is a historic underground mine with proven production. Past production de-risks the project, demonstrating high-grade ore and established processing methods. Borders NINE’s California Lake and Canoe Landing Lake projects; located 20 km southwest of Brunswick No. 12.
The project is located within 20 km of the permitted 3,000 tpd Caribou mill, offering potential access to existing processing infrastructure. Past exploration has identified four key targets: Main Wedge, Western Extension, Tribag and Eastern Extension.
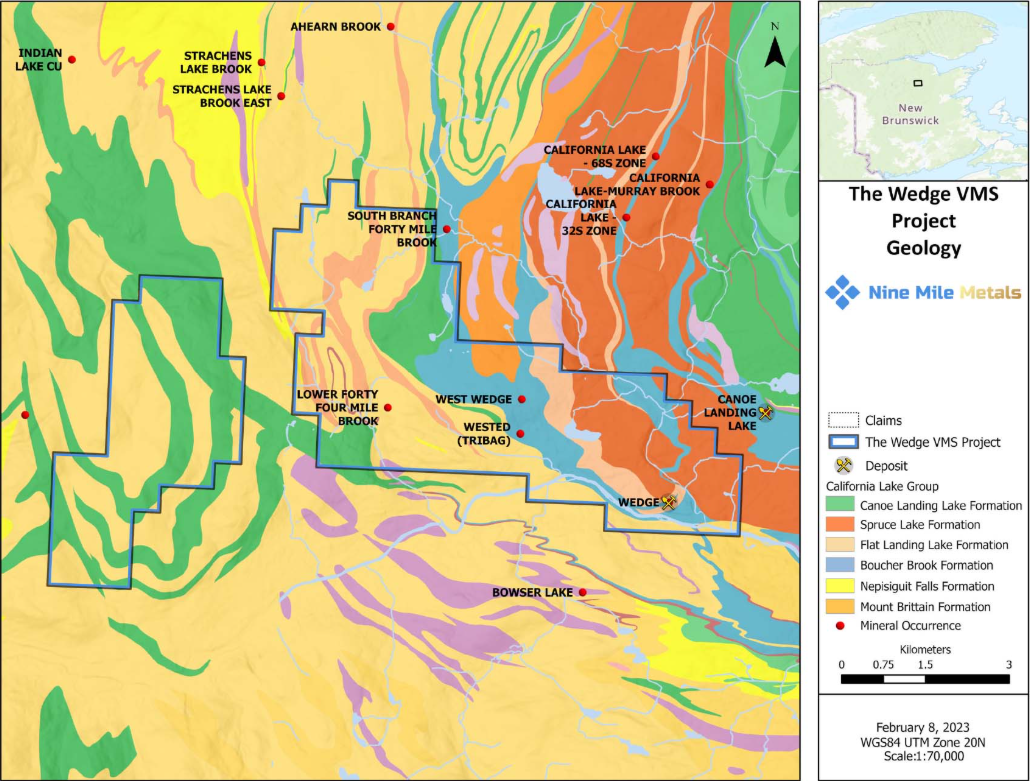
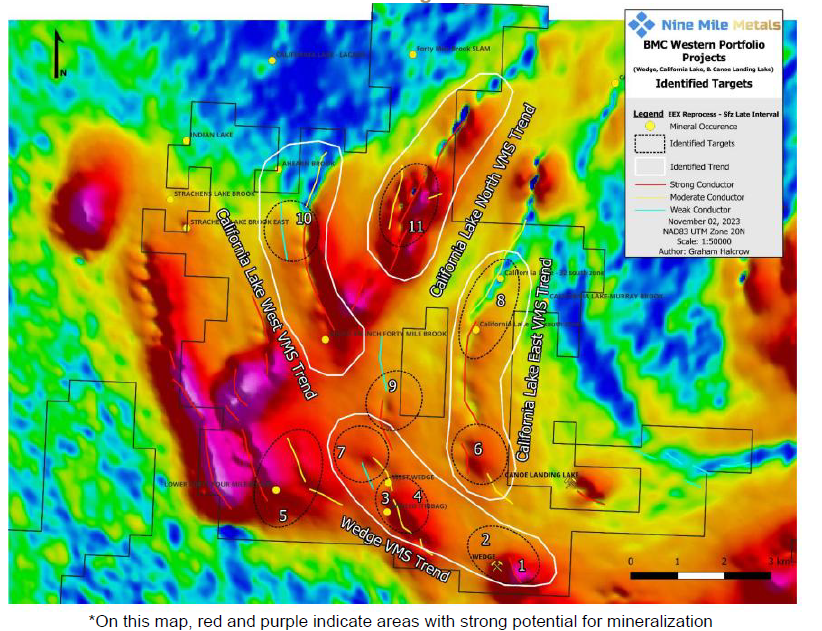
Exploration to date has focused primarily on the Wedge–Tribag area, marked as targets 1, 3 and 4 on the map to the right. In particular, Target 1 is located near the historic mine. All other targets remain largely untested.
Key Targets
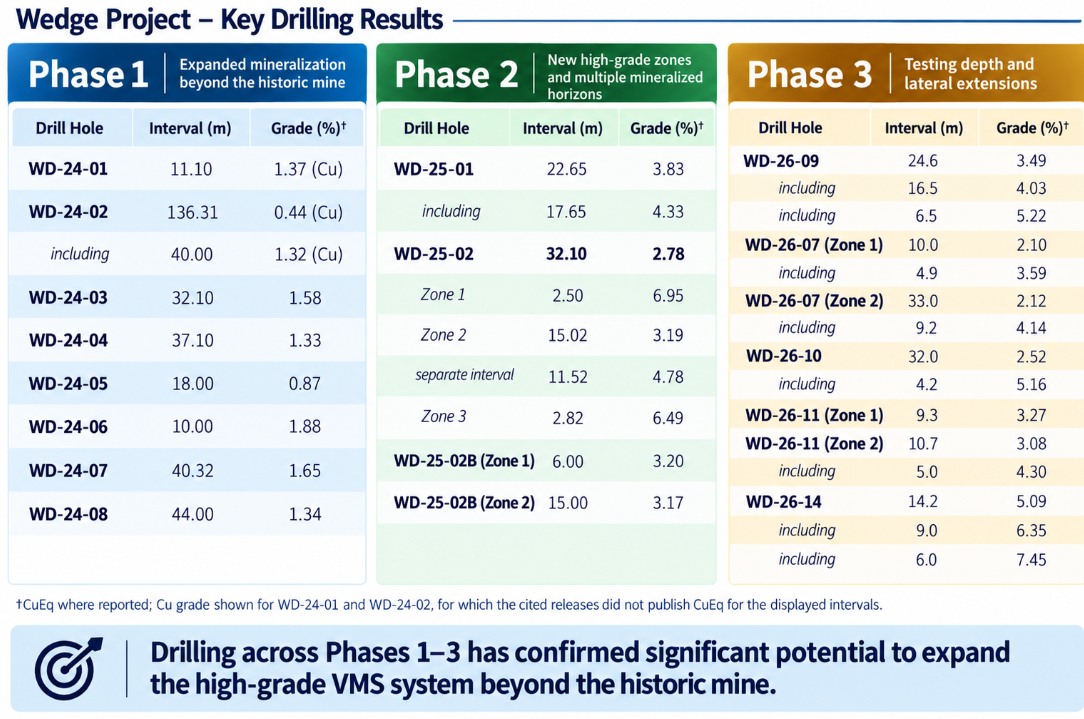
8,573 m have been drilled across 34 holes to date, all located near the historic mine. We believe phases 1–3 have demonstrated potential to expand the high-grade VMS system beyond the historic mine.
Drill Programs
| Program | Target | Drill Holes | Meters |
|---|---|---|---|
| Phase 1 (2024) | Eastern extension of the Wedge Mine | 9 | 1,984 |
| Phase 2 (2025) | Western extension of the Wedge Mine | 7 | 1,654 |
| Phase 3 (2026) | Wedge Mine Tribag-West Wedge targets |
18 | 4,935 |
Phase 1 expanded mineralization; Phase 2 identified multiple high-grade zones, and a new copper-rich lens; Phase 3 is testing depth, and lateral extensions. Overall, we estimate the weighted average grade across all three phases is ~2.4% CuEq, highlighting the high-grade nature of the mineralization.
2024-2026 Drill Highlights
| Phase 1 — Expanded mineralization beyond the historic mine | ||
|---|---|---|
| Drill Hole | Interval (m) | Grade (%)† |
| WD-24-01 | 11.10 | 1.37 (Cu) |
| WD-24-02 | 136.31 | 0.44 (Cu) |
| including | 40.00 | 1.32 (Cu) |
| WD-24-03 | 32.10 | 1.58 |
| WD-24-04 | 37.10 | 1.33 |
| WD-24-05 | 18.00 | 0.87 |
| WD-24-06 | 10.00 | 1.88 |
| WD-24-07 | 40.32 | 1.65 |
| WD-24-08 | 44.00 | 1.34 |
| Phase 2 — New high-grade zones and multiple mineralized horizons | ||
|---|---|---|
| Drill Hole | Interval (m) | Grade (%)† |
| WD-25-01 | 22.65 | 3.83 |
| including | 17.65 | 4.33 |
| WD-25-02 | 32.10 | 2.78 |
| Zone 1 | 2.50 | 6.95 |
| Zone 2 | 15.02 | 3.19 |
| separate interval | 11.52 | 4.78 |
| Zone 3 | 2.82 | 6.49 |
| WD-25-02B (Zone 1) | 6.00 | 3.20 |
| WD-25-02B (Zone 2) | 15.00 | 3.17 |
| Phase 3 — Testing depth and lateral extensions | ||
|---|---|---|
| Drill Hole | Interval (m) | Grade (%)† |
| WD-26-09 | 24.6 | 3.49 |
| including | 16.5 | 4.03 |
| including | 6.5 | 5.22 |
| WD-26-07 (Zone 1) | 10.0 | 2.10 |
| including | 4.9 | 3.59 |
| WD-26-07 (Zone 2) | 33.0 | 2.12 |
| including | 9.2 | 4.14 |
| WD-26-10 | 32.0 | 2.52 |
| including | 4.2 | 5.16 |
| WD-26-11 (Zone 1) | 9.3 | 3.27 |
| WD-26-11 (Zone 2) | 10.7 | 3.08 |
| including | 5.0 | 4.30 |
| WD-26-14 | 14.2 | 5.09 |
| including | 9.0 | 6.35 |
| including | 6.0 | 7.45 |
To date, 18 holes (4,935 m) have been completed under the 10,000 m phase three program, with results released for five holes, and assays pending for 13. Management is targeting a maiden resource by Q4-2027, with a longer-term goal of defining a ~10 Mt regional resource across multiple VMS deposits. We believe this is a reasonable exploration target, given that VMS deposits commonly occur in clusters, and individual deposits can range from <1 Mt to several million tonnes.
Strong balance sheet: Sufficient funding for the next 12 months, with no near-term need for dilution.
| (in C$) (FYE - Sep 30) | Q3-FY2026 |
|---|---|
| Cash | $4,917,772 |
| Working Capital | $4,982,397 |
| Current Ratio | 18.74 |
| Debt | - |
| Monthly Burn Rate (G&A) | -$92,159 |
| Cash Spent on Properties | -$863,493 |
| Cash from Financing Activities | $6,988,099 |
NINE can raise up to $3M from in-the-money options and warrants.
| Options | # | Exercise Price (C$) | Amount |
|---|---|---|---|
| Total | 17,500,000 | $0.09 | $1,542,000 |
| In-the-Money | 15,500,000 | $0.08 | $1,254,000 |
| Warrants | # | Exercise Price (C$) | Amount |
|---|---|---|---|
| Total | 63,497,064 | $0.18 | $11,316,053 |
| In-the-Money | 29,935,693 | $0.05 | $1,500,985 |
We estimate the historic mine area alone could host ~300 Mlbs of CuEq (~100 Mlbs historically mined, with ~200 Mlbs potentially remaining). We now value the Wedge project based on 400 Mlbs of CuEq potential, up from our previous estimate of ~300 Mlbs, reflecting the upside from additional exploration targets. For conservatism, we assign no value to Nine Mile Brook or the company’s other projects, as their resource potential remains too early to quantify.
We continue to value NINE using a peer group comprising only high-grade copper juniors. Since our previous report in April 2026, the peer group’s average EV/resource has declined from $0.20 to $0.19/lb of CuEq. By comparison, NINE is trading at just $0.05/lb, a 72% discount. Applying the peer group average multiple to our speculative estimate on Wedge, we derive a fair value estimate of $0.37/share (previously $0.32/share).
| Copper Juniors | Country | EV (C$,M) | EV/ Resource (C$/lb) |
|---|---|---|---|
| Faraday Copper | U.S. | $1,379 | $0.25 |
| Firefly Metals | Canada | $1,132 | $0.24 |
| KGL Resources | Australia | $314 | $0.24 |
| Cygnus Metals | Canada | $176 | $0.23 |
| Entrée Resources | Mongolia | $666 | $0.18 |
| Canadian Copper | Canada | $120 | $0.17 |
| Trilogy Metals | U.S. | $640 | $0.16 |
| Arizona Sonoran Copper (acquired) |
U.S. | $1,579 | $0.13 |
| Cyprium Metals | Australia | $230 | $0.11 |
| Selkirk Copper | Canada | $151 | $0.09 |
| Nine Mile Metals | Canada | $21 | $0.05 |
| Average (higher-grade) | $0.19 |
We reiterate our BUY rating, and raise our fair value estimate from $0.32 to $0.37/share. The Wedge project offers significant exploration upside, supported by high-grade drill results, and its location in the established BMC. With a maiden resource targeted for Q4-2027, further drilling results, and pending Glencore processing test updates for the Nine Mile Brook project, we anticipate several catalysts could support the stock.
We are maintaining our risk rating of 5 (Highly Speculative). We believe the company is exposed to the following key risks (not exhaustive):
Sid Rajeev, B.Tech, MBA, CFA — Head of Research, Fundamental Research Corp.
Nina Rose Coderis, B.Sc (Geology) — Equity Analyst, Fundamental Research Corp.
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Buy – Fair value is 12% above the current market price; or risk and reward is favorable
Hold – Fair value is between 5% to 12% above the current market price
Sell – Fair value is 5% above, or less, than the current market value; or risk and reward is unfavorable
Suspended or Rating N/A— Coverage and ratings suspended until more information can be obtained from the company regarding recent events.
1 (Low Risk) - The company operates in an industry where it has a strong position (for example a monopoly, high market share etc.) or operates in a regulated industry. The future outlook is stable or positive for the industry. The company generates positive free cash flow and has a history of profitability. The capital structure is conservative with little or no debt.
2 (Below Average Risk) - The company operates in an industry where the fundamentals and outlook are positive. The industry and company are relatively less sensitive to systematic risk than companies with a Risk Rating of 3. The company has a history of profitability and has demonstrated its ability to generate positive free cash flows (though current free cash flow may be negative due to capital investment). The company’s capital structure is conservative with little to modest use of debt.
3 (Average Risk) - The company operates in an industry that has average sensitivity to systematic risk. The industry may be cyclical. Profits and cash flow are sensitive to economic factors although the company has demonstrated its ability to generate positive earnings and cash flow. Debt use is in line with industry averages, and coverage ratios are sufficient.
4 (Speculative) - The company has little or no history of generating earnings or cash flow. Debt use is higher. These companies may be in start-up mode or in a turnaround situation. These companies should be considered speculative.
5 (Highly Speculative) - The company has no history of generating earnings or cash flow. They may operate in a new industry with new, and unproven products. Products may be at the development stage, testing, or seeking regulatory approval. These companies may run into liquidity issues and may rely on external funding. These stocks are considered highly speculative.
Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE.
Analyst Certification: The views expressed in this report accurately reflect the personal views of the analyst, and no part of their compensation was, is, or will be directly or indirectly related to the specific recommendation or views expressed.
Any “forward looking statements” are our best estimates and opinions based upon information that is publicly available and that we believe to be correct, but we have not independently verified with respect to truth or correctness. There is no guarantee that our forecasts will materialize. Actual results will likely vary. The analyst and Fundamental Research Corp. “FRC” does not own any shares of the subject company, does not make a market or offer shares for sale of the subject company, and does not have any investment banking business with the subject company. Fees ranging between $20,000 and $30,000 have been paid to FRC by Nine Mile Metals Ltd. to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. FRC takes steps to mitigate conflicts including setting fees in advance and utilizing analysts who must abide by CFA Institute Code of Ethics and Standards of Professional Conduct. Additionally, analysts may not trade in any security under coverage. Our full editorial control of all research, timing of release of the reports, and release of liability for negative reports are protected contractually. The issuer has agreed to a minimum coverage term and coverage cannot be unilaterally terminated. Distribution procedure: our reports are distributed first to our web-based subscribers on the date shown on this report then made available to delayed access users through various other channels for a limited time.
The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (22%).
This report contains "forward looking" statements. Forward-looking statements regarding the Company and/or stock’s performance inherently involve risks and uncertainties that could cause actual results to differ from such forward-looking statements. Factors that would cause or contribute to such differences include, but are not limited to, continued acceptance of the Company's products/services in the marketplace; acceptance in the marketplace of the Company's new product lines/services; competitive factors; new product/service introductions by others; technological changes; dependence on suppliers; systematic market risks and other risks discussed in the Company's periodic report filings, including interim reports, annual reports, and annual information forms filed with the various securities regulators. By making these forward-looking statements, Fundamental Research Corp. and the analyst/author of this report undertakes no obligation to update these statements for revisions or changes after the date of this report. A report initiating coverage will most often be updated quarterly while a report issuing a rating may have no further or less frequent updates because the subject company is likely to be in earlier stages where nothing material may occur quarter to quarter.
Fundamental Research Corp DOES NOT MAKE ANY WARRANTIES, EXPRESSED OR IMPLIED, AS TO RESULTS TO BE OBTAINED FROM USING THIS INFORMATION AND MAKES NO EXPRESS OR IMPLIED WARRANTIES OR FITNESS FOR A PARTICULAR USE. ANYONE USING THIS REPORT ASSUMES FULL RESPONSIBILITY FOR WHATEVER RESULTS THEY OBTAIN FROM WHATEVER USE THE INFORMATION WAS PUT TO. ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST. WHETHER A STOCK SHOULD BE INCLUDED IN A PORTFOLIO DEPENDS ON ONE’S RISK TOLERANCE, OBJECTIVES, SITUATION, RETURN ON OTHER ASSETS, ETC. ONLY YOUR INVESTMENT ADVISOR WHO KNOWS YOUR UNIQUE CIRCUMSTANCES CAN MAKE A PROPER RECOMMENDATION AS TO THE MERIT OF ANY PARTICULAR SECURITY FOR INCLUSION IN YOUR PORTFOLIO. This REPORT is solely for informative purposes and is not a solicitation or an offer to buy or sell any security. It is not intended as being a complete description of the company, industry, securities or developments referred to in the material. Any forecasts contained in this report were independently prepared unless otherwise stated and HAVE NOT BEEN endorsed by the Management of the company which is the subject of this report. Additional information is available upon request. THIS REPORT IS COPYRIGHT. YOU MAY NOT REDISTRIBUTE THIS REPORT WITHOUT OUR PERMISSION. Please give proper credit, including citing Fundamental Research Corp and/or the analyst, when quoting information from this report. The information contained in this report is intended to be viewed only in jurisdictions where it may be legally viewed and is not intended for use by any person or entity in any jurisdiction where such use would be contrary to local regulations or which would require any registration requirement within such jurisdiction.


Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.