
We reiterate our BUY rating, and lower our fair value estimate from $53.01 to $43.86/share, based on the average of our DCF and comparables valuations. We believe ZEPP’s strong balance sheet, broader product lineup, and higher-priced products offer meaningful upside, despite near-term earnings pressure and negative sector sentiment.
Premiumization Gains Traction as Global Smartwatch Shipments Contract
Paused · 9:49 left · FRC · read by an AI voice
Disclosure: Zepp Health Corporation has paid FRC a fee for research coverage and distribution of reports. This fee creates a potential conflict of interest which readers should consider. See last page for other important disclosures, rating, and risk definitions.
All figures in US$ unless otherwise specified.
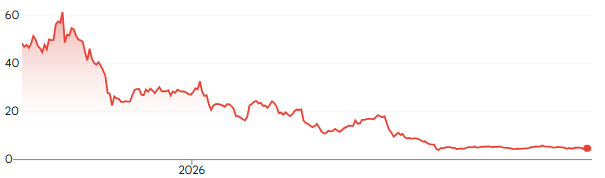
Price and Volume (1-year)
| YTD | 12M | |
|---|---|---|
| ZEPP | -86% | -93% |
| NYSE | 8% | 10% |
| Index* | 38% | 8% |
| Key Financial Data ($, 000s; except EPS) YE: Dec 31st |
2023 | 2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|---|
| Cash | $140,469 | $110,735 | $112,933 | $94,178 | $80,642 |
| Working Capital | $161,621 | $56,197 | $6,681 | -$41,364 | -$53,484 |
| Total Assets | $635,519 | $528,593 | $564,836 | $558,318 | $557,282 |
| LT-Debt | $120,020 | $75,241 | $59,475 | $40,043 | $40,043 |
| Revenue | $351,459 | $182,603 | $258,897 | $304,213 | $323,982 |
| Gross Profit | $92,646 | $70,234 | $99,190 | $118,643 | $126,353 |
| Net Income | -$29,877 | -$75,733 | -$40,068 | -$26,192 | -$9,804 |
| EPS | -$0.12 | -$0.29 | -$0.16 | -$0.10 | -$0.04 |
In Q2, Huawei overtook Apple as the world’s largest smartwatch brand. Zepp ranks seventh globally, maintaining its position. For context, Huawei ships ~35M units annually; Zepp ships ~3-4M.
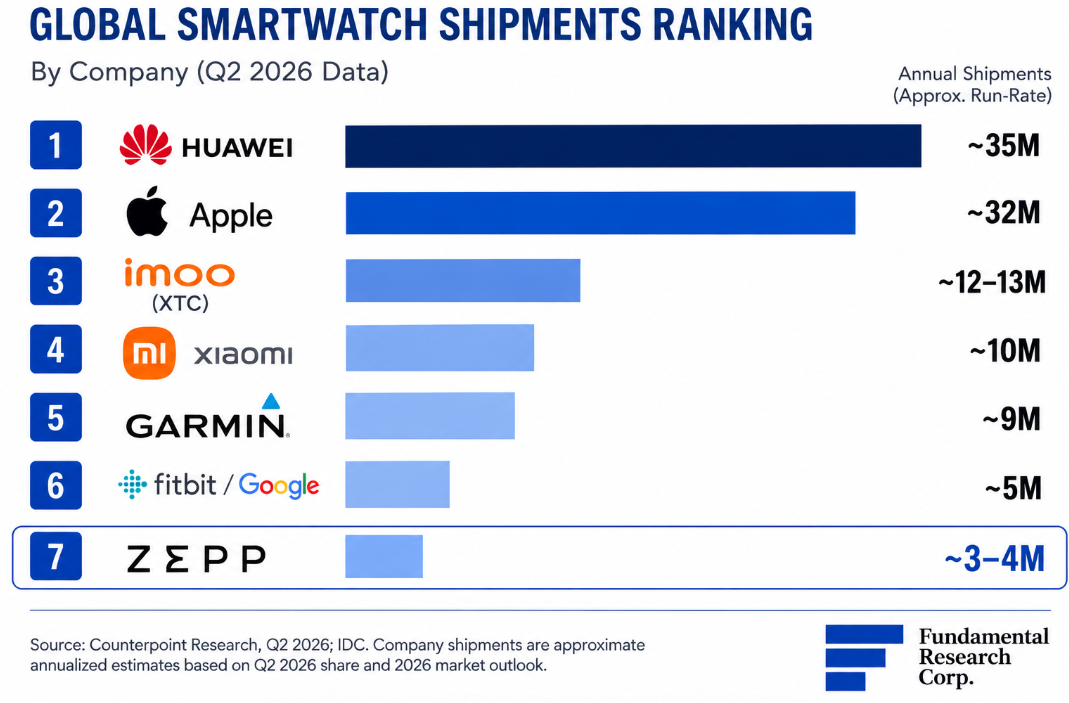
Zepp shipments fell 14% YoY in Q2, reflecting a 4% YoY decline in global smartwatch unit sales, and temporary supply constraints affecting select products; management expects supply to normalize by Q4.
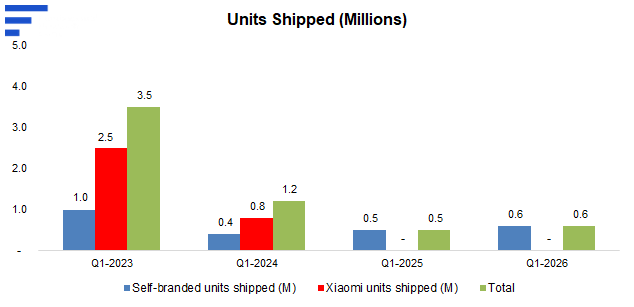
Revenue: Up 7% YoY, 3% below our forecast, driven by higher selling prices (up 25% YoY), partially offset by lower shipments (down 14% YoY).
| Segmented Revenue | Q1-2025 | Q1-2026 | YoY | Q2-2025 (US$) | Q2-2026 (US$) | YoY | H1-2025 (US$) | H1-2026 (US$) | YoY |
|---|---|---|---|---|---|---|---|---|---|
| Self-branded products (000s) | $38,537 | $51,547 | 34% | $59,406 | $63,525 | 7% | $97,943 | $115,072 | 17% |
| Xiaomi wearable products (000s) | - | - | n/a | - | - | N/A | - | - | N/A |
| Total (000s) | $38,537 | $51,547 | 34% | $59,406 | $63,525 | 7% | $97,943 | $115,072 | 17% |
| % Self-branded products | 100% | 100% | 100% | 100% | 100% | 100% | |||
| % Xiaomi wearable products | 0% | 0% | 0% | 0% | 0% | 0% | |||
| Self-branded units shipped (M) | 0.5 | 0.6 | 20% | 0.7 | 0.6 | -14% | 1.2 | 1.2 | 0% |
| Xiaomi units shipped (M) | - | - | n/a | - | - | N/A | - | - | N/A |
| Total | 0.5 | 0.6 | 20% | 0.7 | 0.6 | -14% | 1.2 | 1.2 | 0% |
| Price per Self-branded unit | $77 | $86 | 11% | $85 | $106 | 25% | $82 | $96 | 17% |
| Price per Xiaomi unit | - | - | n/a | - | - | N/A | - | - | N/A |
| Average | $77 | $86 | 11% | $85 | $106 | 25% | $82 | $96 | 17% |
In line with industry standards, Zepp retains 70% of the retail price of its products as revenue, while retailers and distributors keep the remaining 30%; Zepp does not disclose segmented results; Smart wristbands, and watches, constitute 90%+ of revenue; Self-Branded Products - Europe & the Middle East account for 50% of sales, followed by North America (15-20%), China (10%), and the rest of the world (15-30%); Xiaomi owns 20% of Zepp’s outstanding shares.
Gross Margins: Up 1.2 pp YoY, in line with our estimate, and the wearable tech sector (38%), but above the consumer electronics sector (26%).
| Margins | Q1-2025 | Q1-2026 | Q2-2025 | Q2-2026 | H1-2025 | H1-2026 | Sector |
|---|---|---|---|---|---|---|---|
| Gross | 37.3% | 37.7% | 36.2% | 37.4% | 36.6% | 37.5% | 25.7% |
| EBITDA | -46.0% | -33.4% | -9% | -19% | -23.6% | -25.2% | 8.7% |
| EBIT | -47.7% | -34.3% | -10% | -19% | -25.0% | -26.1% | 5.1% |
| Net | -51.2% | -38.1% | -13% | -18% | -28.1% | -26.9% | 0.8% |
| Expenses as % of Revenue | Q1-2025 | Q1-2026 | Q2-2025 | Q2-2026 | H1-2025 | H1-2026 |
|---|---|---|---|---|---|---|
| G&A | 16.9% | 14.3% | 7.4% | 9.8% | 11.1% | 11.8% |
| R&D | 30.5% | 24.5% | 17.6% | 17.4% | 22.7% | 20.6% |
| Selling & Marketing | 35.9% | 32.3% | 20.3% | 28.8% | 26.4% | 30.4% |
We believe new higher-priced product launches should support margin growth in 2026. However, operating expenses were up 32% YoY, 11% above our forecast, driven by prepaid marketing, new product launch campaigns, and sponsorships for new athletes; with most major product launches for the year completed, OPEX should decline in coming quarters.
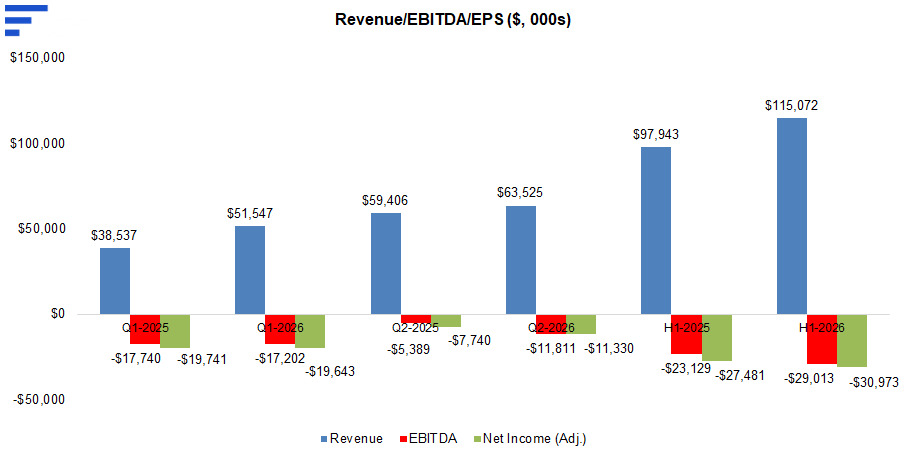
EPS: Declined YoY from ($0.03) to ($0.04), below our forecast of ($0.03), primarily due to higher operating expenses. Additionally, net Cash & Investments: $140M ($9.71/share) vs. the current share price of $3.91, implying the stock trades well below liquid asset value.
| Liquidity and Capital Structure | 2023 | 2024 | 2025 | Q1-2026 | Q2-2026 | Sector |
|---|---|---|---|---|---|---|
| Cash | 140,469 | 110,735 | 112,933 | 103,151 | 106,269 | |
| Working Capital | 161,621 | 56,197 | 6,681 | -35,000 | -31,864 | |
| Current Ratio | 2.04 | 1.29 | 1.02 | 0.88 | 0.90 | 1.30 |
| Total Debt | 188,701 | 178,773 | 226,928 | 238,132 | 244,911 | |
| LT-Debt | 120,020 | 75,241 | 59,475 | 40,043 | 56,397 | |
| Total Debt / Capital | 35% | 41% | 51% | 55% | 57% | 29% |
| LT Debt / Capital | 22% | 17% | 13% | 9% | 13% | 18% |
Global smartwatch shipments fell 4% YoY in Q2, and are expected to decline 2% in 2026, due to longer replacement cycles.
Market Share and Growth
| 2023 | 2023 | 2024 | 2025 | 2026E | |
|---|---|---|---|---|---|
| Global Smartwatch Shipments (Millions) | 161 | 161 | 154 | 164 | 160 |
| Zepp's Market Share (self-branded) | 2.6% | 2.6% | 1.5% | 1.8% | 2.0% |
| Zepp's Growth (self-branded) | -33.3% | -33.3% | -45.2% | 30.4% | 5.7% |
| Global Growth | 8.1% | 8.1% | -4.3% | 6.5% | -2.4% |
Zepp products accounted for 1.8% of global smartwatch shipments in 2025; we anticipate this increasing to 2.0% in 2026, driven by a broader product lineup.
| US$, 000s (except EPS) |
2026E (Old) | 2026E (New) | 2027E (Old) | 2027E (New) |
|---|---|---|---|---|
| Revenue | $313,164 | $304,213 | $356,359 | $323,982 |
| EBITDA | -$783 | -$18,253 | $22,451 | -$1,620 |
| Net Profit | -$8,722 | -$26,192 | $12,127 | -$9,804 |
| EPS | -$0.03 | -$0.10 | $0.05 | -$0.04 |
Zepp’s Q3 revenue guidance implies a 4%–10% YoY decline, below our forecast, due to market weakness, and supply constraints expected to ease by Q4. As a result, we are lowering our revenue and EPS forecasts. We now expect profitability in 2028 vs. 2027 previously. Consequently, our DCF valuation declined from $40 to $32/share.
| DCF Model (US$, 000s) | 2026E | 2027E | 2030E | Terminal |
|---|---|---|---|---|
| EBIT (1-tax) | (15,249) | (2,852) | 52,988 | |
| Non-Cash Expenses | 4,579 | 4,683 | 5,027 | |
| Change in Working Capital | (1,347) | (1,414) | (1,637) | |
| Cash from Operations | (12,017) | 417 | 56,378 | |
| CAPEX | (7,000) | (7,000) | (7,000) | |
| Free Cash Flow | (19,017) | (6,583) | 49,378 | |
| Present Value | (15,716) | (4,946) | 27,872 | 410,124 |
| Discount Rate | 10.0% | |||
| Terminal Growth | 3.0% | |||
| Present Value (US$) | $463,142,239 | |||
| Cash - Debt (US$) | $51,040,250 | |||
| Fair Value (US$) | $514,182,489 | |||
| Shares O/S | 15,845,828 | |||
| Value per Share (US$) | $32.45 | |||
Sector EV/forward revenue is down 7% since our previous report in July 2026. Notably, ZEPP remains undervalued, trading at just 0.10x forward revenue (previously 0.14x), well below the sector average of 3.49x (previously 3.74x). Applying 3.49x to our 2026 revenue forecast for Zepp, we arrived at a comparables valuation of $55/share (previously $66/share).
| Zepp vs Major Wearable Tech Companies | MCAP ($M) | Revenue (US$M) | Gross Margin | EV/R (f) |
|---|---|---|---|---|
| Apple | $4,858,257 | $466,823 | 49% | 10.04 |
| Samsung | $1,309,501 | $356,124 | 58% | 2.18 |
| Sony | $138,294 | $81,846 | 32% | 1.72 |
| Xiaomi | $78,319 | $65,239 | 21% | 1.05 |
| Garmin | $55,063 | $7,671 | 60% | 6.29 |
| iFlytek | $13,334 | $4,142 | 42% | 3.11 |
| Andon Health | $3,779 | $169 | 62% | N/A |
| Ambarella | $3,013 | $418 | 59% | 6.24 |
| Kopin | $874 | $44 | 20% | 14.03 |
| Cosonic Intelligent | $653 | $335 | 11% | 1.80 |
| Vuzix | $252 | $6 | n/a | n/a |
| GoPro | $245 | $569 | 28% | 0.56 |
| Immersion | $241 | $1,733 | 22% | n/a |
| QuickLogic | $213 | $16 | 27% | 8.49 |
| Zepp Health | $62 | $304 | 38% | 0.10 |
| Average | 38% | 3.49 |
Oura, a leading smart-ring company, recently postponed its IPO amid market uncertainty, and investor concerns over valuation. We believe declining smartwatch sales may have also contributed to caution toward the wearables sector.
We reiterate our BUY rating, and lower our fair value estimate from $53.01 to $43.86/share, based on the average of our DCF and comparables valuations. We believe ZEPP’s strong balance sheet, broader product lineup, and higher-priced products offer meaningful upside, despite near-term earnings pressure and negative sector sentiment. ZEPP trades at a 97% discount to the sector on forward revenue, offering an attractive entry point.
We are maintaining our risk rating of 3 (Average).
We believe the company is exposed to the following key risks (not exhaustive):
| INCOME STATEMENTS (000s) YE: December 31st |
2023 | 2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|---|
| Revenue | $352,860 | $182,603 | $258,897 | $304,213 | $323,982 |
| Cost of Sales | $260,502 | $112,369 | $159,707 | $185,570 | $197,629 |
| Gross Profit | $92,358 | $70,234 | $99,190 | $118,643 | $126,353 |
| G&A | $26,778 | $24,854 | $29,273 | $33,463 | $34,018 |
| R&D | $49,218 | $43,892 | $43,008 | $42,590 | $38,878 |
| Selling & Marketing | $44,527 | $46,471 | $53,829 | $60,843 | $55,077 |
| EBITDA | -$28,165 | -$44,983 | -$26,920 | -$18,253 | -$1,620 |
| D&A | $2,285 | $2,267 | $2,310 | $2,079 | $2,183 |
| EBIT | -$30,450 | -$47,250 | -$29,230 | -$20,332 | -$3,803 |
| Interest | $6,752 | $5,552 | $5,697 | $5,860 | $6,001 |
| EBT | -$37,202 | -$52,802 | -$34,927 | -$26,192 | -$9,804 |
| Tax | -$2,430 | $13,693 | $2,537 | ||
| Unusual/Non-recurring expense | -$3,686 | $9,313 | $2,604 | ||
| Non-controlling interest | -$66 | -$75 | |||
| Net Income | -$31,020 | -$75,733 | -$40,068 | -$26,192 | -$9,804 |
| EPS | -$0.13 | -$0.29 | -$0.16 | -$0.10 | -$0.04 |
| CASH FLOW STATEMENTS (000s) YE: December 31st |
2026E | 2027E |
|---|---|---|
| Operating Activities | ||
| Net income | -$26,192 | -$9,804 |
| Depreciation & amortization | $2,079 | $2,183 |
| Share-based compensation | $2,500 | $2,500 |
| Items Not Involving Cash | -$21,613 | -$5,121 |
| Changes in WC | -$1,347 | -$1,414 |
| Cash From Operations | -$22,959 | -$6,535 |
| Investing activities | ||
| PP&E / Intangible assets | -$7,000 | -$7,000 |
| Others | ||
| Cash Used in Investing Activities | -$7,000 | -$7,000 |
| Financing activities | ||
| Debt | $11,204 | - |
| Cash Provided by Financing Activities | $11,204 | - |
| BALANCE SHEETS (000s) YE: December 31st |
2023 | 2024 | 2025 | 2026E | 2027E |
|---|---|---|---|---|---|
| Assets | |||||
| Cash | $140,469 | $110,735 | $112,933 | $94,178 | $80,642 |
| Trade & receivables | $69,332 | $65,628 | $73,573 | $77,252 | $81,114 |
| Short term investments | $5,153 | $997 | |||
| Inventory | $84,887 | $56,789 | $72,756 | $76,394 | $80,213 |
| Other current assets | $16,891 | $17,415 | $34,263 | $34,263 | $34,263 |
| Current Assets | $316,732 | $251,564 | $293,525 | $282,086 | $276,233 |
| PP&E & intangible assets | $18,797 | $13,989 | $19,273 | $24,194 | $29,011 |
| Long term investments | $238,540 | $225,910 | $220,047 | $220,047 | $220,047 |
| Other long term assets | $61,450 | $37,130 | $31,991 | $31,991 | $31,991 |
| Total Assets | $635,519 | $528,593 | $564,836 | $558,318 | $557,282 |
| Liabilities & Shareholders' Equity | |||||
| Payables and accrued liabilities | $86,430 | $91,835 | $119,391 | $125,361 | $131,629 |
| Debt | $68,681 | $103,532 | $167,453 | $198,089 | $198,089 |
| Current Liabilities | $155,111 | $195,367 | $286,844 | $323,450 | $329,718 |
| Borrowings | $120,020 | $75,241 | $59,475 | $40,043 | $40,043 |
| Lease liabilities | $3,197 | $2,007 | $1,102 | $1,102 | $1,102 |
| Tax liabilities & Other | $4,439 | $3,250 | $2,882 | $2,882 | $2,882 |
| Total Liabilities | $282,767 | $275,865 | $350,303 | $367,477 | $373,745 |
| Equity | $352,752 | $252,728 | $214,533 | $190,841 | $183,538 |
| Total Liabilities and SE | $635,519 | $528,593 | $564,836 | $558,318 | $557,282 |
Sid Rajeev, B.Tech, MBA, CFA — Head of Research, Fundamental Research Corp.
The full report — the designed PDF with all charts and the complete disclosure — remains available as published, free of charge with a free account. This page is the same analysis in the form a search engine, an AI assistant and a phone screen can read.
Disclosures. Fees ranging between $20,000 and $30,000 have been paid to FRC by Zepp Health to commission this report, research coverage, and distribution of reports. This fee creates a potential conflict of interest which readers should consider. The analyst and Fundamental Research Corp. “FRC” do not own any shares of the subject company, do not make a market or offer shares for sale of the subject company, and do not have any investment banking business with the subject company. Definition of FRC’s Fair Value Estimate – Our fair value estimate is the theoretical value of the company’s equity using widely accepted methods of valuation such as discount cash flow or comparables. IT IS NOT A TARGET PRICE or PREDICTION OF THE FUTURE STOCK PRICE. Buy – Fair value is 12% above the current market price; or risk and reward is favorable. 3 (Average Risk) - The company operates in an industry that has average sensitivity to systematic risk. The industry may be cyclical. Profits and cash flow are sensitive to economic factors although the company has demonstrated its ability to generate positive earnings and cash flow. Debt use is in line with industry averages, and coverage ratios are sufficient. The distribution of FRC’s ratings are as follows: BUY (76%), HOLD (2%), SELL / SUSPEND (22%). ALWAYS TALK TO YOUR FINANCIAL ADVISOR BEFORE YOU INVEST.




Discussion
Comments reflect the views of individual users, not FRC. Nothing posted in the comments section — by users or otherwise — should be taken as investment advice.